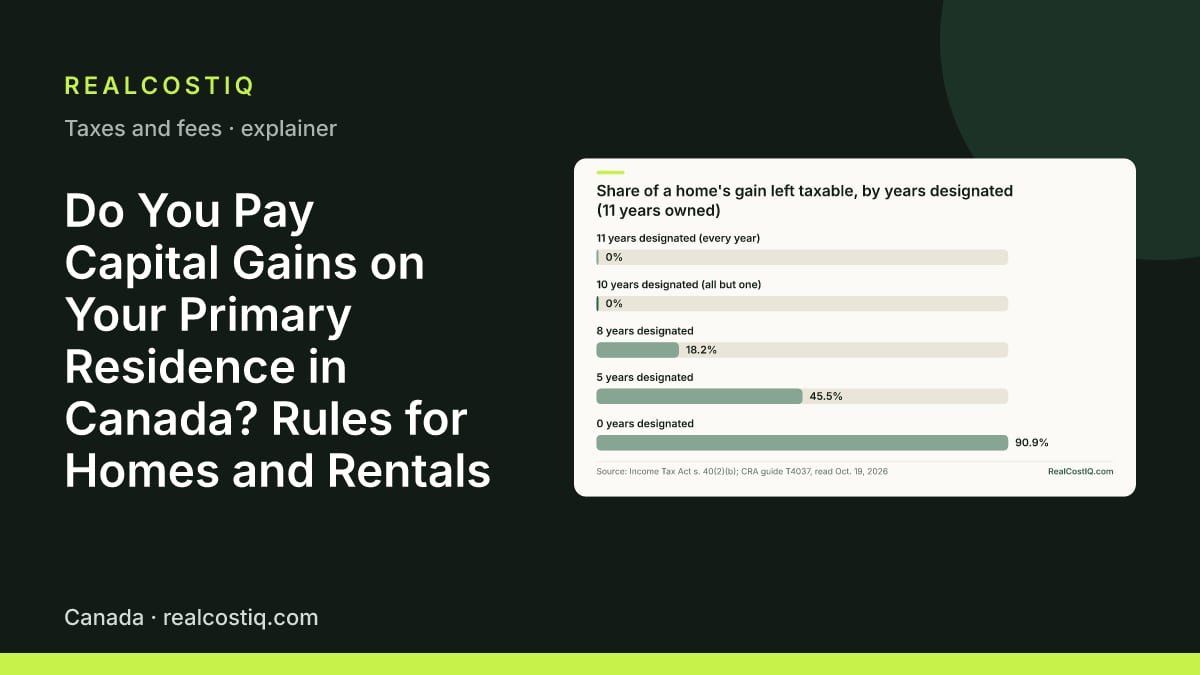
Selling a Canadian home leads to one of four very different tax outcomes. Which one applies depends on how you used the property, how long you held it and where you lived. A house you lived in for every year of ownership usually produces no tax at all. A rental produces a taxable capital gain, which is the profit you make on a sale. A rental often adds a second layer of income called recapture. A property held for less than 365 consecutive days is generally treated as business income rather than a capital gain. A non-resident seller faces a withholding mechanism, which holds back cash at closing. This post walks through each case with the arithmetic shown. Then the number on your Schedule 3, the part of your tax return for capital gains, will not be a surprise.
This post explains the rules. It is not tax advice for your situation. Several rules below involve elections and designations that are hard to undo. Have an accountant review the filing before you sign if the property was ever rented, had more than one owner, or was owned while you were not a Canadian resident. To run your own estimate by province, use the capital gains tax calculator after reading this. It has a principal residence mode for partial designation, a change of use and the flipping rule.
Do you pay capital gains on your primary residence in Canada?
Usually no. You generally pay no tax on the gain if the home was your principal residence for every year you owned it, or every year but one (CRA guide T4037, read 2026-10-19). Two conditions apply. You must report the sale on Schedule 3 and designate the home on Form T2091(IND), even when no tax is owed. And no other property can be designated as your family's principal residence for those years. The exception to watch is the flipping rule below, which can tax a home sold within 365 days. The same rules apply in every province, including Ontario, because capital gains tax is federal. Only the tax rate on the taxable half differs by province.
How long do you have to live in a house to avoid capital gains?
There is no minimum stay in the CRA guidance I read. The test is the number of years you designate the home as your principal residence, compared with the years you owned it. The home must be lived in by you, your spouse or partner, a former spouse or partner, or your child during each year you designate. The plus-one rule means one owned year can go undesignated and the gain is still fully exempt. In practice the 365-day flipping rule is the floor. If you sell a home you held for fewer than 365 consecutive days, the gain is generally business income, even if you lived in it. See the plus-one section for the formula and a table.
Penalty for selling a house before 1 year in Canada
There is no fee, but the tax treatment worsens. A Canadian housing unit held for fewer than 365 consecutive days is a flipped property, and the gain is generally treated as business income, not a capital gain (T4037 and the CRA principal residence page, read 2026-10-19). Business income is fully taxable, not taxed on one-half. Any loss is deemed to be nil. CRA says a home that would otherwise be your principal residence is taxable if it meets the flipped-property definition. Life events are exceptions, such as death, a relationship breakdown with at least 90 days apart, a threat to personal safety, serious illness or disability, a work or school move at least 40 km closer, involuntary job loss, insolvency, and destruction or expropriation of the home. Worked numbers are in the flipping rule section.
Capital gains on rental property in Canada
Yes, a rental property you never lived in is taxed on its capital gain. Half the gain is added to your income and taxed at your marginal rate, which is the rate on your last dollar of income. If you claimed capital cost allowance (CCA, the tax form of depreciation), you also add recapture to income in full. CRA says CCA claimed on a rental part of a home can lead to recapture or a terminal loss, worked out separately. If only part of your home was rented, you split the sale price and costs between the home and the rental part, and report only the rental part's gain. See CCA recapture for a worked example and the capital gains tax calculator for a provincial estimate.
Selling a rental property that used to be your primary residence
Renting out your home is a change in use, which CRA treats as a sale at fair market value followed by an immediate repurchase, even with no actual sale. You can elect under subsection 45(2) to avoid that deemed sale. The election lets you keep designating the home as your principal residence for up to four years while it is rented. You cannot claim CCA on it if you make that election. If you do not elect, the deemed gain is usually covered by the exemption for the years you lived there. The rental period then starts from the new value, and the later gain is taxed on one-half. If you move back in, subsection 45(3) lets you postpone reporting until you sell. CRA notes both elections have been available since March 19, 2019. Examples are in the change-in-use section.
How the gain is calculated
CRA's guide T4037 gives the formula in one line. Take the proceeds of disposition, subtract the adjusted cost base, and subtract outlays and expenses. The result is the capital gain. If the answer is negative, it is a capital loss. Under s. 38 of the Income Tax Act, one-half of a capital gain is the taxable capital gain. That half is added to your income for the year and taxed at your marginal rate. The other half is not taxed. (Your marginal rate is the tax rate on your last dollar of income.)
- Proceeds of disposition. This is generally the sale price. (A disposition is a sale or similar transfer.) For a deemed sale, such as a change in use, it is fair market value on the date of the change.
- Adjusted cost base (ACB). What you paid, plus the costs of buying and improving the property (see below).
- Outlays and expenses. The costs of selling. T4037 lists commissions, brokers' fees, surveyors' fees, legal fees, transfer taxes and advertising costs.
- Capital gain. Item 1 minus items 2 and 3.
- Taxable capital gain. One-half of the capital gain. It is reported on Schedule 3 and carried to line 12700 of your return.
What belongs in the adjusted cost base
T4037 defines the cost of a property as its price plus the expenses of acquiring it. It gives commissions and legal fees as examples. For a Canadian house, the usual acquisition costs are the legal fees on purchase and the land transfer tax or its equivalent paid to the province. (Land transfer tax rules are set by each province, and some cities add their own tax.) The rate is province-specific. Look it up for the province where you bought, using the land transfer tax calculator as a starting point. Use your province's own ministry of finance page as the authority.
Capital improvements, as opposed to repairs, are generally added to the ACB. A new addition, a finished basement or a replaced roof on a rental can raise your base. Painting and routine maintenance do not. On a rental property the line between the two matters. A repair is a current-year rental expense, and an improvement is capital. The records you need are the purchase statement of adjustments, the lawyer's reporting letter, and invoices for improvements. Keep them for as long as you own the property. Also keep them for the period CRA can ask for them after you sell.
A rental sale with no exemption
Assume these hypothetical figures. A rental was bought for C$400,000, with C$8,000 of legal fees and land transfer tax at purchase. It sells for C$700,000, with C$35,000 of commission, legal and advertising costs. Ignore CCA for now. The rental section below adds it.
| Step | Amount (CAD) |
|---|---|
| Proceeds of disposition | C$700,000 |
| Adjusted cost base (C$400,000 + C$8,000) | C$408,000 |
| Outlays and expenses on sale | C$35,000 |
| Capital gain (700,000 - 408,000 - 35,000) | C$257,000 |
| Taxable capital gain (one-half) | C$128,500 |
| Tax at an assumed 40% marginal rate (illustrative only) | C$51,400 |
The 40% marginal rate is an assumption to show the final step, not a quoted rate. Your rate depends on province, income and other items on your return. Use the capital gains tax calculator for a bracket-based estimate.
The principal residence exemption and the plus-one
A property qualifies as your principal residence when it fits this description. It is a housing unit, a leasehold interest in one, or a share of a co-operative housing corporation. You must have owned it in the year. It must also have been ordinarily inhabited in the year by you, your spouse or common-law partner, a former spouse or partner, or your child (Income Tax Act, s. 54). The definition includes the land under the home. It also includes contiguous land that reasonably contributes to its use and enjoyment as a residence. Where the total area exceeds half a hectare, the excess is excluded unless you show it was necessary. This matters for rural and cottage properties.
T4037 states the headline rule plainly. You can claim the exemption if the home was your principal residence for all the years you owned it, or for all the years but one. The second clause is the plus-one rule. The mechanism sits in s. 40(2)(b) of the Act. The exempt portion of the gain is worked out as the number of years the property was designated as your principal residence, plus one, divided by the number of years you owned it. The plus one is available only if you were resident in Canada in the year you acquired the property.
The plus one exists because of timing. Say you buy a new home and sell your old one in the same calendar year. Both would otherwise be needed for that year. A family unit can designate only one property per year (s. 54). So the extra year closes the gap. The formula is the arithmetic form of the same idea.
| Years designated | Exempt fraction (1 + designated) / 11 | Taxable fraction of the gain |
|---|---|---|
| 11 (every year) | Fully exempt (the fraction is capped at one) | 0% |
| 10 (all but one) | 11/11 | 0% |
| 8 | 9/11 (about 81.8%) | about 18.2% |
| 5 | 6/11 (about 54.5%) | about 45.5% |
| 0 | 1/11 (about 9.1%) | about 90.9% |
The fraction applies to the whole gain before the one-half inclusion rate. The plus-one assumes you were a Canadian resident in the year of acquisition. Years are tax years in which you owned the property at any time.
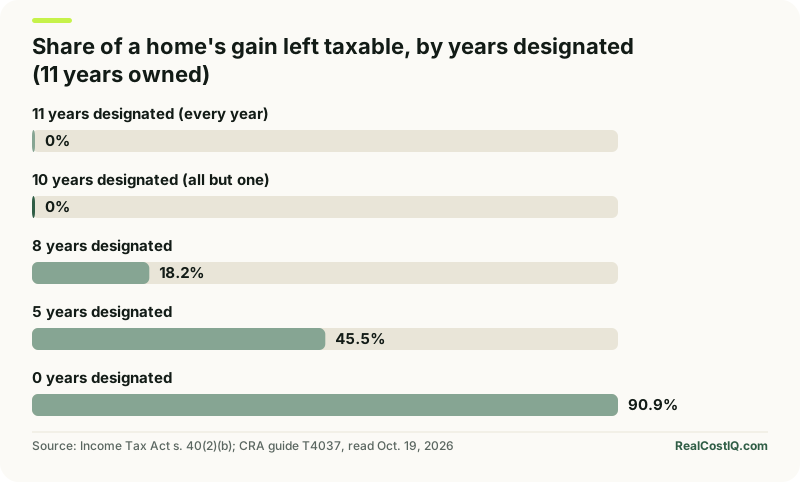
Worked example 2: a family with a house and a cottage
Hypothetical: a couple owns a house for 11 tax years and also owns a cottage. A family unit can designate only one property per year. So they designate the cottage for 3 of those years and the house for the other 8. The house sells for a capital gain of C$220,000 after ACB and selling costs.
- Exempt fraction for the house: (1 + 8) / 11 = 9/11.
- Gain not covered by the exemption: C$220,000 x 2/11 = C$40,000.
- Taxable capital gain at the one-half inclusion rate: C$20,000.
- The cottage must carry its own designation years and its own calculation when it is sold. The 3 years used on it cannot be reused on the house.
This is why couples with a second property need to plan designations before either property sells, not after. The designation is made only when you report the sale. So the arithmetic is a choice between the two properties across the years, not a default. Accountants model both orders. This post cannot do that for your facts.
Designating on Schedule 3 and Form T2091(IND)
A sale of a principal residence is reported on Schedule 3 of your return. It is designated on Form T2091(IND), Designation of a Property as a Principal Residence by an Individual. CRA's guidance says the form is required for dispositions in 2016 and later. You complete only the first page of it when the property qualified for all years of ownership or all but one. If you skip the reporting, the exemption is not automatic. CRA's published materials treat reporting the sale and the designation as a required step. So even a sale of an ordinary home should appear on your return when the resulting tax is nil.
Change in use: moving out, renting, moving back
When you start renting out a home you lived in, or move into a former rental, you are treated as having sold the property at fair market value and bought it back at that value. (Fair market value is the price the property would sell for.) This is called a deemed disposition. It applies even though no cash changes hands. It is the rule most sellers do not know about until the accountant asks when the rental started.
Subsection 45(2) lets you elect out when you convert a principal residence to a rental. You defer the deemed disposition. Under CRA's description, you can keep designating the property as your principal residence for up to four years without claiming CCA on it. Subsection 45(3) is the mirror, for converting a rental back to personal use. You postpone reporting the deemed disposition until the actual sale. But CRA says the election is not available if you or your spouse or common-law partner deducted CCA on the property for any tax year after 1984 and on or before the day the use changed. According to CRA, the four-year window can be extended in one case. That is where the move is tied to an employer relocation that brings you at least 40 kilometres closer to a new work location.
- No election, move out and rent. The deemed sale at fair market value is usually sheltered by the exemption for the years the home was your residence. The rental period then starts with a fresh ACB equal to that value. The property is no longer eligible for the exemption for later rental years.
- With a 45(2) election. There is no deemed sale. You cannot claim CCA for the years covered. The years in that window can still be designated as principal residence, which can keep a later sale fully exempt.
- Claiming CCA while renting. Claiming CCA does not mix with keeping the election's benefits. Check with an accountant before you take the first deduction.
Worked example 3: a deemed sale on change of use
Hypothetical: a home bought for C$450,000 is converted to a rental in 2020, when its fair market value is C$600,000. No 45(2) election is made. It sells in 2025 for C$720,000 with C$30,000 of selling costs.
- Deemed sale in 2020: proceeds C$600,000 less ACB C$450,000 = C$150,000 gain on that date. Suppose the home was the family's principal residence for every year it was owned up to then. The plus-one covers the year of the change. Then that C$150,000 is typically exempt.
- New ACB for the rental: C$600,000.
- Actual sale in 2025: C$720,000 - C$600,000 - C$30,000 = C$90,000 capital gain. One-half, C$45,000, is the taxable capital gain.
The key point is that the rental period is taxed from the new base. The earlier years stay inside the exemption only if the designation conditions are met. If the property carried CCA during the rental, the next section's recapture applies in addition.
Rentals: CCA recapture on top of the gain
Capital cost allowance (CCA) is the tax version of depreciation on a rental building. CRA's rental guide T4036 says land is not depreciable property. It says rental buildings are most commonly in Class 1 at 4%. It also says you cannot use CCA to create or increase a rental loss. CCA is optional every year. The cost of claiming it comes on sale. When you sell the property, the undepreciated capital cost (UCC) of the class may not equal zero. The UCC is the part of the cost you have not yet written off for tax. If it is negative, you add a recapture amount to income. If it is positive, you may be able to claim a terminal loss.
Recapture is the CCA you took in the past that the sale price shows was not needed, up to the capital cost. It is business-style income. Unlike a capital gain, it is included in full, not at one-half. The capital gain on the building is the amount by which the sale proceeds for the building exceed its original capital cost. You model the building and the land separately, because only the building was ever depreciated.
Worked example 4: gain plus recapture on a rental
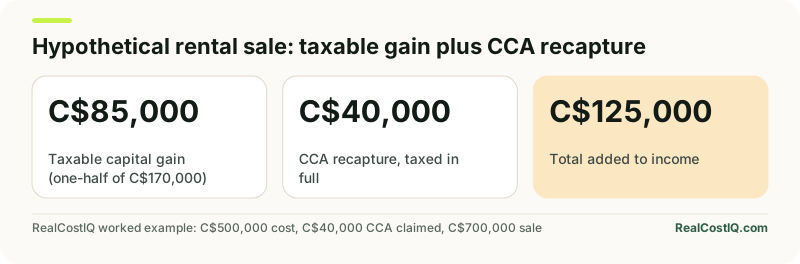
Hypothetical: a rental was bought for C$500,000, split C$350,000 building and C$150,000 land. Over the years C$40,000 of CCA was claimed in total, leaving UCC of C$310,000. It sells for C$700,000: C$420,000 allocated to the building and C$280,000 to land. Selling costs are C$30,000. They are allocated in proportion to proceeds (60% to the building, C$18,000, and 40% to land, C$12,000).
| Item | Building | Land |
|---|---|---|
| Proceeds | C$420,000 | C$280,000 |
| Original cost | C$350,000 | C$150,000 |
| Selling costs (60% / 40%) | C$18,000 | C$12,000 |
| Capital gain (proceeds - cost - selling costs) | C$52,000 | C$118,000 |
| Recapture (lesser of proceeds and original cost, less UCC: 350,000 - 310,000) | C$40,000 | none (land is not depreciable) |
Total capital gain C$170,000, so the taxable capital gain is C$85,000. Recapture of C$40,000 is added to income in full. Total income inclusion is C$125,000, before any rental-year income. The allocation of proceeds between building and land is a judgement an accountant or appraiser should support.
The model here is deliberately simple. Real files add a half-year rule in the first CCA year, additions to the class, and multiple buildings. The rental property CCA calculator runs Class 1 at 4% declining balance. Declining balance means the rate applies to what is left each year. The rental property ROI calculator helps you see the tax on exit as part of the investment's total return, not as a separate surprise. Whether to claim CCA at all is a question for an accountant, because recapture can claw the deduction back on sale.
The residential property flipping rule
Since 2023, a gain on a flipped property is not a capital gain at all. Under s. 12(12) to 12(14) of the Income Tax Act, if you sell a Canadian housing unit (or a right to acquire one) that you held for less than 365 consecutive days, you are deemed to be carrying on a business. The property is then treated as inventory rather than capital property. The gain is business income. It is fully taxable and not eligible for the one-half inclusion rate. Any loss from the flip is deemed to be nil, so it cannot be set against other income.
CRA lists life-event exceptions to the 365-day test. Read the property-specific ones in full before relying on them. They include the death of the taxpayer or a related person, the birth of a child, and a household change such as caring for an elderly parent. They also include the breakdown of a marriage or partnership (with 90 days or more of separation), a threat to personal safety, and serious illness or disability. The list goes on with a work relocation that moves you at least 40 kilometres closer to the new job, involuntary termination of employment, insolvency, and destruction or expropriation (a government taking) of the property. If an exception does not apply, the 365-day clock decides the outcome.
Worked example 5: a 300-day flip
Hypothetical: a Canadian home is bought for C$600,000 and sold 300 days later for C$690,000, with C$40,000 of total acquisition and selling costs. The profit is C$690,000 - C$600,000 - C$40,000 = C$50,000.
- As a capital gain it would have been taxed on one-half, C$25,000.
- As a flipped property the whole C$50,000 is business income. That is C$25,000 more on the tax return, before tax is applied.
- The principal residence exemption does not rescue the gain unless one of the listed life events applies, because the gain is not a capital gain.
A related point for buyers of pre-construction property: the rule also covers a right to acquire a housing unit. So assigning a purchase agreement before closing, which means passing your place in the contract to someone else, can fall inside the 365 days. The assignment rule itself is a matter for a real estate lawyer. So is how it interacts with a purchase agreement signed more than a year before closing.
Selling as a non-resident: section 116 withholding
If the seller is not a resident of Canada, Canadian real estate is taxable Canadian property. Section 116 of the Income Tax Act puts the burden of withholding on the buyer. A non-resident must notify CRA of the disposition. The form is T2062, a request for a certificate of compliance. Per s. 116, this is due within 10 days after the disposition. The buyer faces liability of 25% of the amount by which the purchase price exceeds the certificate limit. The rate is 50% for certain properties, including depreciable property such as a rental building. The buyer must send the money to CRA within 30 days after the end of the month of acquisition.
A buyer is protected if they hold a certificate or reasonably believed the seller was a Canadian resident. That is why lawyers ask residency questions at every Canadian closing. Without a certificate, a buyer usually holds back the amount at closing.
| Scenario | Basis | Amount (CAD) |
|---|---|---|
| No certificate; certificate limit is nil | 25% of C$800,000 | C$200,000 holdback exposure for the buyer |
| Certificate obtained with an agreed ACB of C$500,000 | 25% of the gain (C$800,000 - C$500,000 = C$300,000) | C$75,000 paid by the seller to CRA to obtain the certificate |
| Same sale, depreciable property (50% rate applies) | 50% of C$800,000 without a certificate | C$400,000 holdback exposure for the buyer |
The 25% and 50% rates and the 10- and 30-day deadlines are from s. 116. Whether the 25% on a certificate is applied to the gain or the price depends on the type of property; confirm with CRA or an accountant. The amount withheld is a payment toward the seller's tax, not the final bill, and is reconciled when the seller files a Canadian return.
Non-residents also lose some principal residence years. The s. 40(2)(b) formula counts years in which the property was a principal residence while the taxpayer was a resident of Canada. So years lived outside Canada do not add to the exempt fraction. A person who leaves Canada and sells later should treat the plus-one as unavailable unless they were resident in the year of acquisition. They should also ask an accountant about departure-year effects.
How the pieces fit: a quick map
| Your situation | Rule | Tax result | Where you report it |
|---|---|---|---|
| Lived in the home every year you owned it | Principal residence exemption, s. 40(2)(b) | Gain exempt if designated | Schedule 3 and T2091(IND) |
| Lived in it all but one year | Plus-one | Gain still fully exempt | Schedule 3 and T2091(IND) |
| Owned more than one eligible property in a year | One designation per family unit per year, s. 54 | Exemption split across properties | T2091(IND) for each sale |
| Rented it out (no election) | Deemed disposition at fair market value | Gain on the date of change, usually exempt for residence years | Schedule 3 in the year of the change |
| Rental you never lived in | Capital gain, one-half inclusion, s. 38 | Half of the gain taxed at your marginal rate | Schedule 3, line 12700 |
| Rental where you claimed CCA | Recapture, s. 13(1), plus the capital gain | Recapture taxed in full | Rental income schedule and Schedule 3 |
| Held under 365 consecutive days | Flipped property, s. 12(12) | Entire gain is business income | Business income, not Schedule 3 |
| Seller is a non-resident | Section 116 certificate and holdback | 25% or 50% withholding by the buyer | T2062 and the seller's Canadian return |
Row two onward assume the sale is of Canadian real property. Province-specific closing costs, such as land transfer tax, feed into the ACB or the outlays and are not shown here.
Mistakes that turn up on audit
- Not reporting a home sale because it was exempt. CRA's guidance treats the reporting and designation on Schedule 3 and T2091(IND) as required, even when no tax is owed.
- Forgetting the deemed sale on a change in use. A home converted to a rental has a taxable-event date, even if the exemption covers it. Document the date and value, ideally with an appraisal at the time.
- Leaving selling costs and acquisition costs out of the calculation. Legal fees, commissions and land transfer tax reduce the gain. Missing records are the usual cause.
- Treating improvements as repairs, or the reverse. Capital improvements add to ACB. Repairs on a rental are a current-year expense. Mixing them up changes both the rental income and the gain.
- Selling within 365 days without checking the life-event exceptions. The flipping rule removes the capital gains treatment. Answer the question before the sale agreement is signed.
- Double-counting years across two properties. You get one designation per family unit per year. So a cottage year is not available for the house.
- Skipping the recapture on a rental because the gain looked small. Recapture is taxed in full and can be larger than the capital gain itself.
- Non-resident sellers who close without a certificate. The buyer's lawyer will hold back funds. Recovering them takes time after the sale.
What to do before you list
- List every year you owned the property and how it was used each year: residence, rented, vacant, or used for business. Include any time you lived outside Canada.
- Collect the purchase closing statement, the lawyer's reporting letter, renovation invoices and past rental income tax returns showing CCA claimed.
- If you own a second property, decide with an accountant which property gets each year's designation before the first one is sold.
- If the property was ever a rental, work out the UCC, the building and land split and any recapture before you accept an offer, not after.
- Check the 365-day count if you bought recently, and the exception list if you must sell early.
- If you are not a resident of Canada, or will not be when you close, tell your lawyer immediately. Then the s. 116 process can start before the closing date.
- Run the numbers on the capital gains tax calculator with your province. Then take the result and the records to your accountant.
None of this replaces professional advice. The exemption is generous, but it depends on facts and filings. The rental and non-resident rules carry costs that surprise people who focus only on the one-half inclusion rate. A conversation with an accountant before the sale is far cheaper than a reassessment after it.