The stress test is the one rule that most often decides how much house a Canadian household can buy. It is often described wrongly. It is not a second payment, a penalty, or a rate you will pay. It is a qualifying calculation. The lender works out your payment again at a higher test rate. Then it checks that the result still fits inside your debt-service limits. Your real mortgage is then written at the real contract rate. The contract rate is the rate you agree with the lender. This guide shows the rule as it stands on 2026-10-05. It shows the arithmetic behind it and what it does to a maximum mortgage at three incomes. It also says what to do when the number comes out too low. All dollar figures are Canadian dollars (CAD).
The qualifying rate rule, stated plainly: your mortgage qualifying rate is the higher of 5.25% or your contract rate plus 2 percentage points. OSFI's page lists exactly that rule and was last updated 2026-01-29 (read 2026-10-19). CMHC states the same rule for insured mortgages. Short answer on renewals: if you stay with your current lender, there is no new stress test. If you switch lenders at renewal, there is no test for an uninsured straight switch or an insured switch. Details are in the renewal section below.
You can run your own income and debts through the same logic in the mortgage affordability calculator. This page is the explainer. It covers why the rule exists, where each number comes from, and how to read the result.
To see the monthly payment itself on a C$600,000 home at the minimum, 10% and 20% down, read the mortgage payment on a C$600,000 home.
The rule in one paragraph
Under OSFI Guideline B-20, the qualifying rate for an uninsured mortgage at a federally regulated lender is the greater of two numbers. One is the mortgage contract rate plus 2 percentage points. The other is 5.25%. OSFI is the Office of the Superintendent of Financial Institutions, the federal regulator of banks and other financial firms. It calls the two parts a buffer (2%) and a floor (5.25%). It says it reviews the calibration at least annually. The OSFI page listing the current rate was last updated on 2026-01-29. It still states the 2% buffer and 5.25% floor. I could not find, on the pages read for this article, the result of any later review. So treat 5.25% as the figure in force on the date read. Re-check OSFI before relying on it for a live application. An uninsured mortgage is one without default insurance, which we explain below.
The Financial Consumer Agency of Canada (FCAC) says the same thing in plain language. Banks must use the greater of 5.25% or your negotiated rate plus 2%. FCAC adds that credit unions and other lenders that are not federally regulated do not need to use this stress test. They may still ask you to pass one. CMHC applies its own qualifying rate to every mortgage it insures, whichever lender writes it. CMHC is Canada Mortgage and Housing Corporation, the federal housing agency.
Insured versus uninsured mortgages
A mortgage is insured when the down payment is under 20% of the purchase price (or lending value) and the lender requires default insurance. That insurance comes from CMHC or a private mortgage insurer. It protects the lender, not you, if the loan goes bad. A mortgage with 20% or more down is uninsured, though lenders can also insure it for their own purposes. The two paths use the same qualifying-rate formula. Different documents govern them, and the debt-service caps are stated differently.
- Insured (high-ratio): CMHC states that the GDS and TDS ratios must be worked out at the greater of the contract rate plus 2% or 5.25%. The maximums are 39% gross debt service and 44% total debt service of gross household income. The purchase price (or lending value) must be below C$1,500,000 for CMHC homeowner loans. Minimum down payment is 5% on the first C$500,000 and 10% on the portion above.
- Uninsured (conventional): the qualifying rate is the OSFI minimum qualifying rate. OSFI's guideline sets principles rather than one fixed ratio. Each lender sets its own GDS and TDS limits within its risk appetite. FCAC's consumer guidance uses 39% and 44% as the benchmarks borrowers should aim to stay under.
- Not federally regulated: credit unions and some other lenders are not bound by B-20. They may use a lower qualifying rate, but they are not required to. A mortgage insurer will still apply its own rules to an insured file.
CMHC's premium for an insured purchase is a percentage of the loan. It is set by loan-to-value (LTV), which is the loan as a share of the home's value. The premium is 2.80% for 80.01% to 85% LTV, 3.10% for 85.01% to 90%, and 4.00% for 90.01% to 95%. Below 80% LTV, CMHC lists 2.40% (75.01% to 80%), 1.70% (65.01% to 75%) and 0.60% (up to 65%). Ontario, Quebec and Saskatchewan charge provincial sales tax on the premium, which cannot be added to the mortgage. The premium itself is usually added to the loan. That raises the payment you must qualify for. The CMHC insurance calculator works out the premium for a given price and down payment.
| Item | Insured (down payment under 20%) | Uninsured (20% or more down) |
|---|---|---|
| Qualifying rate | Greater of contract + 2% or 5.25% | Greater of contract + 2% or 5.25% (OSFI B-20) |
| Debt-service limits | GDS 39%, TDS 44% (CMHC) | Lender sets its own; 39% and 44% are the usual reference points (FCAC) |
| Price ceiling | Below C$1,500,000 for CMHC homeowner loans | None from the insurer; lender policy applies |
| Maximum amortization | 30 years for first-time buyers or new builds; otherwise 25 | Lender policy; commonly up to 30 for uninsured |
| Default insurance premium | 0.60% to 4.00% of the loan, by LTV (CMHC) | None required |
Sources: CMHC mortgage loan insurance requirements and cost pages, OSFI minimum qualifying rate page, FCAC mortgage preparation page, Department of Finance news release of December 2024, all read 2026-10-05. The maximum-amortization entry for uninsured mortgages is lender policy, not a figure from a government source.
GDS and TDS: what gets counted
Gross debt service (GDS) is your housing costs divided by gross household income. Gross means before tax. FCAC lists mortgage payments, property taxes, heating costs and 50% of condo fees. Total debt service (TDS) adds all other debt payments. These include credit cards, car loans, student loans, lines of credit and support payments. Both are measured against gross income, not take-home pay. Both also use the stress-test payment, not the payment you will actually make.
The formulas are short:
- GDS = (qualifying mortgage payment + property tax + heating + 50% of condo fees) ÷ gross monthly income
- TDS = (the same housing costs + all other monthly debt payments) ÷ gross monthly income
- Pass = GDS at or under the cap and TDS at or under the cap
For many borrowers GDS binds first, because housing is the largest line. TDS becomes the binding limit when other debt is large. A limit binds when it is the one that stops you first. A C$600 monthly car payment on a C$120,000 income moves the binding limit from GDS to TDS in the worked example below.
How the payment is computed: semi-annual compounding
Canadian fixed-rate mortgages are quoted with semi-annual compounding. That means interest compounds, or builds on itself, twice a year. So a quoted annual rate is not divided by 12 to get a monthly rate. The equivalent monthly rate is (1 + r ÷ 2)^(1/6) − 1. Variable-rate loans are commonly compounded monthly, so confirm your lender's method. The examples here use semi-annual compounding, which is the Canadian fixed-rate convention. Dividing the quoted rate by 12 is the wrong method for a Canadian fixed rate. It gives a slightly different payment.
Three monthly rates drive every example on this page:
| Rate type | Annual rate | Monthly rate (semi-annual compounding) | Payment per C$100,000, 25 years | Payment per C$100,000, 30 years |
|---|---|---|---|---|
| Contract rate (illustrative) | 4.49% | (1.02245)^(1/6) − 1 = 0.37071% | C$552.92 | C$503.63 |
| Qualifying rate at that contract rate | 6.49% | (1.03245)^(1/6) − 1 = 0.53366% | C$669.22 | C$625.76 |
| Qualifying rate when the floor binds | 5.25% | (1.02625)^(1/6) − 1 = 0.43279% | C$595.92 | C$548.71 |
Payment = principal × i ÷ (1 − (1 + i)^−n), where i is the monthly rate and n is months (300 for 25 years, 360 for 30 years). The 4.49% contract rate is an assumption chosen for illustration, not a quoted market rate; check current rates with lenders, and the Bank of Canada for the policy-rate backdrop.
Read the table as a ratio. Amortization is the number of years over which a loan is repaid in full. At a 25-year amortization, every C$100,000 borrowed costs C$552.92 a month at the 4.49% contract rate. It costs C$669.22 at the 6.49% qualifying rate. The qualifying payment is 21% higher. That 21% is the entire effect of the stress test in this scenario. Lenders approve the largest loan for which the higher payment still fits the cap.
Worked qualification examples
To isolate the stress test, the examples use one household type. It has a single gross income, C$400 a month for property tax and heating combined, no condo fees and no other debt. The amortization is 25 years, the contract rate is 4.49% (qualifying rate 6.49%) and the GDS cap is 39%. These are illustrative assumptions, not a forecast. Your property tax in particular will differ by municipality. To find the maximum mortgage, take the housing budget left after tax and heat. Then divide it by the payment factor per dollar borrowed.
Example 1: C$120,000 income
- Gross monthly income: C$120,000 ÷ 12 = C$10,000. GDS cap at 39%: C$3,900.
- Less property tax and heat (C$400): C$3,500 available for the mortgage payment.
- Without the stress test (qualified at the 4.49% contract rate): C$3,500 ÷ C$552.92 per C$100,000 = about C$633,006.
- With the stress test (qualified at 6.49%): C$3,500 ÷ C$669.22 per C$100,000 = about C$522,999.
- Difference: about C$110,007, or 17.4% less.
- Actual payment on C$522,999 at the 4.49% contract rate: C$522,999 × 0.0055292 = about C$2,892 a month, well under the C$3,500 used to qualify.
Example 2: C$80,000 and C$160,000 income
The same steps at other incomes produce the table below. The maximum loan grows in step with income, apart from the fixed C$400. So the percentage cut is essentially the same at each level. What changes is the dollar amount.
| Gross income (CAD) | Housing budget after tax and heat | Max at 4.49% contract rate | Max at 6.49% qualifying rate | Reduction | Actual payment on the qualified loan |
|---|---|---|---|---|---|
| C$80,000 | C$2,200 a month | C$397,890 | C$328,742 | C$69,148 (17.4%) | C$1,818 a month |
| C$120,000 | C$3,500 a month | C$633,006 | C$522,999 | C$110,007 (17.4%) | C$2,892 a month |
| C$160,000 | C$4,800 a month | C$868,123 | C$717,255 | C$150,868 (17.4%) | C$3,966 a month |
Computed with semi-annual compounding as shown above. Maximum mortgage means the loan amount before any CMHC premium added to the principal and before the home price, which is the loan plus your down payment. These are illustrative results, not lender approvals.
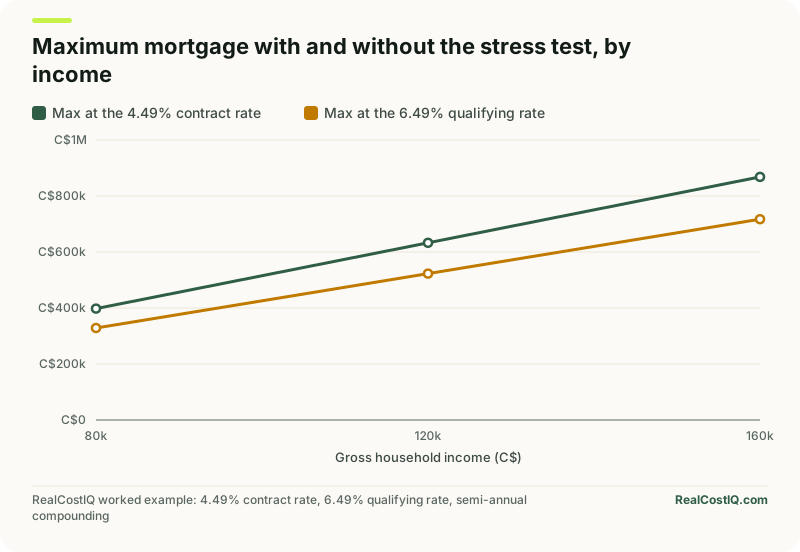
The qualifying cap is about 17% lower than the unstressed one for any buyer with a contract rate near 4.49%. For an insured buyer, the loan limit also depends on the premium added to the amount borrowed. So the home price you can reach is a little lower than loan plus down payment would suggest. The affordability calculator handles that interaction. This explainer keeps the arithmetic visible.
Example 3: when the 5.25% floor binds
Suppose a lender offers a 3.00% contract rate. Contract rate plus 2% is 5.00%, which is below the floor. So the qualifying rate is 5.25%. At a C$120,000 income and the same assumptions, the maximum at the 3.00% contract rate would be about C$739,574 (payment factor C$473.25 per C$100,000). Qualified at 5.25% (payment factor C$595.92), the maximum is about C$587,329. The test removes about C$152,245, or 20.6%. That is a bigger bite than at 4.49%, because the gap between contract and qualifying rate is 2.25 points rather than 2.00. Whenever the contract rate is under 3.25%, a lower contract rate no longer helps you qualify for a larger loan. The qualifying rate stays pinned at 5.25%.
Example 4: when TDS binds
Take the C$120,000 income and add C$600 a month of other debt payments, such as a car loan and a credit card minimum. Total debt service is capped at 44% of C$10,000, or C$4,400. Subtract the C$400 of tax and heat and the C$600 of other debt. That leaves C$3,400 for the mortgage payment. This is less than the C$3,500 left under the 39% GDS test, so TDS binds. The maximum mortgage at the 6.49% qualifying rate falls to about C$508,056 (C$3,400 ÷ C$669.22 per C$100,000). That is roughly C$14,943 below the GDS-only figure. Each C$100 of monthly debt you clear before applying raises your maximum by about C$14,943 at this qualifying rate (C$100 ÷ C$669.22 per C$100,000). This is why paying off a small instalment loan often does more for qualification than a few extra thousand dollars of savings.
The stress test versus what you will actually pay
Readers often ask whether the stress-test payment is what the bank will take from your account. It is not. In the C$120,000 example, you would qualify on a payment of C$3,500 but pay about C$2,892. The difference is a cushion built into the approval. The Bank of Canada's Financial Stability Report 2026 says more than 90% of borrowers who renewed in the previous 12 months did so at rates below their qualifying rates. That is the cushion working as intended.
That same Bank of Canada report looks ahead. Over the next 12 months, the last of the five-year fixed-payment mortgages from the pandemic years will renew. That is about 12% of outstanding mortgages. Those borrowers will see their payments rise by about 15% on average. Another roughly 14% of renewals will on average see no change. These are variable-payment and shorter-term fixed-payment loans taken out after rates rose in 2022 and 2023. The report also notes that some borrowers have softened the increase by extending amortization. Those figures are the reason the renewal rules below matter.
Does the stress test apply at renewal?
No, not in the usual case. If you renew with your current lender, the stress test generally does not apply, because the lender is not approving new credit. Underwriting means checking and approving a loan. If you switch lenders at renewal, the answer depends on whether the mortgage is uninsured or insured, and on whether you ask for more money or a longer amortization. Amortization is the number of years over which the loan is repaid in full.
Uninsured mortgages: OSFI's straight-switch position
OSFI's backgrounder, published 2024-11-21, says that from that date OSFI no longer requires a set minimum qualifying rate for uninsured straight switches at renewal. A straight switch is a move of an existing stand-alone uninsured mortgage from one federally regulated lender to another. The loan amount and the amortization period must not increase. OSFI's current minimum qualifying rate page (updated 2026-01-29, read 2026-10-19) still describes this exception. Lenders must still follow the underwriting principles in Guideline B-20. They must also set qualifying rates in line with their own risk appetite. So a lender may still run its own test. Credit unions and other lenders that are not federally regulated were never bound by this rule.
Insured mortgages: the Department of Finance and CMHC
The Department of Finance's release of December 2024 says the Canadian Mortgage Charter lets insured mortgage holders change lenders at renewal without a new stress test. The release does not give a separate effective date for that change, so ask your lender to confirm that the switch is covered. CMHC's GDS and TDS page (read 2026-10-19) sets the qualifying rate for the insured loans it covers at the higher of contract rate plus 2% or 5.25%. That page does not address renewal switches, and it refers transfer questions to CMHC.
When the stress test still applies at renewal
A refinance replaces your mortgage with a new one, often for more money. If it raises the loan amount or lengthens the amortization, it is not a straight switch, and it is still stress-tested. A move to a different lender that is not a straight switch is also tested. Adding a co-borrower, taking cash out or adding a second mortgage are common triggers. Lenders can also still apply their own checks.
Want to see what your renewal looks like at today's rates, and whether switching or staying is cheaper? Use the mortgage renewal calculator. Weigh any rate saving against the penalty and legal costs of leaving early. This applies if you are not at the end of the term.
Term versus amortization
Canadian mortgages have two clocks, and the stress test uses both. The amortization is the full repayment horizon the payment is calculated on (25 or 30 years). The term is the length of the contract at a fixed rate, with five years the most common. After the term, you renew at whatever rates then prevail. A term ends long before the amortization does. So the test exists to check that you can survive a renewal at a higher rate, not just the first five years at today's.
| Term | Amortization | |
|---|---|---|
| What it is | Length of the contract and the rate you locked | Total years to repay the loan in full |
| Typical length | Commonly 5 years (1 to 10 are available) | 25 years standard; up to 30 for eligible insured buyers |
| Ends with | Renewal, switch or payout | Mortgage-free |
| Effect on stress test | Contract rate is the base for the qualifying rate | Longer amortization lowers the qualifying payment |
| Can change mid-way | Break early and pay a penalty | Re-set at renewal or refinance, subject to rules |
The 5-year term norm and 1 to 10 year range are general market practice, not a government statistic. Confirm term options with your lender.
30-year amortization since December 15, 2024
The Department of Finance's news release of December 2024 confirms that as of December 15, 2024, 30-year amortizations became available on insured mortgages. They are open to all first-time home buyers and all buyers of new builds. In the same release, the price cap for insured mortgages rose from C$1 million to C$1.5 million. The amortization rules apply to insured mortgages. Uninsured amortization is a matter of lender policy.
The stress test checks the payment, so a longer amortization directly lifts the amount you can qualify for. Take the C$120,000 example at the 6.49% qualifying rate. Moving from 25 to 30 years changes the payment factor from C$669.22 to C$625.76 per C$100,000. That raises the qualifying maximum from about C$522,999 to about C$559,316, an increase of about C$36,317 or 6.9%. At C$160,000 income the gain is about C$49,807. The cost is interest. A 30-year schedule pays interest on the balance for five more years. CMHC also lists a 0.20% surcharge for amortizations beyond 25 years on its refinance product. So ask for a purchase-specific quote that shows the surcharge, if any, before you assume the saving.
| Amortization | Payment per C$100,000 at 6.49% | Maximum mortgage | Change versus 25 years |
|---|---|---|---|
| 25 years | C$669.22 | C$522,999 | - |
| 30 years (eligible insured buyers) | C$625.76 | C$559,316 | +C$36,317 (+6.9%) |
Illustrative; assumes C$400 a month for property tax and heat and no other debt. Any insurer surcharge for the longer amortization would raise the loan balance and is not modelled.
If you fail the stress test
Failing means the lender's calculation does not fit your income and debts at the qualifying rate. It is a numbers problem, and the numbers have only five levers. Work through them in order of how much each is worth.
- Clear small debts. Each C$100 a month of instalment debt removed lifts the qualifying maximum by about C$14,943 at a 6.49% qualifying rate and 25 years, as computed above. Pay off the car loan or the line of credit with the highest payment per dollar owed.
- Increase the down payment. A smaller loan needs a smaller qualifying payment. Crossing a CMHC loan-to-value tier also lowers the premium. At 20% down you avoid default insurance altogether, though you then face the uninsured rules.
- Extend the amortization where you are eligible. First-time buyers and buyers of new builds can use 30 years on an insured mortgage. That cuts the qualifying payment by about 6.5% (C$625.76 against C$669.22 per C$100,000).
- Add a co-borrower with income. Both incomes count towards the ratios, and so do both sets of debts. The effect is positive only if the second person's income exceeds their debt payments by enough.
- Look at a different lender type. Credit unions and other provincially regulated lenders are not bound by OSFI B-20, per FCAC. They may apply a different test. Check the terms and any rate premium before accepting. A lower qualifying hurdle sometimes comes with a higher contract rate.

Two options that look attractive deserve scepticism. A smaller home with the same rate is a legitimate fix. A private lender or a short-term rate premium to dodge the test can leave you with a mortgage you can only refinance at a worse rate at renewal. Whichever route you pick, price the renewal before you sign. That is exactly what the stress test makes you do. The mortgage renewal calculator runs that scenario.
Finally, you can improve a marginal result without changing the borrowing. Get a better credit report, documented income and a lower reported housing cost. FCAC recommends checking your credit report for errors before applying. It also suggests working out your GDS and TDS in advance, and using its Mortgage Qualifier Tool to test eligibility.
Why the test exists, and what it is not
OSFI says the buffer builds in a margin of safety. That way, borrowers can cope with a drop in income or a rise in rates. It says the floor reflects risks from broader economic ups and downs. The Bank of Canada's 2026 report supports the practical result. Most renewers have managed higher payments, with more than 90% renewing below their qualifying rate. It also warns that borrowers with weaker income growth have less flexibility. Lower home prices have reduced their equity buffers, which is the part of the home they own. That has made refinancing harder.
The test is not a prediction that your rate will rise 2 points. It is not an evaluation of your lifestyle, or a ceiling on what you may spend. It does not set the contract rate, the term or the amortization. It is a screen applied once, at the moment of approval. It is built into the maximum a lender will commit.
Using this to plan a purchase
Work backwards from the maximum. Take your gross income and subtract the housing and other debt costs. Divide by the qualifying payment factor, then add your down payment. Treat the result as a ceiling and aim below it. The purchase also carries closing costs. CMHC's page for buyers says to budget 1.5% to 4% of the purchase price for these costs, such as legal fees and land transfer tax (page read 2026-10-18). Treat that as a national rule of thumb only. Land transfer tax and first-time buyer rebates differ by province, and some cities add their own tax. For your own figure, use the closing costs calculator and the land transfer tax calculator. The mortgage affordability calculator lets you enter your own income, debts, down payment and rate. It also shows the qualifying rate it used, so you can see the test applied to your numbers. The CMHC premium and renewal calculators above fill in the remaining pieces. To see the income this test asks for in each province, read what income you need to buy a home in each province.
If you plan to move in the next few years, run the test again at a higher assumed rate at your expected renewal. A mortgage you qualified for at 6.49% is one you could still carry by design, if your five-year term renewed at that rate. A mortgage you stretched to the limit and then renewed at a higher payment is where the Bank of Canada sees the stress.