The condo corporation's insurance policy is one of the least understood documents a Canadian unit owner is bound by. It decides who pays for a burst pipe, a flooded unit below yours or a kitchen fire. It does this through a number most owners never see: the deductible. The deductible is the part of a loss the insurer does not pay. When a corporation claims on its policy, the insurer pays the loss above the deductible. The corporation absorbs the rest. In most buildings the corporation recovers that amount from all owners as a common expense, which is a cost shared through the monthly fees. But sometimes the loss starts inside one owner's unit. Then the law of the province often lets the corporation send the whole deductible to that owner instead. That amount can run to tens of thousands of dollars.
This explainer sets out the Ontario, BC and Quebec rules side by side, then covers Alberta in its own section. They are Ontario's Condominium Act, 1998, British Columbia's Strata Property Act, and the co-ownership rules of the Civil Code of Québec. It reads each rule from the province's own legislation site on 2026-10-06. It explains what the corporation's policy covers and leaves out. Then it matches each gap to the unit-owner coverage that answers it. It is information, not legal or insurance advice. Corporations can have by-laws (their own written rules) that go beyond the statute, and your own declaration and by-laws control. The declaration is the document that creates the condominium. To price an owner's own policy, start with the home insurance estimator, which treats condo as one of its home types.
Two policies, one building
Every condo or strata home in Canada sits under two separate insurance contracts. The Insurance Bureau of Canada (IBC) puts it plainly: two policies provide the coverage. The corporation's policy does not cover your personal contents. It does not cover improvements to your unit. It does not cover your liability. (Liability is your legal duty to pay for harm you cause others.) What does it cover? Typically the buildings shown on the plan. It also covers common property such as hallways, roof, pools and garages. It covers fixtures built or installed as part of the original or standard construction. It covers the corporation's own assets. And it covers the corporation's liability to others for property damage and bodily injury.
Your own policy is what IBC calls a unit owner's policy. It typically covers personal property. It covers additional living expenses if you must move out after an insured loss. It covers your personal liability. It covers upgrades and improvements made by you and previous owners, up to a stated limit. It also typically includes "contingency" coverage. This applies if the corporation's insurance is insufficient. And it includes "loss assessment" coverage. IBC describes loss assessment as paying your share of a major loss on common property that exceeds the corporation's policy limit. The loss can be to property or from liability. It pays up to a stated limit. Sometimes the coverage has its own deductible. Most people have never heard of that last coverage. It is also the one that interacts with the deductible chargeback.
| Layer | Corporation's policy | Your unit-owner policy |
|---|---|---|
| Building, common property, standard unit | Yes: required by statute in Ontario, BC and Quebec | No, except the gaps below |
| Improvements and upgrades (flooring, custom kitchen) | No: carved out in Ontario (s. 99(4)) and Quebec (art. 1073); BC covers only original-construction fixtures | Yes: improvements or betterments coverage, up to a stated limit |
| Personal contents | No | Yes |
| Your liability to others | No (the corporation insures its own liability) | Yes: personal liability coverage; mandatory in Quebec |
| Living elsewhere after an insured loss | No | Yes: additional living expenses |
| Corporation's deductible charged to you | Not applicable: it is the charge | Maybe: depends on the loss assessment wording and its sub-limit |
| Special levy when the loss exceeds the policy limit | Not applicable | Maybe: loss assessment coverage, up to a stated limit |
Sources: IBC, Types of home coverage; Condominium Act, 1998 (Ontario) s. 99; Strata Property Act (BC) ss. 149 and 161; Civil Code of Québec arts. 1064.1 and 1073, all read 2026-10-06. The last two rows are the open ones: whether a given policy answers them is a question of wording, which this post cannot see.
Ontario: the Condominium Act, 1998
What the corporation must insure
Section 99(1) of the Condominium Act, 1998 requires the corporation to obtain and maintain insurance. It does so on its own behalf and for the owners. The insurance is for damage to the units and common elements. The damage must come from major perils. It can also come from any other perils the declaration or by-laws specify. (Common elements are the parts of the property that owners share. A peril is a cause of loss.) Section 99(2) defines major perils. They are fire, lightning, smoke, windstorm, hail, explosion, water escape, strikes, riots or civil commotion, impact by aircraft or vehicles, and vandalism or malicious acts. Water escape is in that list. It is the peril behind most large claims discussed below. Section 99(3) covers faulty or improper material, workmanship or design. An exclusion is ineffective for that damage if the policy would otherwise insure it. Section 99(7) says the insurance must cover replacement cost, subject to a reasonable deductible.
The corporation does not insure everything inside your unit. Section 99(4) says the duty to insure does not include improvements made to a unit. Section 99(5) says a standard unit decides what counts as an improvement. The standard unit is for the class of unit. Under s. 99(6), the standard unit is the one described in a by-law the board has made under clause 56(1)(h). If there is no such by-law, it is the one described in the schedule to the declaration. The Condominium Authority of Ontario (CAO) explains the result. The standard unit definition says which part of your unit the corporation must repair and insure. Generally that includes walls, doors and plumbing. Appliances and flooring tend to be non-standard elements. Owners must insure and repair those themselves. The CAO warns about a missing standard unit definition. In that case a corporation may be liable for additional damages and face higher premiums.
The chargeback: section 105
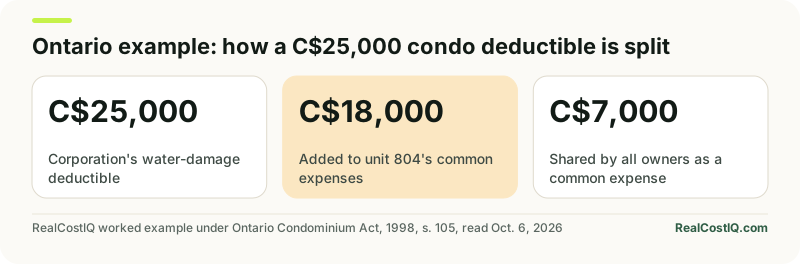
Section 105 is the deductible section. It has four parts. Subsection (1) is the default. The corporation's policy may have a deductible clause that limits what the insurer pays. The part of the loss the insurer does not pay is a common expense. So every owner bears it through monthly fees, in proportion to their share. Subsection (2) is the chargeback. It applies when damage to an owner's unit is caused through an act or omission. The cause can be the owner, a lessee of the owner, or a person living in the unit with the owner's permission or knowledge. (A lessee is a tenant.) In that case, "the lesser of the cost of repairing the damage and the deductible limit" is added to the common expenses payable for that unit. Subsection (3) lets the corporation pass a by-law to extend the circumstances in subsection (2). The damage must not have been caused by the corporation or its directors, officers, agents or employees. Subsection (4) says the amount an owner owes under s. 105 or under such a by-law is an insurable interest of the owner. That means a stake the owner can insure. It is the statutory hook for an owner's own policy to cover it.
Three details matter. First, the trigger in s. 105(2) is an act or omission that causes damage. An omission is a failure to act. The text does not use the word negligence. It covers tenants and occupants as well as the owner. Second, the amount is capped twice. It cannot exceed the repair cost of the damage, and it cannot exceed the deductible limit. Third, as written, subsection (2) is about damage to the owner's own unit. The CAO explains that corporations commonly have by-laws that extend the circumstances in which owners pay the corporation's deductible. Its usual example is an owner who causes damage to other units and the common elements through negligence, such as a major flood affecting many units. That extension is exactly what s. 105(3) authorizes. It is why you must read your own by-laws, not only the Act.
Section 105.1 adds a duty to disclose. The board must give owners a notice, subject to the regulations. The notice carries information about the corporation's insurance under ss. 39, 99, 102 and 105. Section 106 deals with conflicts. Suppose an insurance policy term or the Insurance Act conflicts with the Condominium Act. Then the Condominium Act prevails.
British Columbia: the Strata Property Act
Part 9 of the Strata Property Act sets the insurance duties. It was current to 2026-09-22 on BC Laws when read. Section 149 requires the strata corporation to obtain and maintain property insurance. The insurance must cover common property, common assets and buildings shown on the strata plan. It must cover fixtures built or installed on a strata lot if the owner developer installed them as part of the original construction. (A strata lot is the unit you own.) It must be on a full replacement value basis, except in prescribed circumstances. It must insure against the major perils set out in the regulations. It must also insure against any other perils the bylaws specify. Section 150 requires liability insurance. Section 154 has several duties. The corporation must review its insurance each year. It must report on it at each annual general meeting. It must also tell owners and tenants as soon as feasible of any material change. That includes any increase in an insurance deductible. Section 155 makes the owners, tenants and normal occupants named insureds on the corporation's policy.
The deductible: section 158
Section 158(1) makes the payment of an insurance deductible a common expense. Owners pay it through strata fees. Section 158(2) says this does not limit the corporation's capacity to sue an owner. The corporation may sue to recover the deductible portion of a claim "if the owner is responsible for the loss or damage that gave rise to the claim." Section 158(3) removes a procedural hurdle. Despite any other section, no owner vote is needed for a special levy to cover the deductible. No vote is needed to spend from the contingency reserve fund either. This applies to a deductible the corporation must pay to repair or replace damaged property. The exception is where the corporation has decided not to repair under s. 159. A special levy is an extra charge on owners. The contingency reserve fund is the corporation's savings for big repairs.
Responsibility is the operative word, and the BC government is explicit about how low the bar is. Its owner-and-tenant insurance page states that a strata owner can be deemed responsible, and required to pay the corporation's insurance deductible, even if not at fault or negligent. It gives the example of a dishwasher water hose that prematurely breaks and overflows. The BC Real Estate Association (BCREA) published a 2019 Legally Speaking column by lawyer Mike Mangan. It reports two cases that show both ends of the range. In Strata Plan VR360 v. Jauhar, 2016 BCPC 238, a plugged toilet caused water damage of about C$50,000. The corporation charged back its C$10,000 deductible. The court confirmed the owner's liability, and no negligence was needed. In Strata Plan LMS 2446 v. Morrison, 2011 BCPC 519, the bylaw required an act, omission, negligence or carelessness. So the higher standard applied. The court found negligence and ordered the owner to pay a C$25,000 deductible on C$42,538 of damage. A corporation can therefore raise the standard by bylaw. But the default in the Act is responsibility, not fault.
Two points distinguish BC from Ontario in the text read. First, s. 158(2) lets the corporation recover "the deductible portion" of the claim. Unlike Ontario's s. 105(2), the wording read contains no lesser-of rule tying the charge to the repair cost. The 2019 BCREA column notes that the British Columbia Law Institute's strata insurance committee had recommended such a rule. It also recommended a standard bylaw requiring owners to carry insurance for the deductible. The current Act as read on BC Laws contains neither. The Strata Property Regulation consolidation (B.C. Reg. 43/2000, current to 2026-09-29) has no provision that uses the word deductible. Second, the sums at stake are larger. The BC government's owner insurance page says strata corporation deductibles can range from C$100,000 to C$750,000 or higher. It says owner insurance can cover some or all of the cost of the strata deductible.
Quebec: the Civil Code and the syndicate
In a Quebec divided co-ownership, the syndicate of co-owners buys the building's insurance. (The syndicate is the legal body that all co-owners form.) Article 1073 of the Civil Code of Québec, read on LégisQuébec on 2026-10-06, sets the rules. The syndicate has an insurable interest in the whole immovable, including the private portions. (An immovable is the building and land.) It must take out insurance against ordinary risks. That insurance must allow for a reasonable deductible. It must cover the whole immovable. One exception exists. Improvements made by a co-owner to their portion are left out. They are left out only where they can be identified against the description of that portion. The insured amount must pay for rebuilding to the standards, usage and good practice of the time. A member of a professional order named by regulation must value it. This must happen at least every five years. The syndicate must also carry liability insurance. It covers the syndicate itself, its directors and manager, and the officers of the general meeting. The government may set by regulation when a deductible is unreasonable. By operation of law, the syndicate's insurance contract covers at least the risks the regulation lists. The one way out is if the policy expressly excludes them.
The 2018 reform was introduced by Bill 141. It was phased in between 2018 and 2022. Each part came into force on a different date. This applies to the appraiser requirement of the Ordre des évaluateurs agréés du Québec, the liability-insurance minimums and the self-insurance fund. The Organisme d'autoréglementation du courtage immobilier du Québec (OACIQ) sets out the dates. The reform changed three things for owners. It made each co-owner buy liability insurance. It required the syndicate to build a self-insurance fund for the deductible. And it required a description of private portions, so that improvements can be identified. The regulation (CCQ, r. 4.1) sets the minimum liability insurance each co-owner must take out under art. 1064.1. The minimum is C$1,000,000 if the immovable has fewer than 13 fractions used or usable as dwellings or to operate an enterprise. It is C$2,000,000 if it has 13 or more. (A fraction is one co-owner's unit.) The syndicate's policy must cover certain minimum risks. These include theft, fire, lightning, storms, hail, explosions and water leak damage. They include sewer backup. They include overflows from appliances connected to water distribution piping within the building. They also include strikes, riots or civil disturbances, aircraft or vehicle impact, and vandalism or malicious acts.
Who pays the deductible
Article 1074.2 is the Quebec equivalent of Ontario's s. 105 and BC's s. 158. It uses a different test from BC's. Take the sums the syndicate pays for deductibles and to repair injury to property in which it has an insurable interest. The syndicate may not recover them from the co-owners, with two exceptions. One is their contribution to the common expenses. The other is damages from a co-owner bound to make reparation. To make reparation means to make good the harm. A co-owner may be bound for an injury caused by that co-owner's own fault. In the cases the Code provides, a co-owner may also be bound for an injury caused by the act, omission or fault of another person. The same goes for an injury caused by the act of things in the co-owner's custody. Any stipulation inconsistent with that rule is deemed unwritten. So a declaration of co-ownership cannot extend the chargeback the way an Ontario by-law can. Article 1074.3 makes the syndicate's insurance primary where the syndicate and a co-owner have insured the same risk on the same property. Article 1075.1 limits what an insurer may do after paying a claim. The insurer may not subrogate against the syndicate, a co-owner, a member of a co-owner's household, or the persons whose liability the syndicate must insure. The exceptions are bodily or moral injury and an intentional or gross fault. (Subrogation is when an insurer that has paid a claim steps into your shoes to sue the person who caused the loss.)
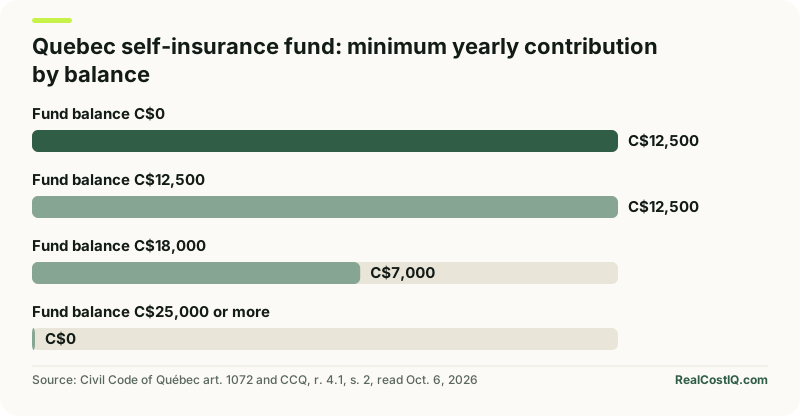
The co-owner's own liability insurance is the practical answer to a claim of this kind. Suppose you are bound to make reparation for a leak, whether through your fault or in one of the other cases the Code provides. Then the syndicate recovers its deductible from you. Your art. 1064.1 liability policy, with its C$1,000,000 or C$2,000,000 minimum, is what responds. Where no co-owner is bound to make reparation, the deductible falls on all co-owners through the common expenses. Quebec has built a fund to absorb it. Article 1071.1 requires the syndicate to hold a self-insurance fund. The fund must be liquid, meaning easy to turn into cash, and available on short notice. It is used to pay the deductibles and to make reparation where the contingency fund or an insurance indemnity cannot. Article 1072 includes the fund in the annual common expense contribution. Section 2 of the regulation sets the minimum yearly contribution. If the fund holds half of the highest deductible or less, the contribution equals half of that deductible. If it holds more than half, the contribution is the difference between that deductible and the fund balance. At or above the highest deductible, no contribution is required. The earthquake and flood deductible is not counted. Suppose the minimum contribution would lift the fund above C$100,000. Then the contribution may be lowered, but not below the amount that leaves the fund at C$100,000 or more. So C$100,000 is a floor on the fund's size, not a cap.
| Fund balance | Rule applied (CCQ, r. 4.1, s. 2) | Minimum contribution that year | Per fraction, 40 equal fractions |
|---|---|---|---|
| C$0 | At or below half the deductible: half the deductible | C$12,500 | C$312.50 |
| C$12,500 | At half: still half the deductible | C$12,500 | C$312.50 |
| C$18,000 | Above half: deductible minus balance | C$7,000 | C$175.00 |
| C$25,000 or more | At or above the deductible | None required | C$0 |
Illustration of the regulation's three-case formula using a hypothetical C$25,000 highest deductible and 40 fractions of equal relative value; real contributions are shared by relative value of fractions and a syndicate may set aside more than the minimum. Source: CCQ, r. 4.1 and Civil Code art. 1072, read 2026-10-06 on LégisQuébec.
Alberta: the C$50,000 chargeback
Alberta is the clearest rule of the four provinces in this post, because the regulation sets a dollar cap. We read section 62.4 of the Condominium Property Regulation (AR 168/2000) on the King's Printer site on 2026-10-21. The copy we read is the consolidation current to 2026-02-15, and it shows an amendment by AR 23/2026. Check the live text before you rely on it.
- Who pays. The owner is "absolutely liable" to the corporation, on demand, for up to the corporation's insurance deductible. This applies to damage that originates in or from the owner's unit or an exclusive possession area, such as a balcony assigned to the unit. The wording does not require fault.
- The cap. Despite any bylaw, a corporation must not require an owner to pay more than C$50,000 under this section. A C$100,000 deductible therefore costs the source owner at most C$50,000.
- No claim needed. The corporation does not have to file an insurance claim to recover up to the deductible from an owner.
- When you are not liable. You are not liable for damage caused by a construction defect in your unit, by an act or omission of the corporation or its board, officers, employees or agents, or by normal structural deterioration of the common property or other property you did not have to maintain.
- How it is collected. By an action in debt, or by a levy on the unit if the bylaws allow it. The regulation keeps the corporation's and owner's right to sue whoever is responsible for the damage, including for wilful damage.
- Required insurance. A bylaw can require owners to buy insurance for these deductibles (section 60.2).
The Government of Alberta's condominium page, read the same day, adds the process. The board passes a resolution and sends a statement of chargeback. It first sends written notice within 90 days of learning of the issue, and the owner has at least 10 days to respond. The owner can appeal to the Court of King's Bench within 30 days of the notice. The page says the charge is the lesser of the repair cost and the deductible, up to C$50,000, whether or not a claim is made. These changes came into force in February 2026. Because the rule applies to damage that starts in your unit, fault is not the question. Where the water came from is.
Ontario, BC and Quebec side by side
| Question | Ontario (Condominium Act, 1998) | British Columbia (Strata Property Act) | Quebec (Civil Code) |
|---|---|---|---|
| Default: who bears the deductible | Common expense (s. 105(1)) | Common expense via strata fees (s. 158(1)) | Common expenses, with a self-insurance fund (arts. 1071.1, 1072) |
| When can it be recovered from one owner | Owner, lessee or occupant causes damage to the owner's unit by act or omission, added to the unit's common expenses (s. 105(2)); more by by-law (s. 105(3)) | Strata may sue an owner who is responsible for the loss or damage (s. 158(2)); no negligence needed by default; a direct charge to the owner's account depends on a bylaw | Co-owner bound to make reparation: fault, or the act of another person or of a thing in the co-owner's custody in the Code's cases (art. 1074.2) |
| Cap on the charge | Lesser of repair cost and deductible limit (s. 105(2)) | The deductible portion; no lesser-of rule in the text read | Damages for the injury; fault-based |
| Can the corporation change it | Yes, by by-law, within s. 105(3) | Yes, bylaws can raise the standard (Morrison) | No: inconsistent clauses are deemed unwritten |
| Special-levy procedure for the deductible | Common expense | No owner vote needed (s. 158(3)) | Board must consult the general meeting before a special contribution (art. 1072.1) |
| Owner's mandatory insurance | Not required by the Act; corporation may require it | Not required by the Act; strongly advised by the Province | Liability insurance, C$1,000,000 or C$2,000,000 minimum |
| What the corporation's policy leaves to you | Improvements beyond the standard unit (s. 99(4)) | Non-original fixtures, improvements, contents, liability | Identifiable improvements (art. 1073) |
Sources: Condominium Act, 1998, S.O. 1998, c. 19, ss. 99, 105 and 105.1; Strata Property Act, SBC 1998, c. 43, ss. 149 to 162, and the BC government's Strata owner and tenant insurance page (published 2025-07-23); Civil Code of Québec arts. 1064.1, 1071.1, 1072, 1072.1, 1073, 1074.2 and 1075.1 and CCQ, r. 4.1; BCREA Legally Speaking #515 (2019-06-20). All read 2026-10-06.
Which unit-owner coverage answers which gap
Each provincial rule leaves a gap. Each gap maps to a coverage line on your own policy. The list below uses the labels that IBC and the BC government use. Actual endorsement names and limits vary by insurer. (An endorsement is an add-on to a policy.) Show your broker the corporation's insurance summary. Then ask each question below by name.
- Improvements ("betterments") coverage. Answers the carve-out for improvements in Ontario's s. 99(4) and Quebec's art. 1073. It also answers BC's limit to original-construction fixtures in s. 149(1)(d). IBC lists upgrades and improvements by you and previous owners, up to a stated limit. It also lists an optional "owner's increased improvement" coverage. That is for upgrades that may exceed standard limits. In Ontario the standard unit definition decides what is an improvement. So get the definition before you pick a limit.
- Personal liability. Answers the fault-based or responsibility-based claim from a neighbour or the corporation. In Quebec it is compulsory. The minimum is C$1,000,000 for buildings of fewer than 13 fractions, and C$2,000,000 for 13 or more. In BC, s. 161(1)(e) expressly lets an owner insure liability. This covers property damage and bodily injury on the strata lot or the common property.
- Loss assessment. Answers the special levy (a special assessment, in Ontario) when a loss exceeds the corporation's limit, per IBC. It is the line most likely to answer a deductible chargeback. The BC government says owner insurance can cover some or all of the cost of the strata deductible. The CAO advises Ontario owners to explore policies that cover them when the corporation asks them to pay its deductible. Ask whether the loss assessment extension applies to the corporation's deductible. Ask what the sub-limit is. Also ask whether it has its own deductible, which IBC says it may.
- Additional living expenses. Answers the cost of living elsewhere after an insured loss. The BC government and IBC both list it as an owner coverage, because the corporation's policy does not pay it.
- Contents. BC's guidance notes that a condo policy asks for a dollar estimate of contents replacement. A house policy instead uses a percentage of the building's value.
- Water and sewer backup, earthquake. IBC lists sewer backup, overland water and earthquake as optional coverages. The BC government lists sewer backup and earthquake among them. It advises owners to ask about the cost of their earthquake deductible. It also advises them to ask about their share of the corporation's earthquake insurance, if the corporation has bought it.
A caution on the wording. The BC government's page says the corporation's policy does not pay the corporation's deductible. It says owner insurance "can" cover some or all of it. It does not say every policy does. A policy can offer a generous liability limit. It can still exclude a charge that comes from a contract or by-law. It can also set a smaller limit for it. Suppose your corporation has an extended chargeback by-law. An insurance reading of "liability" may not match a by-law reading of "responsibility." So do not just ask whether you are insured for liability. Ask whether the policy pays an amount the corporation charges you under a statute or by-law when no one has sued you.
How much deductible coverage should your unit policy carry?
Insurers do not publish one standard limit, so the answer is to compare your building's deductible with your policy's loss assessment limit. Two insurer pages, read 2026-10-21, show how far apart policies can be. RBC Insurance says its property-damage loss assessment pays up to 250% of your contents coverage. It also says it will not pay more than C$25,000 for the part of an assessment made necessary by the corporation's deductible. TD Insurance says loss assessment protects you if you are assessed part of a loss because of the corporation's deductible, but its page gives no dollar limit and refers you to an advisor.
| Building deductible | Most you can be charged: Ontario or BC | Most you can be charged: Alberta | Left over after a C$25,000 sub-limit (Alberta) |
|---|---|---|---|
| C$10,000 | C$10,000 | C$10,000 | C$0 |
| C$25,000 | C$25,000 | C$25,000 | C$0 |
| C$50,000 | C$50,000 | C$50,000 | C$25,000 |
| C$100,000 | C$100,000 | C$50,000 | C$25,000 |
Ontario: the lesser of the repair cost and the deductible (Condominium Act, 1998, s. 105(2)), or more if a by-law extends it. BC: the strata can sue a responsible owner without proving fault (Strata Property Act). Alberta: capped at C$50,000 (Regulation s. 62.4). The C$25,000 sub-limit is RBC's published wording; other insurers differ. In Ontario and BC the same C$100,000 deductible would leave C$75,000 over a C$25,000 sub-limit.
Read the table as a prompt for questions, not a recommendation. If your building's deductible is above your policy's sub-limit, ask the insurer whether a higher deductible-assessment limit is available and what it costs. In Alberta, ask for a limit of at least C$50,000. Then check that your declaration does not push the charge higher.
Water from the unit above: whose policy pays?
Suppose the unit above yours floods and the water reaches your ceiling, floor and cabinets. Three policies can be involved. The corporation's policy responds to the damage to the standard unit and the common elements. It does so after its deductible. Your own policy answers for your contents, your improvements beyond the standard unit, and where you stay while repairs are made. The source unit's owner faces the chargeback. In Ontario that is the lesser of the repair cost and the deductible when an act or omission caused the damage. In Alberta it is up to the deductible, capped at C$50,000, with no fault test.
The chargeback is owed to the corporation, not to you. If you want to recover your own uninsured loss from the neighbour, that is a separate civil claim, and your insurer may pursue it. Alberta's regulation expressly keeps the right of an owner or a corporation to sue whoever is responsible. Ask the corporation which unit the water came from and keep every invoice. Tell your own insurer early.
What to ask for before you buy a unit
The British Columbia Law Institute's strata committee was quoted in the 2019 BCREA column. It observed that many strata corporations had seen their deductibles rise significantly. This was particularly true for damage caused by water ingress (water getting in). A buyer who judges a building only by its monthly fee ignores the single largest contingent liability attached to the unit. That is a cost that may or may not arrive. The monthly fee is a known cost. The deductible is a conditional one. You can only size it by reading the corporation's insurance. The condo fee affordability calculator sets the fee against your income and debt service. The questions below size what the fee does not.
- Get the policy summary and the deductible schedule. In BC, the government says a summary must be attached to the Form B information certificate. The summary is of the corporation's insurance. In Ontario, s. 105.1 says the board must give owners a notice. It is about the corporation's insurance. In Quebec, a designated professional must appraise the reconstruction value. This is required at least every five years. Ask for the latest appraisal. Ask for the highest deductible too.
- Get the by-laws that touch the deductible. In Ontario, ask for the standard unit by-law (or the declaration schedule) and any s. 105(3) by-law. In BC, search the bylaws for a clause that charges the deductible on an act, omission, negligence or carelessness, as in Morrison. In Quebec, the Code overrides any extension. But ask for the description of private portions that identifies your improvements.
- Ask about claims history. A history of water claims tells you how often the deductible has been triggered. It also tells you whether the corporation's cover has changed. BC corporations must tell owners of an increased deductible as soon as feasible under s. 154.
- Check the reserve behind the deductible. In Quebec the self-insurance fund is a legal requirement, and its balance is visible. Elsewhere, a deductible without a reserve becomes a special levy. Under BC's s. 158(3) the strata can levy for it without an owner vote.
- Show your broker both documents. Then ask the questions in the previous section by name. Get the loss assessment sub-limit and any deductible in writing.
- Re-check each year. The BC government advises owners to review their coverage annually. It also advises them to talk to their broker before renewal if the corporation's coverage changes.
The status certificate is where Ontario buyers see the deductible, claims history and reserve fund in one place. Our guide to reviewing a condo status certificate shows what to check. If you are weighing a condo against a house, the deductible exposure is one of the costs that does not appear in a fee comparison. The condo vs house calculator compares ongoing ownership costs. Add your own estimate of the unit-owner policy to it. Treat a chargeback as a one-time event cost, not a monthly one.
A common misreading, and the limits of this post
The most common misreading is that the corporation's insurance covers the unit, so the unit owner need not insure much. In Ontario, BC and Quebec the corporation's policy is built around the standard unit or the original construction. It is not built around what you have actually installed. It stops at the boundary the law or the declaration draws. A second misreading is that a chargeback requires negligence. In Ontario it requires an act or omission that causes damage. In BC it requires responsibility, which the Province says does not require fault. In Quebec it requires that the co-owner be bound to make reparation, through fault or one of the Code's other liability cases. One example is the act of a thing in the co-owner's custody. A third misreading is that the cap is the same everywhere. It is not. Ontario's text caps the charge at the lesser of repair cost and the deductible. The BC text read has no such cap.
Limits. This post covers four provinces. Alberta is covered in its own section above. Nova Scotia and the other provinces have their own condominium statutes and were not read. It covers condo and strata structures that follow the statutes cited. Vacant land condominiums, common element condominiums and bare land stratas have different insurance requirements, as the CAO and BC government pages note. It does not address earthquake or flood deductibles in detail, tenant coverage, or commercial units. It reflects the Ontario, BC and Quebec statutes as they read on 2026-10-06 and Alberta's regulation as it read on 2026-10-21. Ontario's e-Laws notes that the Act has amendments with future in-force dates. If your building has just had a large claim or a deductible increase, get advice from a lawyer who practises condominium law in your province.