Parents who want a flat or house to reach a child can choose among four instruments. The choice moves three costs that are easy to confuse. The first is the stamp duty and registration fee you pay on the paper. The second is the income tax the recipient may or may not owe. The third is the capital gains tax the recipient pays when they eventually sell. A gift, a will, a release (relinquishment) deed and a partition deed look interchangeable in conversation. In law they do different things, to different owners, at different times. This post compares them. It uses state stamp duty figures read from each state's own schedule, and the central rules that sit over all of them. It is general information, not legal advice. The last section lists the points where an advocate is worth paying for.
The four instruments in plain terms
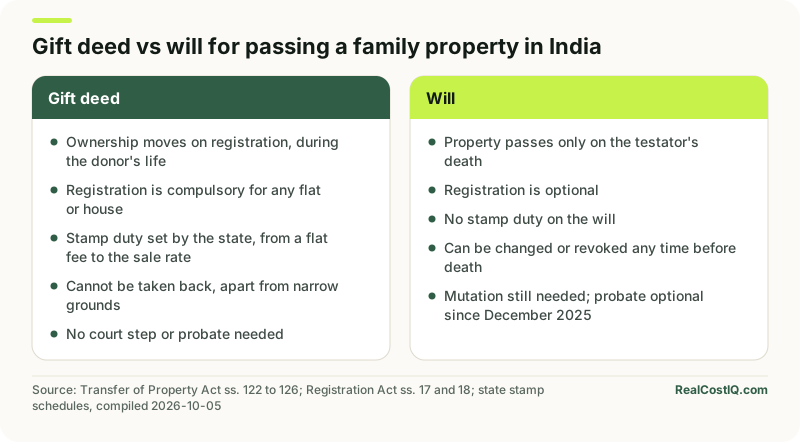
- Gift deed. The owner transfers a property voluntarily, without consideration, to someone who accepts it during the owner's lifetime. (Consideration means payment or something of value in return.) Ownership moves the day the registered deed is executed.
- Will. The owner declares who gets the property after death. Nothing moves while the owner is alive, and the owner can rewrite the will at any time. The beneficiary inherits only what the testator (the person who made the will) actually owned at death.
- Release or relinquishment deed. One co-owner gives up their share in joint property in favour of another co-owner. A typical case is a sibling releasing a share in an inherited house. The two terms are used for the same instrument. The releasee, the person who receives the share, must already hold a share. Otherwise the document is really a gift or a sale.
- Partition deed. Co-owners divide jointly held property into separate portions, each owned by one person. It converts joint ownership into several ownership. Nobody is buying anything.
The practical split is this. A gift and a will move property from an owner to someone who owns nothing in it yet. A release and a partition rearrange property among people who already own it together. A parent with a self-acquired flat and one child is choosing between a gift and a will. Three siblings who inherited a house from a parent who died without a will are choosing between a partition and one or two release deeds. Getting that framing right matters. Registrars price the instruments differently. They treat a mislabelled one as the more expensive thing it actually is.
| Gift deed | Will | Release / relinquishment deed | Partition deed | |
|---|---|---|---|---|
| Who moves property to whom | Owner to a new owner | Owner to beneficiaries, at death | One co-owner to another co-owner | Among co-owners, into separate shares |
| When ownership changes | On registration, during the donor's life | On the testator's death | On registration | On registration (or on a prior oral division later recorded) |
| Registration | Compulsory for immovable property, any value | Optional (Registration Act s.18) | Compulsory where it extinguishes a right in immovable property of ₹100 or more | Compulsory for immovable property |
| Revocable? | No, apart from the narrow grounds in TPA s.126 | Yes, any time before death | No | No |
| Stamp duty | State-specific; from ₹200 flat to full sale rate | No ad valorem stamp duty | State-specific, often a family concession | State-specific, on the separated share or per share |
| Tax on the recipient (s.92; formerly s.56(2)(x)) | Nil if the donor is a relative as defined; taxable above ₹50,000 if not | Nil; inheritance is exempt | Generally none if no consideration is paid | Generally none among co-owners |
| Cost and holding period on later sale | Donor's cost and donor's holding period carry over | Testator's cost and holding period carry over | Carries over for the share received | Carries over for the share received |
| Court step | None | Probate optional since December 2025; mutation still needed | None | None, unless parties contest |
Stamp duty rows are state-specific; see the state table below. The tax rows state the general rule; the exceptions are in the tax sections. Compiled 2026-10-05.
What a valid gift of property needs: Transfer of Property Act sections 122 and 123
Section 122 of the Transfer of Property Act, 1882 defines a gift. It is the transfer of existing movable or immovable property, made voluntarily and without consideration, by one person (the donor) to another (the donee). The donee, or someone for the donee, must accept it. Acceptance must happen while the donor is alive and still capable of giving. Two practical results follow. First, a gift is of existing property. Section 124 makes a gift of future property void. Second, there must be no consideration. Suppose the donee pays the donor, or the deed is a disguised sale. Then it is not a gift, and the stamp duty authority is entitled to treat it as a conveyance.
Section 123 sets the formality for immovable property. A registered instrument must make the transfer. The donor, or someone for the donor, must sign it. At least two witnesses must attest it. Handing over possession does not replace registration for immovable property, though it does for movable gifts. An unregistered gift deed of a flat does not pass title, however long the donee has lived in it. The Registration Act, 1908 backs this up. Section 17 lists the instruments of gift of immovable property as compulsorily registrable, whatever the value.
Section 127 deals with onerous gifts. These are gifts where the property comes with burdens, such as a home loan or an obligation to maintain the donor. A donee who accepts the benefit must accept the burden. Section 128 covers a gift of the donor's entire property, where the donee takes the liabilities as well. Suppose the flat has an outstanding home loan. Then the lender's consent or no-objection letter is a practical need long before the registrar becomes involved, because the property is mortgaged to the bank. Section 129 provides that the chapter does not affect any rule of Muslim law. So a hiba (a Muslim-law gift) follows its own requirements, and an advocate should confirm which regime applies.
Revocability: the biggest difference between a gift and a will
A will can be revoked or rewritten as often as the testator likes until death, provided the testator is of sound mind. A gift cannot give you that flexibility. Under section 126 of the Transfer of Property Act, a gift once accepted is generally irrevocable. The Act allows only two routes out. The first is a clause in the deed itself, agreed by donor and donee, that the gift will be revoked on a specified event that does not depend on the donor's will. The second is any case, other than want or failure of consideration, in which the gift could be rescinded if it were a contract. Coercion, undue influence and fraud are examples. The same section adds that a gift which is to be revocable wholly or in part at the mere will of the donor is void to that extent. So the common instinct does not survive contact with the section. That instinct is that parents can give the flat now and take it back if the child turns out badly.
That is why advocates often draft protective features into a gift deed instead of relying on a change of mind. Examples are a life interest or right of residence for the donor, or a condition on the donee's conduct that is defined by an event. Where the family is uncertain, a will is the other option. A gift made while the donor is elderly and dependent on the donee is a classic ground for later litigation. Courts are alert to undue influence where the donee looked after the donor. None of this is a reason not to gift. It is a reason to decide on a gift only when the donor accepts that the property is gone. Keep independent advice on record too.
Release and partition deeds are as final as gifts. Once registered, the person who gave up the share cannot undo them, unless there was fraud or another ground that voids the deed. Many people miss this. A sibling signs a release for goodwill in a family settlement and later wants to reopen it. That is usually too late.
Can parents take back a gift? The senior-citizens maintenance law
Section 126 is not the only route. A second law can undo a gift made by an older parent. It is the Maintenance and Welfare of Parents and Senior Citizens Act, 2007. Section 23(1) says this. A senior citizen transfers property "by way of gift or otherwise". The transfer is made "subject to the condition" that the receiver will provide basic amenities and basic physical needs. The receiver then refuses or fails to do so. In that case the law treats the transfer as made by fraud, coercion or undue influence. At the parent's option, the Maintenance Tribunal can declare it void. The Supreme Court quoted this text in Sudesh Chhikara v. Ramti Devi, decided on 6 December 2022, and we read the judgment on 2026-10-21.
The same judgment shows how narrow the door is. Both parts must be proved: the condition, and the failure to meet it. The Court said parents often give property "out of love and affection without any expectation in return". So a condition of looking after the parent is not assumed. Whoever claims it must establish it before the Tribunal. In that case the parent had not even pleaded that her release deed carried such a condition. The Supreme Court set aside the Tribunal's order declaring the deed void, and the petition was dismissed. A child who simply neglects a parent does not, by that fact alone, lose the property.
- Write the condition into the deed. If you want this protection, say in the gift deed that the receiver must provide food, shelter, medical care and other basic needs. An advocate can word it. A deed that is silent leaves you to prove the condition from other evidence.
- Know which forum. The petition goes to the Maintenance Tribunal set up under the 2007 Act, not to the civil court. Section 23(3) lets a recognised organisation act for a senior citizen who cannot do it alone.
- This sits beside section 126, not in its place. Section 126 of the Transfer of Property Act still bars a gift that is revocable at the donor's mere will. The 2007 Act gives a separate, condition-based remedy.
- It also helps with maintenance. Section 23(2) lets a senior citizen enforce a right to maintenance out of an estate against a person who receives that estate by gift, if the receiver has notice of the right or the transfer is free.
In plain terms, a gift deed with a written care condition is the closest thing to a safety net in Indian law. It is not a way to take the flat back because the relationship soured. Your advocate should draft the condition before you sign, not after the problem begins.
Stamp duty and registration for a family gift, state by state
Stamp duty is a state subject. Each state defines both the rate and who counts as family. The table below uses the figures behind our deed-type stamp duty calculator. It reads each rate from the state's own Stamp Act schedule or registration department document. We list the date each was checked. On 2026-10-05 we tried to re-read the Maharashtra, Karnataka, Tamil Nadu and other state registration portals, and the India Code and Registration Act PDFs, for this post. Most did not respond from our connection. Two did: the Kerala Department of Registration's rate schedule and the Uttar Pradesh department's model gift deed (Form 106). We re-read both on 2026-10-05, and they match the figures below. We have not re-verified the others at primary source today. Treat the dates as the dates of the last successful reading. Confirm at the sub-registrar's office before you sign.
| State | Stamp duty, family gift | Registration fee | Checked |
|---|---|---|---|
| Maharashtra | ₹200 flat for residential or agricultural property gifted to a husband, wife, son, daughter, grandson, granddaughter or the wife of a deceased son. 3% where the gift is to a brother, sister or lineal ascendant, or for other property types. Beyond those lists, the full conveyance rate. | 1% of market value, capped at ₹30,000 (some practitioners report a lower flat fee; confirm locally) | 2026-08-24 |
| Karnataka | Flat ₹5,000 inside BBMP, BMRDA or a city corporation; ₹3,000 in a town municipal council; ₹1,000 elsewhere, plus 10% cess and a 2% to 3% surcharge on that duty | Not stated: sources split between ₹500 and ₹1,000, so we do not pick one | 2026-08-24 |
| Delhi | No family concession found in the schedule text we read; a gift is charged like a conveyance (6% for a male transferee, 4% for a female, 5% joint). Our calculator applies 6%, because the women's concession is worded for purchases | 1% plus ₹100 for pasting | 2026-08-24 |
| West Bengal | 0.5% of market value for a gift to a family member | 1% of market value (secondary sources; ceiling unestablished) | 2026-08-24 |
| Kerala | ₹2 for every ₹1,000 or part thereof (about 0.2%), minimum ₹1,000, no ceiling | 1% for family, no cap | 2026-09-29 |
| Uttar Pradesh | Flat ₹5,000 under the Government order of 3 August 2023, for gifts to the qualifying relatives named in it | Not read at source: confirm with the sub-registrar | 2026-09-29 |
Maharashtra Stamp Act Schedule I Article 34 (igrmaharashtra.gov.in); Karnataka Stamp Act Article 28(b) (kaveri.karnataka.gov.in); Delhi Article 33 (revenue.delhi.gov.in); West Bengal Article 33 (wbregistration.gov.in, as read in the Stamp Act schedule text); Kerala Articles 31(a)/(b) as substituted by the Kerala Finance Act, 2018 (keralaregistration.gov.in rate schedule); Uttar Pradesh from the registration department's model gift deed, Form 106 (igrsup.gov.in), which cites the order of 3 August 2023 and excludes commercial, industrial and institutional property. The Government order itself could not be retrieved. Tamil Nadu and Telangana are not in this table because we cannot honestly state them; see below. Each state defines family differently and more narrowly than ordinary usage.
Tamil Nadu and Telangana: why there is no figure
Most consumer websites say a family gift in Tamil Nadu costs 1% stamp duty and 1% registration, with caps. A 2026 Godrej Capital explainer we read on 2026-10-05 is one of them. Our reading of the Indian Stamp Act as applied to Tamil Nadu is different. The 2023 amendment (Act 13 of 2024) widened the family definition for partition and release. It did not extend it to the gift article. This suggests a gift is charged at the conveyance rate, with the concession sitting in the settlement deed instead. The two readings differ by six percentage points on the same instrument, and we could not read the primary schedule. So we do not publish a Tamil Nadu gift figure. In practice, intra-family transfers in Tamil Nadu are usually drafted as a settlement deed. Ask the sub-registrar which instrument and which rate apply, and get it in writing. We also leave out Telangana's family gift rate, because published sources conflict.
What the numbers mean on a real flat
- Mumbai flat worth ₹1,50,00,000 (₹1.5 crore) to a daughter. Stamp duty is ₹200. Registration at 1% would be ₹1,50,000 but is capped at ₹30,000. So the paper costs about ₹30,200. The same flat gifted to a mother or a brother falls in the 3% band. That is ₹4,50,000 of duty plus the ₹30,000 fee.
- Kolkata flat worth ₹60,00,000 (₹60 lakh) to a daughter. Stamp duty at 0.5% is ₹30,000 and registration at 1% is ₹60,000. That makes ₹90,000, or 1.5% of value. If the flat were sold instead, the duty and fee would run to 7%, which is ₹4,20,000.
- Bengaluru flat worth ₹2,00,00,000 (₹2 crore), inside BBMP. Flat duty is ₹5,000, cess ₹500 and surcharge ₹100. That is ₹5,600 before any registration fee. If sold, the same flat attracts 5% duty plus cess, surcharge and 2% registration, which is ₹15,20,000.
- Kochi house worth ₹50,00,000 (₹50 lakh) to a daughter. ₹50,00,000 is 5,000 blocks of ₹1,000. So duty is 5,000 × ₹2 = ₹10,000, and the 1% registration fee is ₹50,000. A gift to a nephew or niece is charged as a sale.
- Lucknow home to a child. The duty is ₹5,000 if the donee is a qualifying relative and the property is within the order. Confirm the registration fee locally.
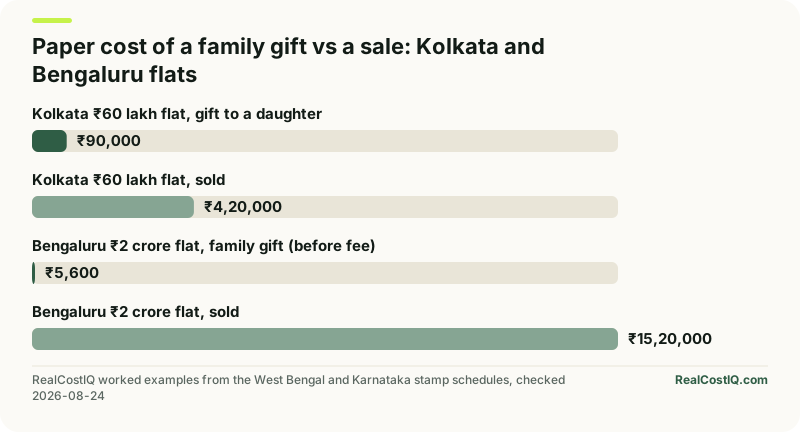
The spread between these is the reason people ask whether a gift is a way of avoiding sale-deed duty. A genuine gift is a legitimate, state-sanctioned concession. A sale dressed as a gift is not. If consideration actually passes, the deed is misdeclared. The registrar can refer it for adjudication, with a deficit, penalty and interest if the duty was underpaid. Another trap is the donee's relationship. Maharashtra's ₹200 does not extend to a gift to a parent or a sibling. A gift to a nephew falls outside both Maharashtra lists. Check the relationship against the state's definition, not against how your family describes itself. For sale-deed rates across states, use our stamp duty calculator. For the registration fee alone, use the property registration cost calculator.
Partition deed stamp duty: charged on the separated share, not the whole
Partition rates are on a different basis from gift rates. So a state with a cheap gift can have an expensive partition, and the reverse. Most states charge on the value of the share or shares that separate out, with the largest remaining share ignored. Maharashtra's Article 46 charges 2% of the market value of the separated share or shares, with no monetary ceiling. West Bengal charges 0.5%. Karnataka's Article 39 charges a fixed ₹1,000 per share for non-agricultural property inside a corporation or council. It charges ₹500 per share elsewhere and ₹250 per share for agricultural land, regardless of value. Kerala charges about 0.15% on the separated share, rounded up to the next ₹10,000, with a ₹1,000 minimum. Our calculator models these on that basis. We leave out its Tamil Nadu and Telangana family partition rows, because the per-share ceilings differ across sources. For Tamil Nadu, ₹10,000, ₹25,000 and ₹40,000 all appear as the stamp duty cap.
A worked Pune example makes the "separated share" idea concrete. A father divides a ₹1,00,00,000 (₹1 crore) property into a ₹60,00,000 share he keeps and two ₹20,00,000 shares for his sons. He is charged 2% on the ₹40,00,000 that separates out. That is ₹80,000. The ₹60 lakh retained share is not charged. The registration fee is 1% with a ₹30,000 ceiling, so it cannot exceed ₹30,000. Now take a ₹5,00,00,000 (₹5 crore) Bengaluru property divided three ways. It costs ₹3,000 at the ₹1,000 per share rate, because the value never enters the calculation. Karnataka's partition duty carries no cess or surcharge on the statutory text, unlike its gift duty. Run your own split in the deed-type stamp duty calculator.
Release or relinquishment deeds
A release deed is the cheaper-looking route when one heir simply drops out. Say a sibling inherited a one-third share of a house with two others. That sibling signs a release in favour of one co-owner, and that co-owner ends up with a larger share. Section 17(1)(b) of the Registration Act makes a document that extinguishes a right in immovable property of ₹100 or more compulsorily registrable. The release must be presented at the sub-registrar's office. The stamp duty depends entirely on the state, and consumer sources contradict each other on it. One 2026 guide we read gives ₹500 in Maharashtra for ancestral property between listed relatives and no payment. Its figures for Karnataka, Tamil Nadu and Telangana differ from the other guides. We do not model release deeds in the calculator and do not give a number for them. Two rules of substance are better established. First, the releasee must already own a share in the property. If not, the registrar will treat the instrument as a gift or sale. Second, suppose the releasor takes money for the share. Then it is not a gratuitous release but a sale of a share, with sale-style duty and a capital gain for the releasor.
A will: no stamp duty, no registration needed, and no immediate transfer
No stamp duty is payable on a will, under the Indian Stamp Act or the state stamp laws. This is according to TaxGuru's stamp duty FAQ, which we read on 2026-10-05. That is the cost advantage that appeals to families. Under section 18 of the Registration Act, 1908, registering a will is optional. An unregistered will is valid if the testator is of sound mind, executes it properly and has two witnesses attest it. Registration, or depositing a sealed will with the Registrar, adds evidentiary weight. The registrar's record proves the signature, and the will becomes harder to challenge as forged. It is cheap relative to the property. It is worth doing for anything that looks likely to be contested.
The costs of a will arrive later and in other forms. Nothing passes during life. After the testator's death, the beneficiary must apply for mutation of the property in the municipal and revenue records. The beneficiary must also transfer the share certificate in the cooperative housing society. Where the property carries a loan, the beneficiary must deal with the lender. A will also only governs what the testator owns. A share in ancestral or coparcenary property may not be fully within the testator's power. The same goes for property over which another person has a legal claim. Personal law may also limit what can be left by will. These are advocate questions, not drafting-template questions.
The trade-off is the reverse of the gift. A will is fully revocable and costs next to nothing in stamp duty. But it leaves a window in which the property is still the testator's. In that window it is exposed to their creditors, to a later will, to a dispute, and to the testator's own needs. A gift removes those risks and the flexibility together. Many families do both. They gift the flat to the child who lives in it and leave the rest by will.
Income tax for the recipient: section 92 of the Income-tax Act, 2025 (formerly section 56(2)(x))
The Income-tax Act, 2025 came into force on 1 April 2026 and now governs the rule. Section 92(2)(m)(ii)(A) taxes a person who receives immovable property without consideration, if its stamp duty value is more than ₹50,000. The taxable amount is the stamp duty value. Section 92(3) then lists what is left out. These include property received from any relative, on the occasion of marriage, under a will or by way of inheritance, and in contemplation of the donor's death. This rule was section 56(2)(x) of the Income-tax Act, 1961. A gift received before 1 April 2026 falls under the old numbering, so check the date of your deed. The substance is the same. We read the Act's text in the Gazette copy on 2026-10-21.
Section 92(5)(g) defines relative for an individual. It covers the spouse, a brother or sister, the brother or sister of the spouse, and the brother or sister of either parent. It also covers any lineal ascendant or descendant of the individual or of the spouse. Finally, it covers the spouse of any person in those groups. So a gift to a son's wife is a gift to a relative, because she is the spouse of a lineal descendant. Cousins and friends are not on the list. A gift of a house from an uncle is tax-free. A gift from a cousin is taxable at the stamp duty value if that is above ₹50,000. This list is different from the stamp duty list. A person can be a relative for income tax and still sit outside the state's family concession. The Maharashtra nephew case is an example. There is no income tax on receipt, but conveyance-rate duty applies on the deed.
Two more tax points matter for family gifts. First, take a gift of property from one spouse to the other. Income that the property later earns, such as rent, is added to the donor's income. Section 99(1)(a)(ii) of the 2025 Act (formerly section 64) says so, and it applies even though the gift itself is tax-free. Second, a gift is not a taxable transfer for the donor. Section 70(1)(b) of the 2025 Act (formerly section 47(iii)) takes a gift or will by an individual or HUF outside capital gains. A gift by a company or a firm gets no such cover. For a family transfer by an individual, the donor has no capital gain when gifting.
Capital gains on a later sale: you inherit the previous owner's cost
Receiving a gifted or willed property is not a taxable event. But it does not reset the clock or the cost. Section 73(1) of the Income-tax Act, 2025 (formerly section 49(1)) sets the cost. Serial number 1 of its Table covers a capital asset that became yours under a gift or will, or by succession, inheritance or devolution. The cost of acquisition is the cost for which the previous owner acquired it. It is increased by any improvement the previous owner or you paid for. Section 73(2) explains who the previous owner is. It is the last previous owner who got the asset by some other mode, such as a purchase. Say your father bought the flat in 2004 for ₹18,00,000 and gifted it to you. Your cost is ₹18,00,000 plus improvements. It is not the market value on the day you received it. A buyer who purchases directly would have a higher cost base. You do not. So a gift of a long-held appreciated property puts the tax on you at the time of sale.
The holding period behaves the same way. Section 2(101)(a) of the 2025 Act calls a capital asset short-term if you held it for not more than 24 months before the transfer. Immovable property is long-term after that. Section 2(101)(c)(B)(I) adds the period the previous owner held the asset, where it came to you under section 73(1). This rule was the Explanation to section 2(42A) of the 1961 Act. Say your mother held a property for 15 years and gifted it to you last month. It is already long-term when you sell it. For the current rate and the indexation options on a sale, use the property capital gains tax calculator. Do not work from older articles that predate the 2024 changes.
Partition and release deeds are treated differently depending on the structure. A division of joint property among co-owners is generally not treated as a transfer, if each receives property equal to their share. But suppose one co-owner receives more than their share and pays for it. That excess may be a transfer. Where an HUF (Hindu undivided family) is being partitioned, the rules are separate. These are exactly the cases where a chartered accountant should look at the draft deed before it is signed.
Probate and succession certificates: what changed in December 2025
Until recently, probate of a will was mandatory to establish rights as executor or legatee only in a narrow set of cases. (Probate is a court's confirmation that a will is genuine.) These cases were connected with Mumbai, Chennai and Kolkata, through section 213 of the Indian Succession Act, 1925. Section 370 tied succession certificates to the same rule. Bar and Bench reports that the Repealing and Amending Act, 2025 omitted section 213 and removed the linkage in section 370, with effect from 20 December 2025. Probate is now optional anywhere in India. The Finnovate explainer we read on 2026-10-05 says it is still available and advisable in some cases. These are disputed wills, complex estates, high-value property in major cities, or an estate that crosses borders.
Probate and a succession certificate do different jobs. Probate is a court's confirmation that a will is genuine. It grants the executor authority over the estate. A succession certificate authorises collection of debts and securities such as bank deposits, shares and bonds. Neither transfers immovable property by itself. The executor or heir still applies for mutation in the land or municipal records and for transfer in the housing society. Court fees are ad valorem on the estate under each state's Court Fees Act, so they differ by state. The only example Finnovate gives is Maharashtra. There the fee is 4% on the slice between ₹50,000 and ₹2,00,000 and 7.5% above ₹2,00,000, capped at ₹75,000. We have not read the Maharashtra Court Fees Act. So treat that as a reported figure and check the schedule for your state.
The difference to the gift route is worth stating plainly. A gift deed needs no court and no probate. The family that gifts avoids the delay and court-fee risk of the will route, and a contested will can take years. The family that relies on a will keeps flexibility and avoids stamp duty. But it may need probate if anyone is likely to challenge the will. Suppose the will is uncontested and the beneficiaries are the natural heirs. Many families then proceed with mutation on the strength of the will and the death certificate alone. It depends on what the local revenue office and housing society ask for.
Choosing between them
- One owner, one intended recipient, wants it settled now. Use a gift deed. Budget the state's family-gift stamp duty and fee. Confirm the donee is within the state's definition of family. Accept that it cannot be reversed.
- One owner, wants control until death. Use a will, ideally registered. There is no stamp duty. But expect mutation work, and possible probate if a dispute is likely.
- Several co-owners from an inheritance, who want separate ownership. Use a partition deed. It is priced on the separated share, or per share, depending on the state.
- One co-owner leaving a joint property to another co-owner. Use a release or relinquishment deed, registered, with no consideration paid. If money changes hands, expect it to be treated as a sale.
- The property has a loan. Talk to the lender first. In practice, a gift or release of a mortgaged property needs the lender's consent.
- Long-held property that will eventually be sold. Estimate the capital gain using the previous owner's cost. It will carry over to the recipient under any of these routes.
When to see an advocate or a chartered accountant
Nothing in this post is legal or tax advice. The stamp duty figures are the ones in the state schedules on the dates shown. Get an advocate in these cases. The property is ancestral or part of an HUF. The donor is elderly, ill or dependent on the donee. The donee is not clearly within the state's list of relatives. The property is mortgaged or in a cooperative society with its own transfer rules. The family is not unanimous. The donor or donee is an NRI, whose repatriation and tax position adds separate rules. Or personal law other than Hindu law applies. Get a chartered accountant when the property has a low historical cost and will be sold. Also get one when a partition is unequal, or when any payment is being made between co-owners.
Finally, check the stamp duty at the sub-registrar's office on the day, not from this page or any other. The state revises rates, relationship lists and the valuation used (the ready reckoner or circle rate) by notification. A deed stamped at last year's figure is a deficit that carries penalty and interest. A family cannot choose the valuation basis. So ask for the market value the office will apply before you buy stamp paper.