A condo is insured twice, by two different parties. The gap between the two policies is where owners get hurt. The HOA, short for homeowners association, buys a master policy on the building and common areas. You buy an HO-6, the unit owner's policy, for the rest. Say the HOA's policy covers less than you assumed. Or say you carry less than the master leaves out. Then a covered loss turns into a bill. This post shows how to read where the line falls and what a lender requires on each side of it. It also shows how to size your own coverage from the HOA's documents. It does not quote premiums. The site's home-insurance premium data is for single-family (HO-3) policies and does not describe an HO-6. So no premium figure here is presented as a condo premium. For what the HOA fee itself pays for, see the HOA costs guide.
Three kinds of master policy, and why the label decides everything
The Washington State Office of the Insurance Commissioner (OIC) explains how your unit's structure is covered. It depends on the community's governing documents. It falls into one of three categories. The names vary by state and by insurer. The three structures stay the same.
| Master policy type | Master policy covers | You (HO-6) must cover |
|---|---|---|
| All-in | The exterior and all interior finishes: doors, windows, siding, shower or tub, vanity and cabinets, paint, baseboards and trim, light fixtures, floor coverings. | Your belongings, liability, loss of use, loss assessment, and any improvements you added beyond the original unit (depending on the policy). |
| All-in, excluding improvements or betterments | The unit restored to its original interior and exterior finishes. Owner upgrades are not covered, for example replacing original laminate counters with granite. | Everything above plus the cost of the upgrades you made, such as the kitchen or bath remodel. |
| Bare walls (walls-out) | Damage up to the uncovered sheetrock and subfloor, which includes the roof, maybe the windows, and other common areas. | All interior finishes: cabinets, fixtures, flooring, paint, and everything inside the drywall line that is yours. |
Categories and examples from the Washington State Office of the Insurance Commissioner's condo insurance guide, read 2026-10-06. Some governing documents use other terms, so use your documents' wording, not these labels, to decide.
The same building can sit under any of the three. Two owners in different associations can both pay HOA dues for "insurance" and carry very different amounts of risk. So never guess the type from the fee. Read the declaration, which is the recorded document that creates the condo. Read the bylaws too, or ask for the insurance summary. Do this before you set a dwelling limit.
What the lender requires of the master policy
Fannie Mae is a company that buys mortgages from lenders. When a condo loan is sold to it, the project itself must meet insurance standards. Those standards show what a good master policy looks like. Fannie Mae's master property insurance requirements call for coverage of at least 100% of the estimated replacement cost value of the project improvements. That includes common elements and residential structures. The lender may rely on guaranteed replacement cost coverage or its equivalent. It may rely on extended replacement cost coverage or its equivalent. It may use a replacement cost estimate from the insurer. It may use the project's insurance risk appraisal. Or it may use a statement from the insurer or another expert. The policy should be written on a Special coverage form or equivalent. Building ordinance or law coverage is also required. It pays for loss to the undamaged part of a building, demolition costs, and higher costs of construction. The one exception is where the HOA cannot get it in its insurance market.
HUD's FHA rules for approved condo projects set a similar standard. In Handbook 4000.1 (Update 18, issued 8/12/2026) the HOA's master or blanket hazard policy has a set minimum. It must be in an amount to fully cover the insurable replacement cost of all Units and all insurable Common Elements in the approved project. A policy with a coinsurance clause has three options. It can include an agreed amount endorsement. It can use the agreed value option. Or it can carry an amount of coverage that fully covers that insurable replacement cost.
The master policy deductible is the number that reaches you
A deductible is the part of a loss you pay before insurance pays. The HOA sets the master policy's deductible, but a covered loss can still land on the owners. Fannie Mae's master-policy rules allow two setups. One is a per-occurrence deductible of up to 5% of the master policy's coverage amount. The other is a per-unit deductible of up to $50,000 per unit. A per-unit deductible requires unit owners to keep their own policies. A 5% deductible on a large building is a big dollar amount. When a loss exceeds it, the HOA collects the deductible share from the owners through a special assessment.
| Item | Figure |
|---|---|
| Master policy coverage amount | $30,000,000 |
| Maximum per-occurrence deductible at 5% | $1,500,000 |
| Number of units, equal ownership shares | 60 |
| Deductible share per unit if the full deductible is assessed | $25,000 |
| Same building, per-unit deductible at the $50,000 maximum | Up to $50,000 for each affected unit |
Illustrative arithmetic. The 5% and $50,000 limits are from Fannie Mae Selling Guide B7-3-03 (effective 08/05/2026). The coverage amount, unit count and ownership shares are invented to show the calculation; your declaration sets how a deductible or assessment is divided.
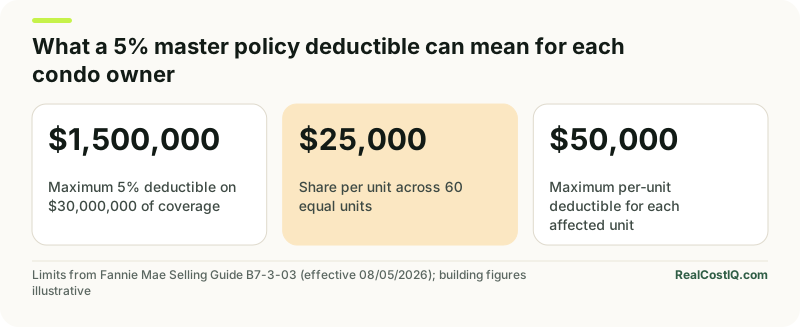
This is why the deductible, not the premium, is the line to read in the HOA's insurance summary. A master policy with a low premium and a high deductible has moved risk from the HOA's budget to your checking account. The OIC guide says unit owners are responsible for the community deductible on their own policies. It also says owners get a certificate of insurance each year confirming limits and deductibles. Use it.
What your HO-6 actually covers
The NAIC (the National Association of Insurance Commissioners) publishes a consumer guide. It describes the condo unit owners form as the policy for owner-occupants of condo units. It insures your personal property and your walls, floors and ceiling against the perils in the broad form. The OIC lists the parts: dwelling coverage for your unit's structure, personal liability, premises medical, additional living expenses, personal property, and loss assessment.
- Dwelling coverage (the building portion of the HO-6). Covers the interior the master does not. In a bare-walls building that means finishes. In an all-in-excluding-improvements building it means betterments. This is the limit you must size.
- Personal property. Your furniture, clothing and electronics. The OIC notes it is often paid at actual cash value, not full replacement value. So a replacement-cost endorsement is worth pricing.
- Loss of use (additional living expenses). Pays for temporary housing if a covered loss makes the unit unlivable.
- Personal liability and premises medical. Covers injuries to others in your unit. The master covers the common areas, not your unit.
- Loss assessment. Helps pay a special assessment the HOA charges members for a loss it suffered. One example is storm damage that exceeds the master policy's limits.
The OIC also lists what typical policies exclude: community property, flood, earth movement, and wear and tear. Flood is handled differently from the rest. Take an attached condo in a Special Flood Hazard Area. Fannie Mae asks the lender to verify that the HOA maintains a Residential Condominium Building Associated Policy (RCBAP) or equivalent private flood coverage. HUD's Update 18 likewise puts the flood requirement on the Condominium Association. It covers the buildings for unit owners and common areas alike. Ask the HOA for its flood policy. See our flood insurance cost calculator for how flood premiums move with zone and elevation.
How to size your dwelling coverage from the association's documents
Sizing takes three steps. You are insuring the gap between what the master restores and what your unit needs to be livable again.
- Get the documents. Request the declaration, the bylaws, and the current certificate of insurance or insurance summary from the HOA. The OIC advises speaking with the president or the property manager. It notes that unit owners get a Certificate of Insurance each year when the community policy renews, confirming the limits and the deductible. Ask for three things: the master policy type, the coverage limit, and the deductible.
- Mark the line. Write down what the documents say the HOA insures, such as interior finishes, fixtures and original cabinetry. Everything on the other side of that line is yours.
- Price your side. Add up the replacement cost of what you must insure. That is finishes and fixtures if the master is bare walls. It is only your upgrades if the master is all-in excluding betterments. Use your remodel receipts and contractor quotes. Walk through the unit with a room list in hand.
| Component | How to price it | Example figure |
|---|---|---|
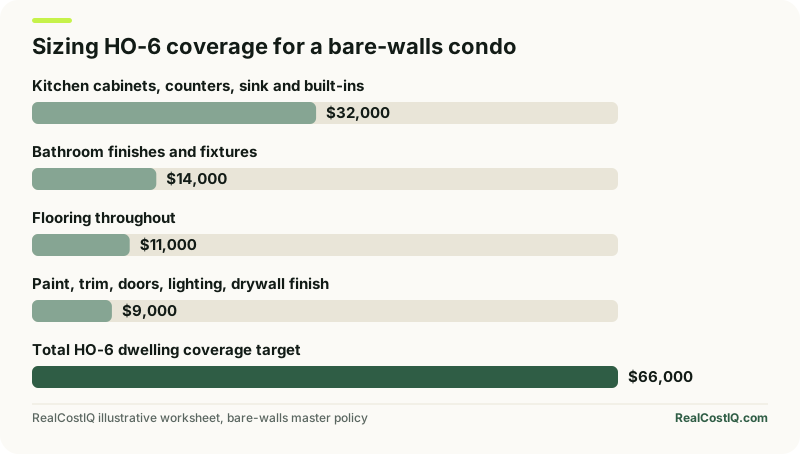
| Kitchen cabinets, counters, sink and appliances built in | Remodel receipts or a contractor quote at current prices | $32,000 |
| Bathroom finishes and fixtures | Quote for tile, vanity, tub or shower, fixtures | $14,000 |
| Flooring throughout | Area times a current installed price per square foot | $11,000 |
| Paint, trim, doors, lighting, interior drywall finish | Quote or per-room allowance | $9,000 |
| Total dwelling (HO-6 interior) coverage target | Sum of the above | $66,000 |
Every figure is an example to show the method; none is a market price. Get quotes at your own address. If the master policy is all-in excluding betterments, only the upgrade portion of each line belongs in the total.
A second way to get the dwelling number: square feet times a rebuild price
The line-by-line method above is the most accurate. A quick check is interior square feet times a finish-and-fixture price per square foot. Say your unit is 900 square feet. Say a contractor tells you the interior finishes in a bare-walls unit run $75 per square foot. Both numbers are assumed for this example. Then 900 x $75 = $67,500. That lands close to the $66,000 worksheet total. If the two methods are far apart, one of them is missing a room or a fixture. Replace the $75 with a bid from a local contractor.
Sizing loss assessment from the master deductible
| Step | Figure |
|---|---|
| Master policy deductible (5% of $30,000,000) | $1,500,000 |
| Your share, 1 of 60 equal units | $25,000 |
| Loss assessment limit to carry at minimum | $25,000 or more |
| Why more | An assessment for a loss above the master limit comes on top of the deductible share |
Illustrative. Your declaration decides how a deductible or an assessment is split among owners, and your policy sets the loss assessment limit. The OIC notes that loss assessment can help pay special assessments for community losses, such as damage above the master policy's limits.
Then add a cushion for the deductible. Say the master carries a $25,000 per-unit deductible. That amount has to come from somewhere. If your HO-6 loss assessment limit is lower than the deductible, you pay the difference. The true cost of homeownership calculator shows where an insurance line sits against dues, taxes and maintenance in a condo budget. It is a good place to test what a higher limit does to the monthly total.
One more question to ask before you buy: does the master policy carry an agreed amount endorsement? HUD's condo standard says any policy with a coinsurance clause must include one of three things. These are an agreed amount endorsement, the agreed value option, or coverage that fully covers the insurable replacement cost. Ask which of those the HOA relies on. Suppose the HOA's limit has not been revised in years. A loss above it becomes a special assessment. Your loss assessment coverage is the only policy line that answers it. Ask when the master policy's replacement-cost estimate was last updated. Ask to see the board minutes on the last insurance renewal. An HOA that raised its deductible sharply at renewal is telling you the risk has moved to the owners.
Timing matters too. A buyer usually has only the contract period to collect these documents. The lender will want the HO-6 binder before closing. A binder is proof that your coverage is in place. Request the insurance summary the day the contract is signed, not the week of closing. Then your quote for the right dwelling limit is not rushed.
The lender's rule for the unit owner's side
A lender does not leave your side to chance. Under Fannie Mae's unit owner insurance requirements, the borrower must get a unit owner policy in two cases. One is when any part of the unit's interior or improvements is not covered by the master policy. The other is when the master includes a per-unit deductible. The policy should be written on a Special coverage form or equivalent. It should cover the same minimum perils as a house policy: fire or lightning, explosion, windstorm including named storms, hail, smoke, aircraft, vehicles, and riot or civil commotion. It must be on a replacement-cost basis.
- Minimum coverage: the greater of two amounts. One is the amount needed to restore the interior parts the master does not cover to their pre-loss condition. The other is the per-unit deductible amount, if there is one.
- Maximum deductible: the greater of 5% of the coverage amount or $2,500. The $2,500 floor means a small policy is not forced to carry a tiny deductible.
- Replacement cost basis: required, as for a house.
- Mortgagee clause: the lender is named as mortgagee on your policy. The servicer's name and address must match. The clause and named-insured rules for one- to four-unit properties are in Selling Guide B7-3-08.
The guide recommends that borrowers work with an insurance professional to find their needs. Coverage must fit the unit's own conditions and the master policy's terms. In practice the lender will ask for a binder or declarations page on the HO-6 before closing. Say your quote shows a dwelling limit well below the interior your documents leave to you. Expect a request to raise it. Our post on how much homeowners insurance a lender requires covers how a house policy is tested against the same lender framework.
Where condo owners get caught
- Assuming "all-in" without reading it. The label on a listing sheet is not the document. Read the declaration.
- Forgetting the remodel. Say the previous owner replaced the kitchen. An all-in-excluding-betterments master policy will not pay for it. Your HO-6 dwelling limit must include it.
- A loss assessment limit lower than the master deductible. The deductible, not the premium, is what reaches you. Compare the two numbers.
- Treating loss assessment as unlimited. It has a limit, and you must choose the limit. Read how your policy defines the assessments it will pay.
- Flood and earth movement. Standard unit owner policies exclude both, as the OIC notes. For flood, check whether the HOA carries the RCBAP or equivalent that lenders look for in a flood zone. Also ask about your own coverage for contents and improvements.
- Contents at actual cash value. The OIC notes personal property is often paid at depreciated value on standard limits. Price the replacement-cost endorsement.
A condo insurance checklist before you close
- Request the declaration, bylaws, and the master policy certificate with its limit and deductible.
- Identify the master policy type in the documents' own words: all-in, all-in excluding betterments, or bare walls.
- List the interior items and improvements the master does not cover and price them at current replacement cost.
- Set your HO-6 dwelling limit to that total, at least, and confirm it satisfies the lender's unit-owner minimum.
- Set loss assessment at or above the master deductible share you could be charged.
- Check the deductible against the lender's maximum: the greater of 5% of coverage or $2,500.
- Confirm the lender is named as mortgagee with the exact servicer name and address, and send the declarations page before closing.
- Re-read the master policy certificate each year when you receive it.