The RealCostIQ Blog
Blog
Long-form explainers that sit beside our calculators: the rules, fees and trade-offs behind the numbers, written market by market and sourced line by line. No lead forms, no sponsored picks.
United States
 MortgagesHow Much of Your Take-Home Pay Should Go to a Mortgage? The 28% Rule Restated for Net IncomeA lender's 28 percent of gross pay is closer to 33 to 36 percent of what lands in your bank account. This post converts the rule to take-home pay at three salaries and shows what each yardstick lets you borrow.14 min read
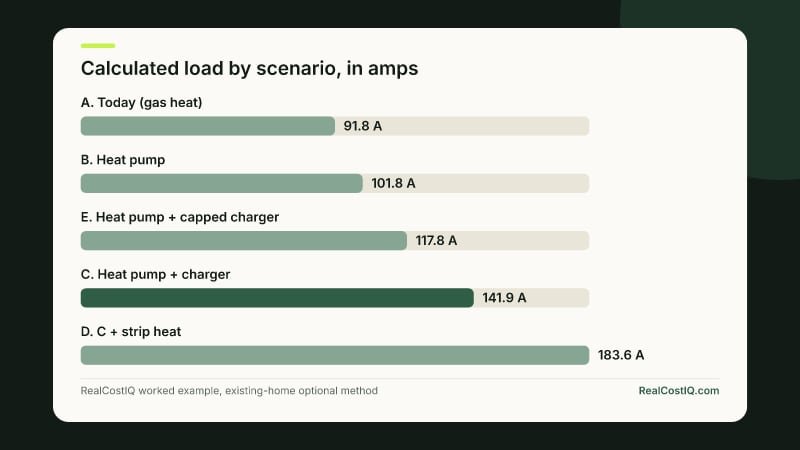 Renovation & RepairDo You Need a 200-Amp Panel for a Heat Pump or EV Charger? Do the Load Math FirstA heat pump and an EV charger do not always mean a 200-amp panel. Here is the five-step load math, a worked example with real numbers, and the cheaper options to try before you pay for an upgrade.15 min read
 MortgagesHOA Dues and Your Mortgage: How $300 a Month Cuts What You Can BorrowLenders count HOA dues as part of your monthly housing cost. This worked example shows how $300 a month shrinks your maximum loan by $44,021, why the debt-to-income cap does not change that, and what special assessments add.12 min read
 Home BuyingBuying a Home With a Private Well: Inspection, Pump Replacement and New-Well CostsWith a private well, nobody tests your water for you. This post lists the two tests to order before closing, the lender rules, and four dollar budgets from a healthy well to a new one.13 min read
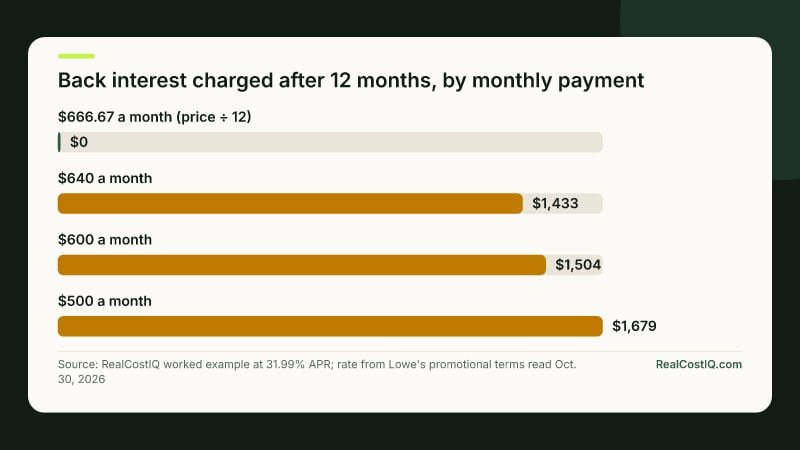 MortgagesDeferred-Interest Financing for Home Improvements: How the "No Interest If Paid in Full" Cliff Works, With NumbersStore-card offers for windows, flooring and appliances often say "no interest if paid in full." Miss the date by a few hundred dollars and the interest is charged back to day one. This post shows the numbers.15 min read
 MortgagesHow to Pay for a $40,000 Renovation: HELOC, Home-Equity Loan, Cash-Out Refi, Personal Loan or Contractor FinancingFive ways to fund a $40,000 renovation, priced with this week's rates. The cheapest is usually a second loan on the house. The one that can cost $197,000 extra is a cash-out refinance when your first mortgage rate is low.13 min read
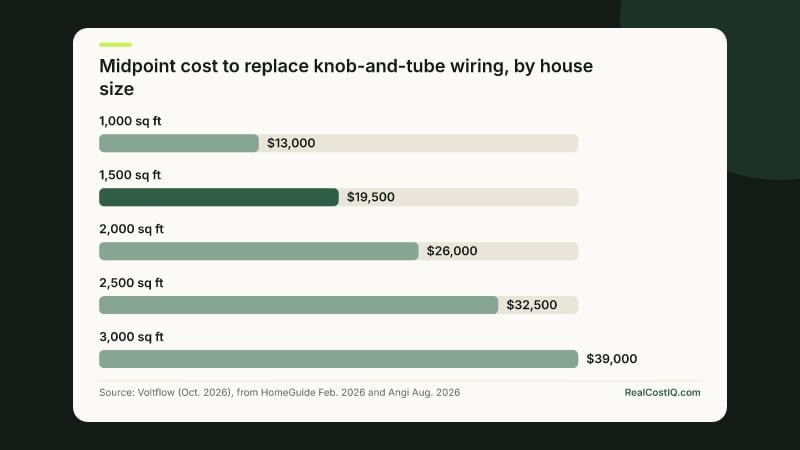 Home BuyingBuying a House With Knob-and-Tube Wiring: Insurance, Rewiring Cost and Who PaysOld knob-and-tube wiring can block your homeowners policy before it blocks your loan. Here is the rewire cost for a 1,500-square-foot house, how insurers react, and the five ways a seller can pay.14 min read
 MortgagesDSCR Loan vs Conventional Investment Mortgage: Rate, Down Payment and Prepayment PenaltyA DSCR loan costs more each month and can charge you to pay it off early. This post puts the extra cost in dollars, year by year, so you can see when the trade is worth it.17 min read
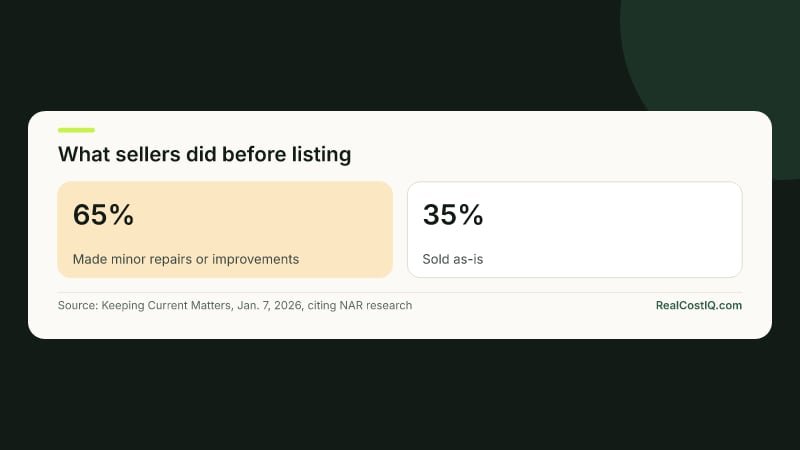 Home BuyingSell As-Is or Fix It First? Which Repairs Pay Back Before ListingA repair pays back only if buyers pay more than it costs, after commission and the months you wait. Here is the formula, three worked cases, and the short list of fixes that usually clear the bar.12 min read
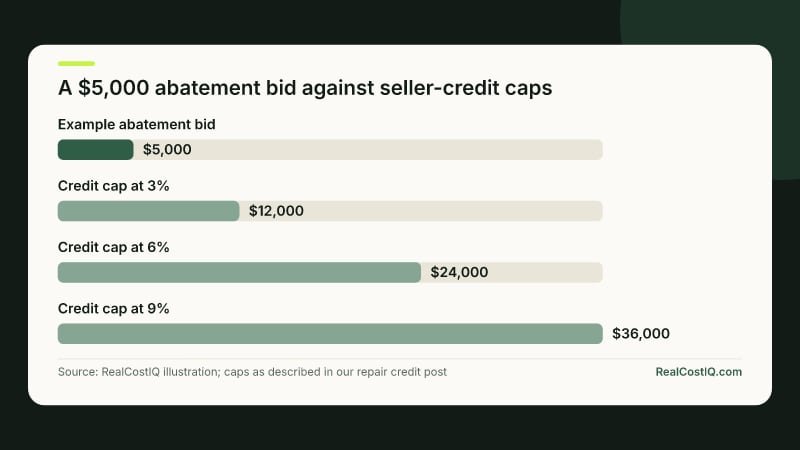 Renovation & RepairAsbestos Found in a House You're Buying: Testing, Removal vs Encapsulation, and Who PaysThe inspector says the tile, ceiling or insulation may contain asbestos. Here is how to decide whether it matters, which fix fits your plans, and how to put the cost on the seller.19 min read
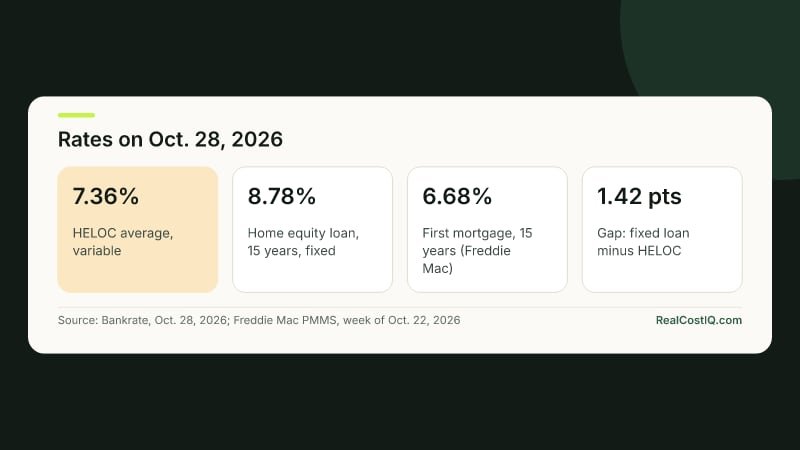 MortgagesHome Equity Loan vs HELOC in 2026: Fixed Payment or Flexible Line, and What Each Really CostsOn a $50,000 borrow, a HELOC at 7.36% saves about $7,400 in interest over 15 years if the rate never moves. This post shows how far the rate has to climb before the fixed loan wins.18 min read
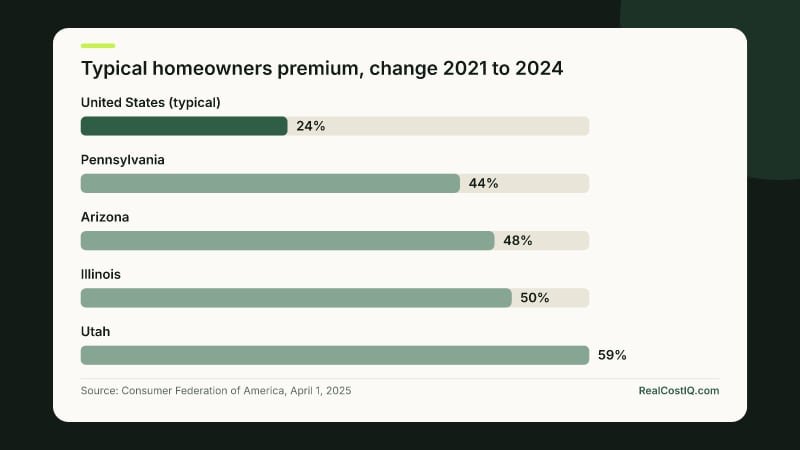 Home InsuranceWhy Did My Homeowners Insurance Go Up? The Six Reasons, and What You Can ChangeSix causes sit behind a homeowners renewal increase. Four are market-wide and you cannot change them. Two sit on your own policy. Here is how to tell which hit you, and the deductible math for the one lever most people have.18 min read
 MortgagesBuying Before You Sell: Bridge Loan vs HELOC vs a Sale Contingency, With Real CostsTo buy a $600,000 home before selling a $500,000 one, you need about $120,000 for 4 months. A HELOC costs about $2,900 in interest, a bridge loan $4,000 to $9,600, and a sale contingency costs no loan fees but can lose you the house.14 min read
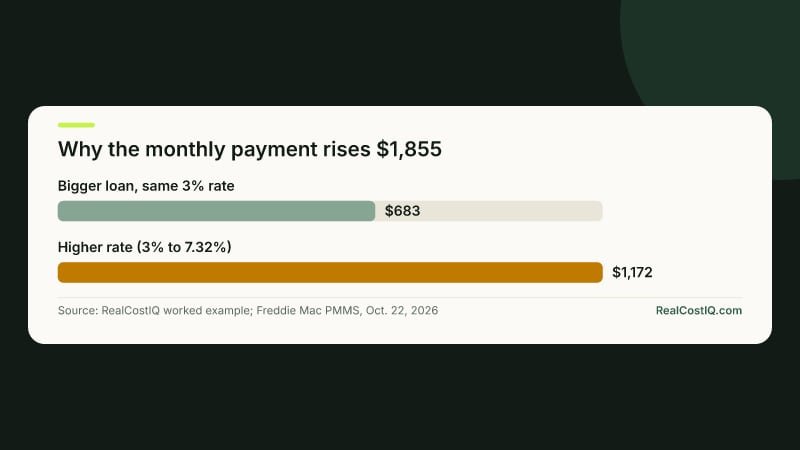 MortgagesGiving Up a 3% Mortgage to Move: What It Really Costs to Trade Up at Today's RatesMoving means trading a 3 percent loan for a new one near 7 percent. This post prices that trade in dollars, with a worked example, a rate table, and the options that avoid it.12 min read
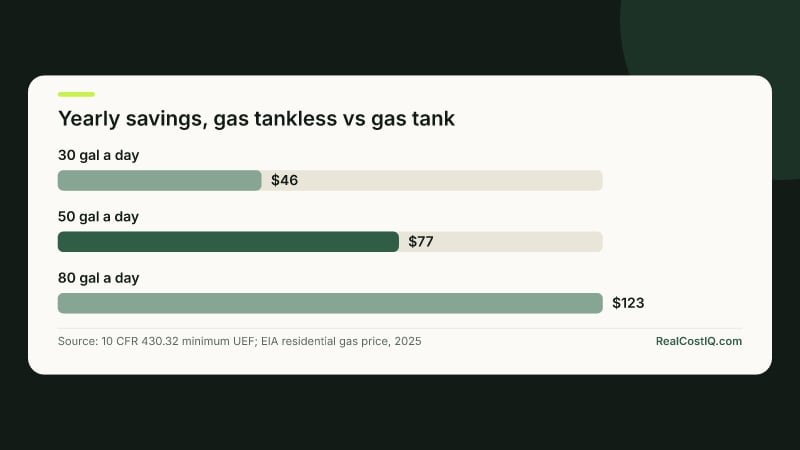 Renovation & RepairIs a Tankless Water Heater Worth It? Conversion Cost, Payback by Fuel, and When a Tank WinsTankless heaters save energy, but the savings are small. This post works out the yearly savings for gas and electric homes, then shows how long the extra cost takes to pay back.15 min read
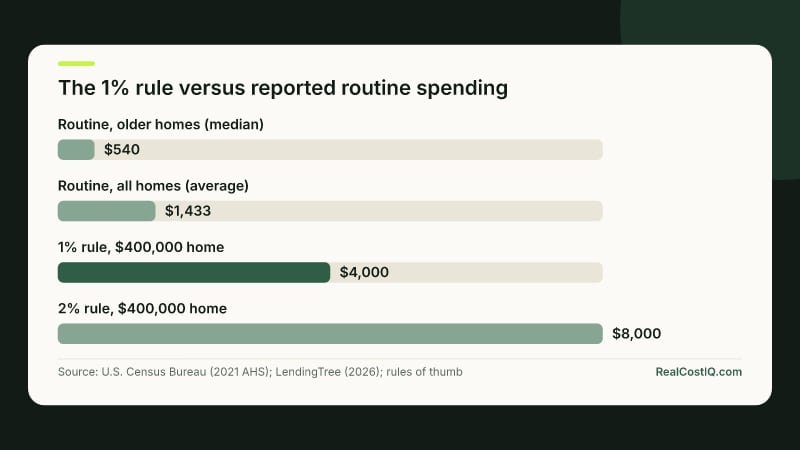 Home BuyingIs the 1% Home Maintenance Rule Right? Tested Against Home Age and What Actually Wears OutOn a $400,000 home the 1% rule says $4,000 a year. Census and Harvard data show most owners spend far less, yet one bad year can cost five times that. Here is where the rule works and where it fails.16 min read
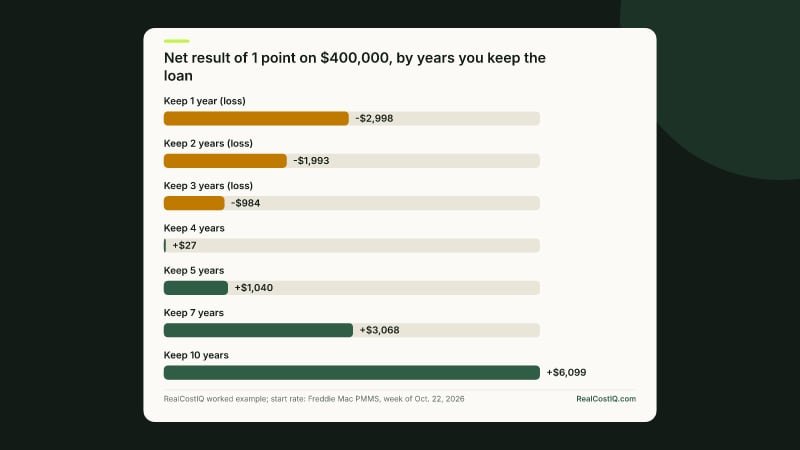 MortgagesAre Mortgage Points Worth It If You Might Refinance? The Break-Even That Accounts for Leaving EarlyA mortgage point only pays if you keep the loan past its break-even month. This post shows the net result for each year you might keep a $400,000 loan, what a refinance does to the points you paid, and when a lender credit is the better trade.13 min read
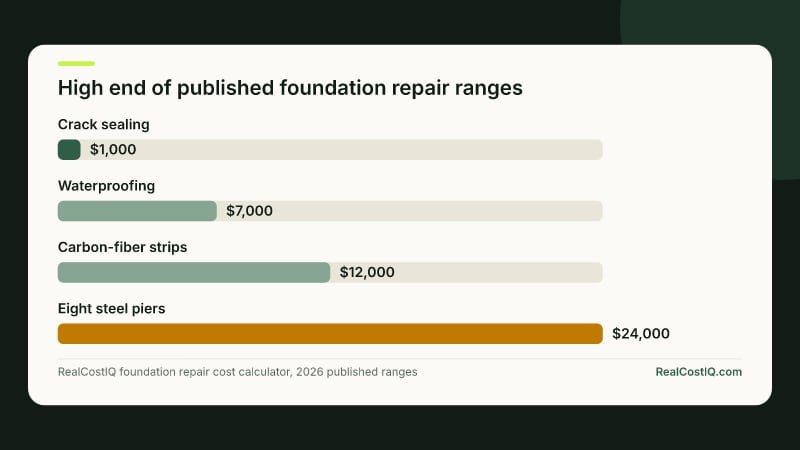 Home BuyingFoundation Crack Found at Inspection: Walk Away or Negotiate? Engineer Fees and Repair CostsA foundation crack in the inspection report does not mean the deal is dead. Hire an independent engineer before your deadline, learn whether the crack is moving, then price the repair and decide.15 min read
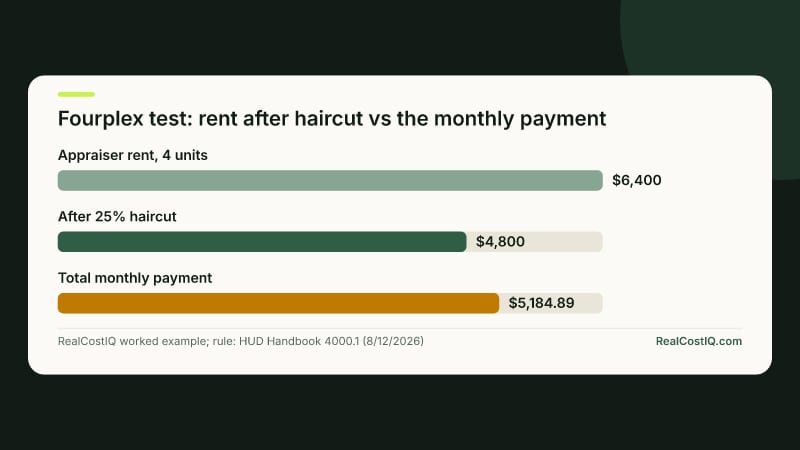 MortgagesHouse Hacking With FHA: Why Duplexes Pass and Fourplexes Fail the Self-Sufficiency TestHUD's handbook sets one test that only 3- and 4-unit FHA buyers face: 75 percent of the appraiser's market rent, counting your own unit, must cover the whole payment. This post works a $600,000 fourplex through it and shows what passes.13 min read
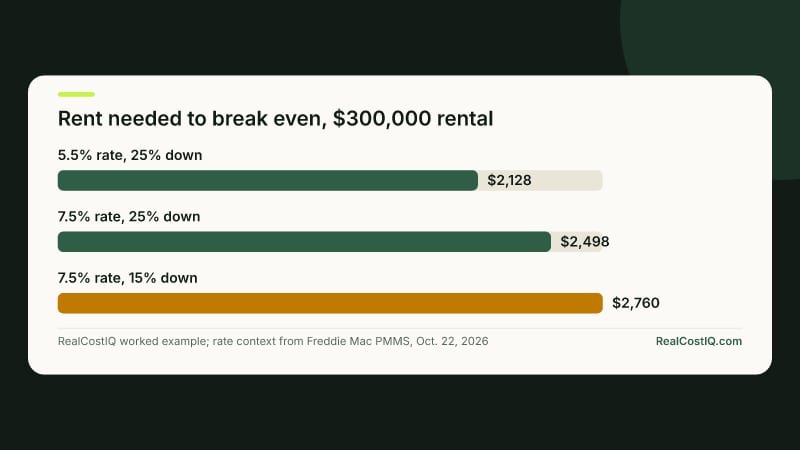 Home BuyingWhy Rentals Don't Cash-Flow at 7%: The Break-Even Rent and When Negative Cash Flow Can Still Make SenseOn a $300,000 rental, moving the loan rate from 5.5% to 7.5% adds about $295 a month to the payment and about $370 to the rent you need. Here is the break-even rent line, and when a loss can still be worth it.16 min read
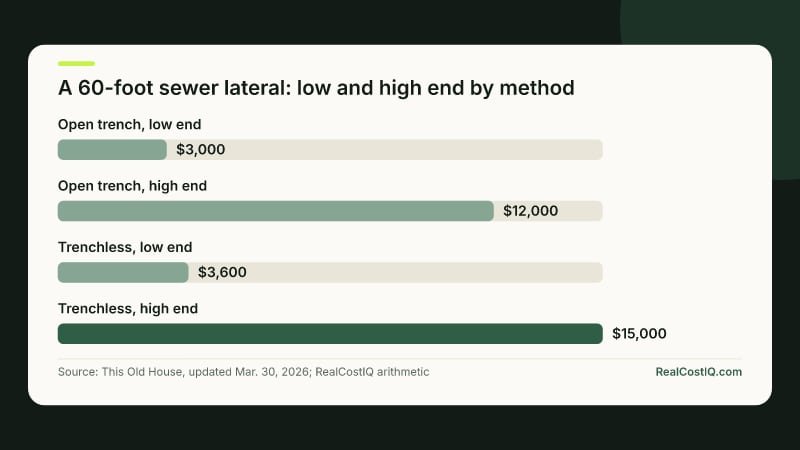 Home BuyingSewer Scope Found a Problem? Repair vs Replacement Cost and How to Negotiate Before ClosingThe camera found roots, a sag or a crack. Here is what each finding means, when a spot repair is enough, what a full replacement can cost, and how to turn a contractor quote into a credit.16 min read
 Property Taxes & FeesWhy Your Property Taxes Go Up After You Buy: Reassessment, Lost Exemptions and the Supplemental BillThe seller's tax bill is a poor guide to yours. In some states the sale resets the assessed value, in some a cap starts over, and in California a second bill arrives months after closing.13 min read
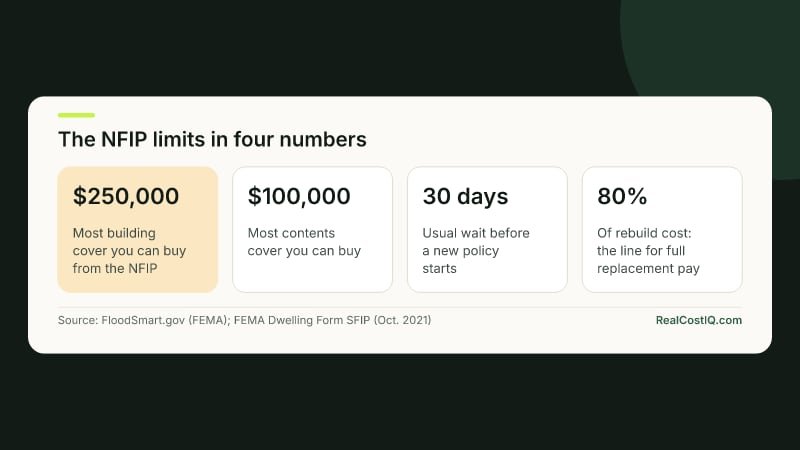 Home InsuranceHow Much Flood Insurance Do You Need? Coverage Amount, NFIP Limits and Whether to Buy It Outside a Flood ZoneFlood insurance has two limits, $250,000 for the house and $100,000 for belongings. This post shows how to pick your own amounts, what each zone costs, and whether to buy outside a mapped flood zone.17 min read
 Home BuyingRadon Test Came Back High When Buying a House: Mitigation Cost and Who PaysThe inspector's radon test read above 4. Here is how to confirm the number, what the fix costs, and the three ways a seller can pay for it, with the wording to put in the contract.17 min read
 MortgagesDebt-to-Income Ratio for a Mortgage: What Each Loan Type Allows in 2026The same buyer can pass one loan type and miss another. This post tests one $90,000 household against the conventional, FHA and VA debt-to-income rules, then shows four ways to move the ratio.16 min read
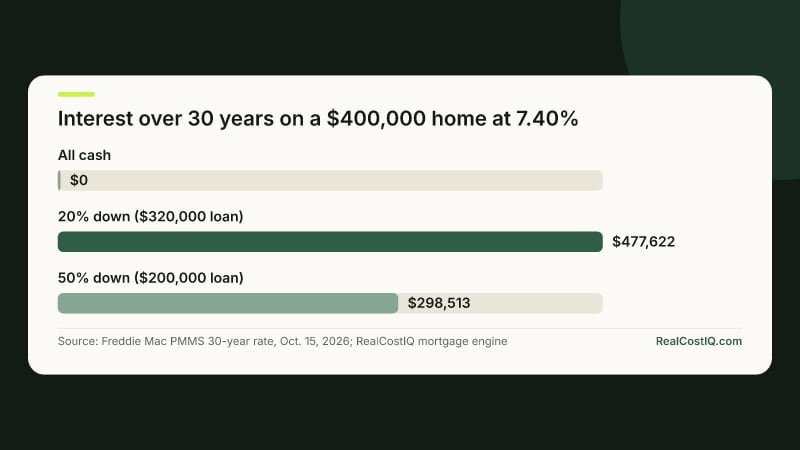 MortgagesPaying Cash vs. Getting a Mortgage in 2026: What It Really CostsOn a $400,000 home, a mortgage at 7.40 percent costs $23,579 in interest in year one. Cash saves that and about $2,400 in lender fees, but it ties up $315,643 more. Here are the numbers and the rules.13 min read
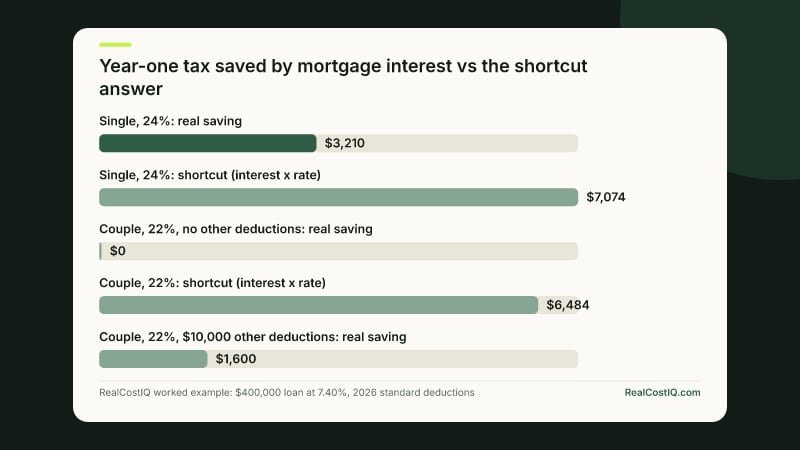 Property Taxes & FeesMortgage Interest Deduction in 2026: How Much It Really SavesMortgage interest is deductible, but the saving is not interest times your tax rate. Here is the real math on a $400,000 loan at 7.40 percent, year by year, plus the 2026 rules.15 min read
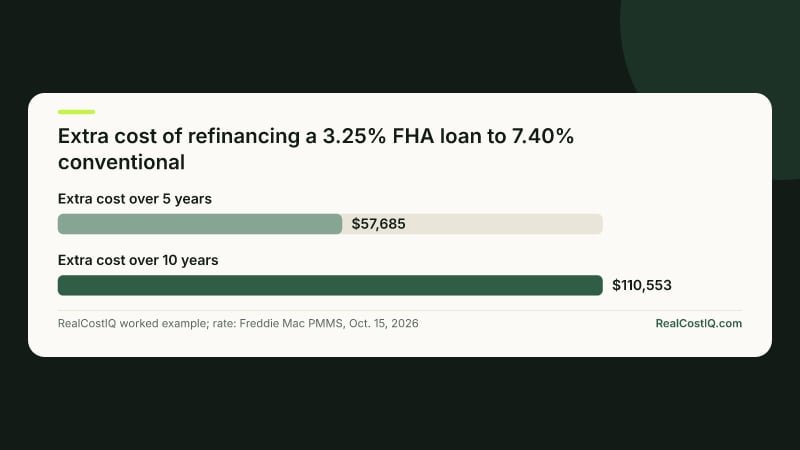 MortgagesRefinance Out of FHA Mortgage Insurance? The MIP Break-Even When Your FHA Rate Is Low, and Every Other Way to Remove ItMost FHA loans from 2013 on cannot drop mortgage insurance early. This post tests the one escape people ask about, refinancing to conventional, on a low-rate FHA loan at today's rates, then lists the exits that do work.16 min read
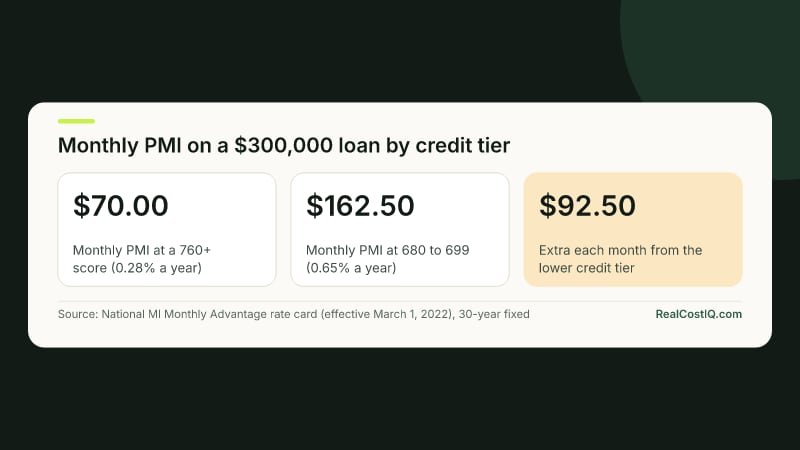 MortgagesHow to Remove PMI Early: The 80% and 78% Rules, a New Appraisal, and What to Do If Your Servicer Says NoThe law ends PMI at 78 percent of the original value. A new appraisal can end it sooner on Fannie Mae loans. This post counts the months, shows the home value you need, and lists the steps if the servicer says no.16 min read
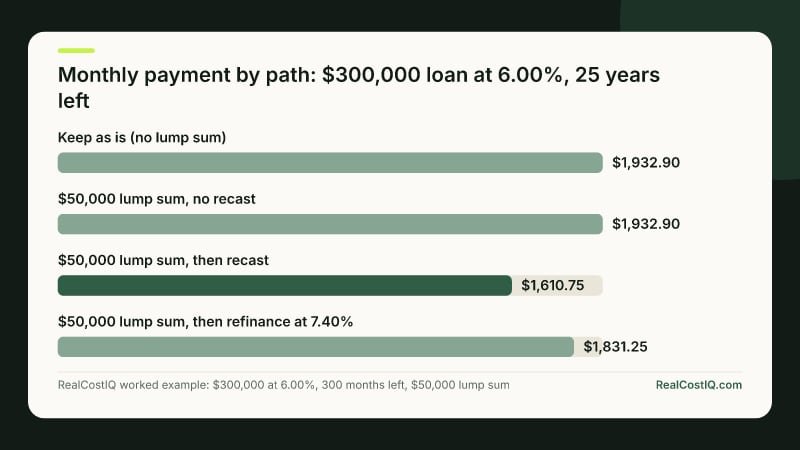 MortgagesMortgage Recast vs Refinance: How to Lower Your Payment Without a New RatePay a big lump sum and the bill does not drop on its own. A recast fixes that for about $250. This post compares a recast, no recast, and a refinance on one $300,000 loan.15 min read
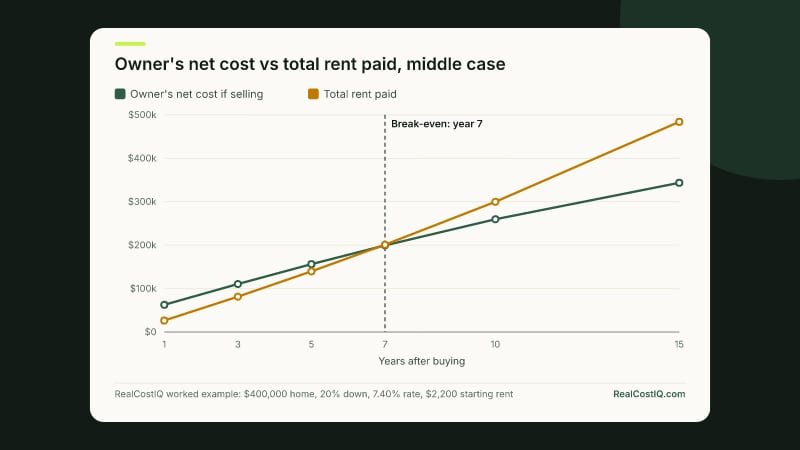 Home BuyingRent or Buy in 2026? How Many Years Until Buying Breaks EvenBuying a $400,000 home costs more than renting for a $2,200 house in the early years. This post finds the year the two lines cross, in three cases, with every input sourced and dated.16 min read
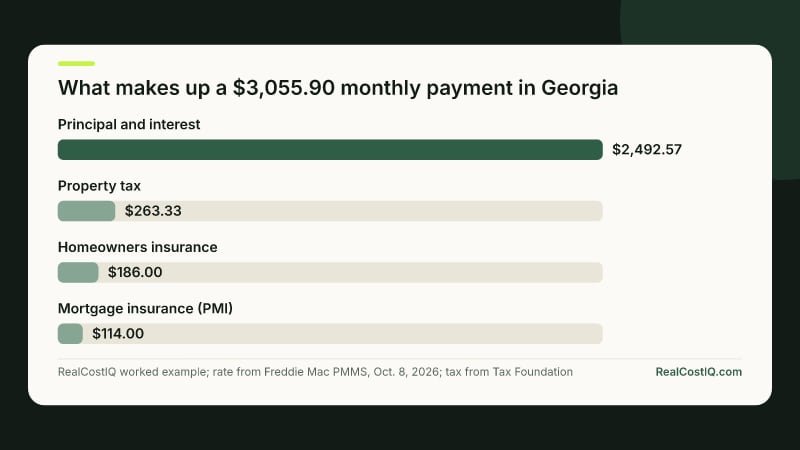 MortgagesWhat Is PITI? Your Full Mortgage Payment, Line by LineThe number in a mortgage ad is usually only part of what you pay. Here is a $400,000 home split into principal, interest, taxes, insurance and mortgage insurance, with a source for every line.17 min read
 Property Taxes & FeesIs PMI Tax Deductible in 2026? What Changed for Mortgage Insurance, Who Qualifies, and What It SavesA 2025 law brought back the deduction for mortgage insurance premiums, starting with tax year 2026. Here is who can use it, the income limit, and what it is really worth on a $380,000 loan.15 min read
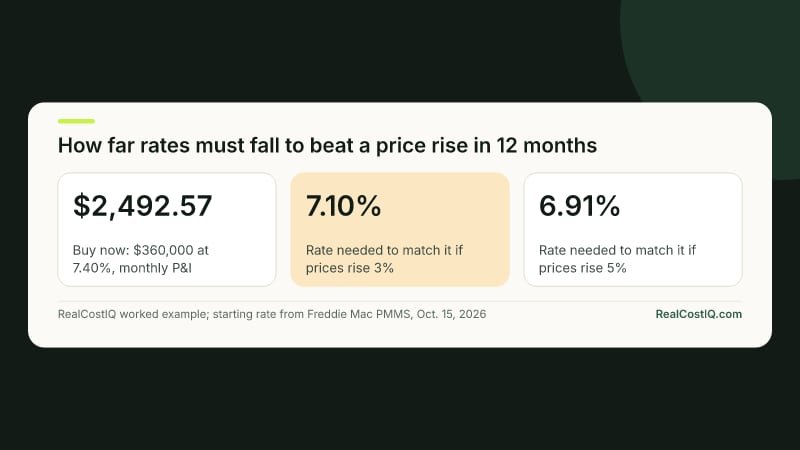 MortgagesMortgage Rates and Home Prices, October 2026: Buy Now or Wait?Nobody knows where mortgage rates go next. What you can know is how much a rate drop has to be worth before waiting pays. This October 2026 update uses the latest Freddie Mac rate and NAR home price.17 min read
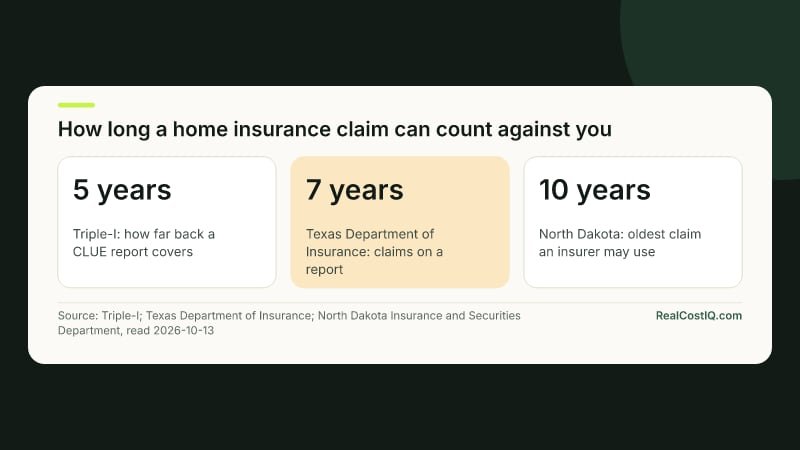 Home InsuranceShould You File a Small Homeowners Claim? The Deductible-Versus-Surcharge Arithmetic, What a CLUE Report Holds and for How Long, and How to Get Yours FreeTriple-I says a CLUE report goes back five years; the Texas Department of Insurance says seven. Neither publishes a surcharge. Here is the break-even arithmetic at named inputs, what the regulators say about inquiries, and how to pull your own report free.16 min read
 Home BuyingUnpermitted Work on a House You're Buying or Selling: What the Appraiser Reports, What the Lender Can Require, What Legalising It Costs, and What Your Insurer May SayFannie Mae's guide gives the appraiser one sentence on additions without permits and no lender consequence. The real gatekeepers are zoning legality, the appraiser's value call and your insurer's policy wording. Here is what each source actually says.16 min read
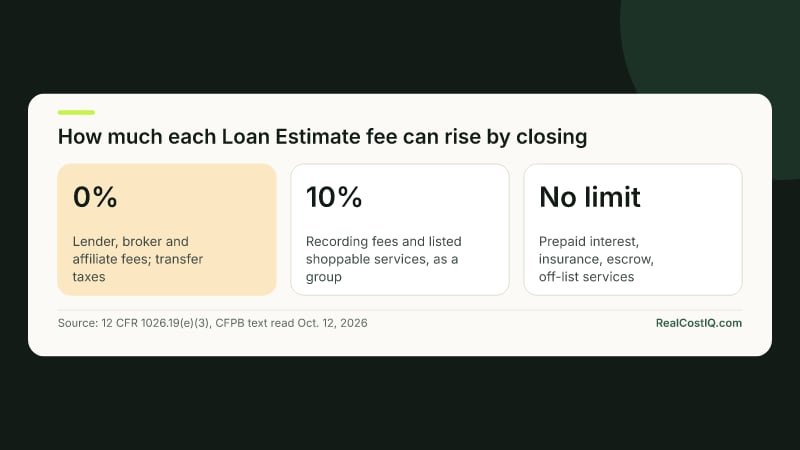 Home BuyingLoan Estimate vs Closing Disclosure: Which Fees Can Change (0%, 10%, No Limit)Some fees on your Loan Estimate cannot rise at all, some can rise 10% as a group, and some have no cap. Here is how Regulation Z sorts them, what lets a lender reset the baseline, and how a refund is paid.19 min read
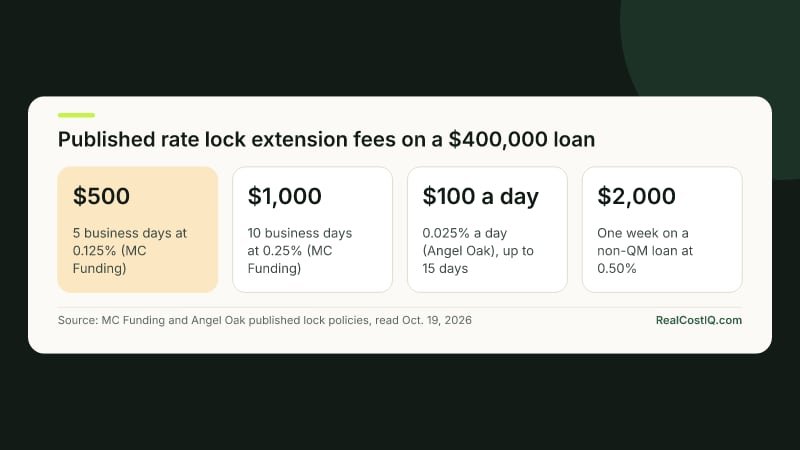 MortgagesRate Lock Expires Before Closing: Extension Fees and Your OptionsWhat happens when a rate lock expires before closing, what two published lender policies charge to extend it, and what federal rules do and do not say. Includes a worked payment example.16 min read
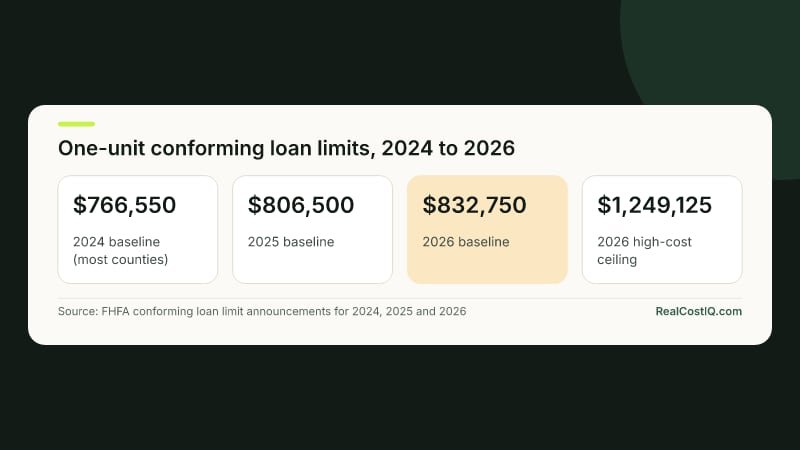 Mortgages2026 Conforming Loan Limits: The $832,750 Baseline, High-Cost Areas Up to $1,249,125, and What Changes When Your Loan Crosses Into High-Balance or JumboThe $832,750 baseline is only the floor of a county-by-county map that tops out at $1,249,125. Here is how FHFA sets it, what Fannie Mae changes for high-balance loans, and why jumbo is a lender question, not an agency rule.16 min read
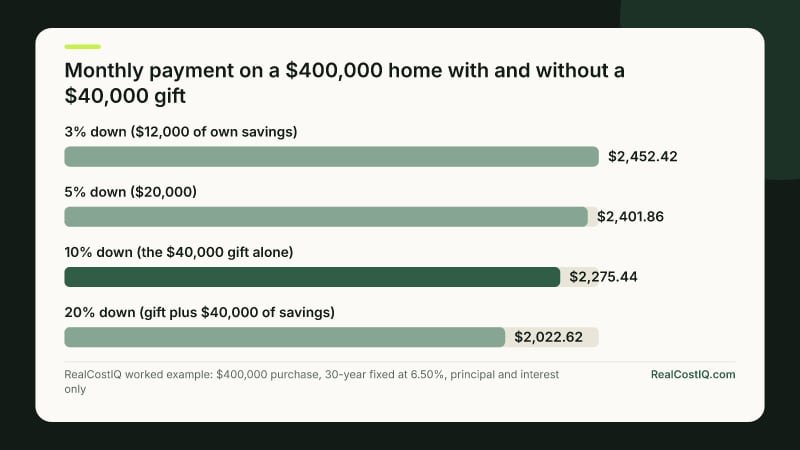 Home BuyingUsing Gift Money for a Down Payment: Who Can Give It, What the Gift Letter Must Say, How Lenders Trace the Funds, and Gifts of EquityEvery major program accepts gift money, but each defines the donor, the letter and the proof of transfer differently. Here is the side-by-side from the current guides, the large-deposit trap, and how a gift of equity differs from a cash gift.22 min read
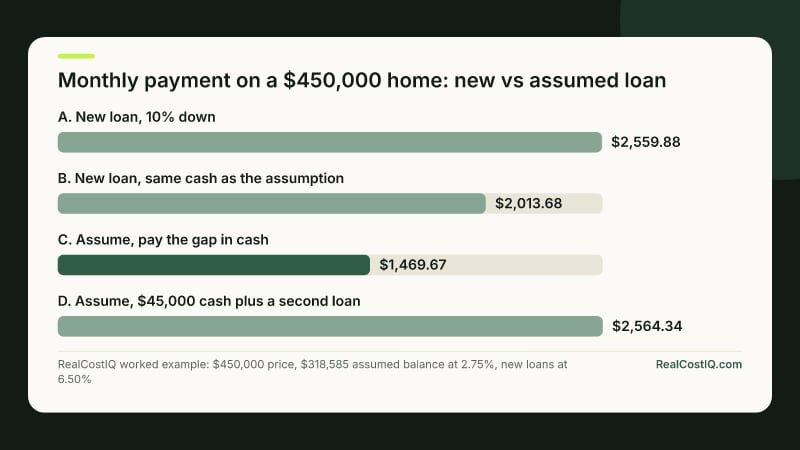 MortgagesAssumable Mortgages: Which Loans Can Be Taken Over, What the Buyer Must Qualify For, and the Cash Gap Over the Seller's Low BalanceA seller's 2.75% loan is only worth taking over if you can fund the difference between the price and the balance. Here is which loans allow it, what the buyer must qualify for, and the arithmetic of the gap.24 min read
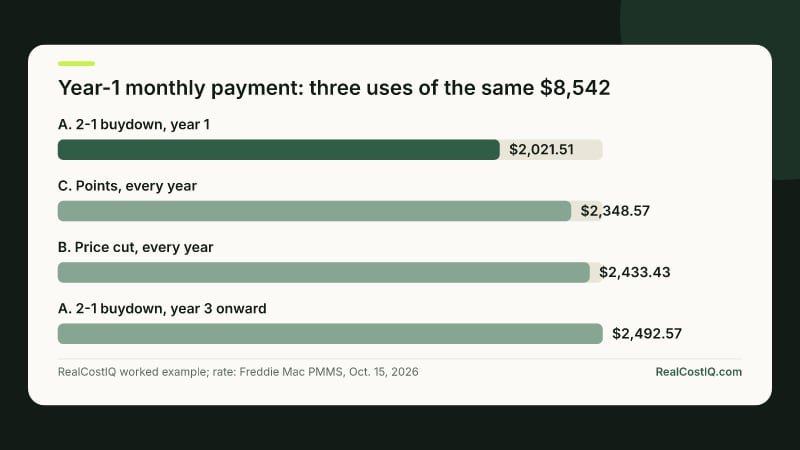 MortgagesBuilder Offers a 2-1 Buydown or the Same Money Off the Price: Which Is Better?Same builder dollars, three uses: a 2-1 buydown, a lower price, or permanent points. Worked totals at months 12 and 24 and years 5 and 10, plus the rules on unused buydown money.20 min read
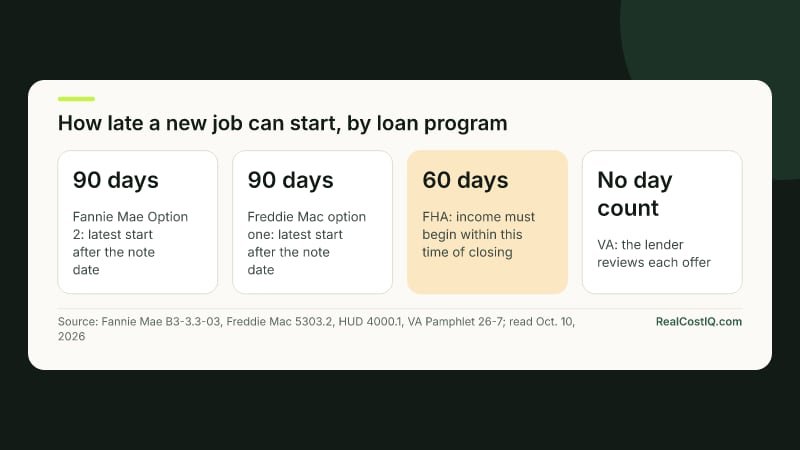 Home BuyingMortgage Offer Letter Rules: Fannie Mae, Freddie Mac and FHA Start-Date WindowsA signed offer can count as income before the first paycheck, but each program sets its own start-date window, paperwork and cash reserve. Here is the side-by-side, and what a slipped start date does to the file.19 min read
 MortgagesGetting a Mortgage After a Layoff: Employment Gaps, Severance and Unemployment Income, and What Lenders Count While You Are Between JobsWith no paycheck, a lender has little to qualify you on. This is what the four main guides say about gaps, unemployment benefits and severance, and which income can fill the space.20 min read
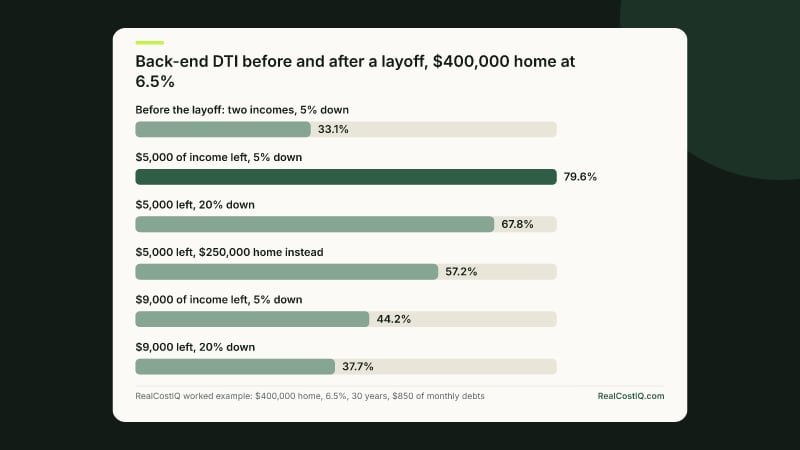 Home BuyingLaid Off Before Closing: 10-Day Job Check, What to Disclose and Your OptionsA layoff between pre-approval and closing does not automatically end the purchase, but it does change the file. Here is the order to act in, what the guides require, and what each option actually fixes.18 min read
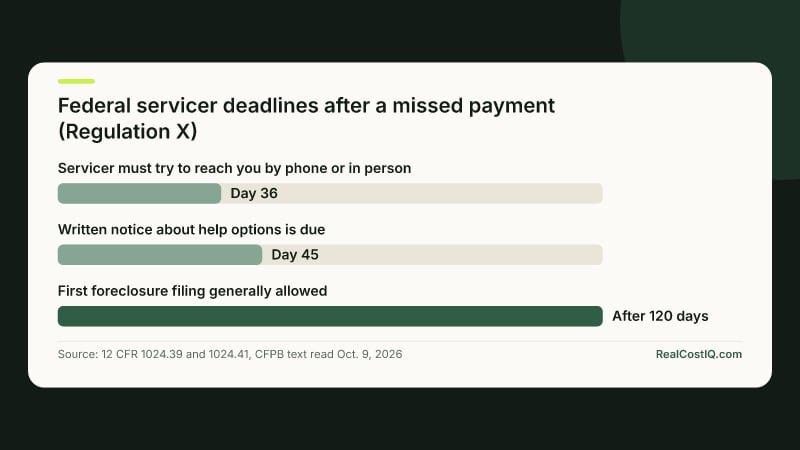 MortgagesLaid Off With a Mortgage: What Your Servicer Must Offer, Forbearance vs Repayment Plan vs Modification, and the Rules Before Foreclosure Can StartCalling the servicer before you miss a payment is the first step. This post sets out what federal rules require of the servicer, how Fannie Mae, Freddie Mac, FHA and VA options differ, and when foreclosure can start.21 min read
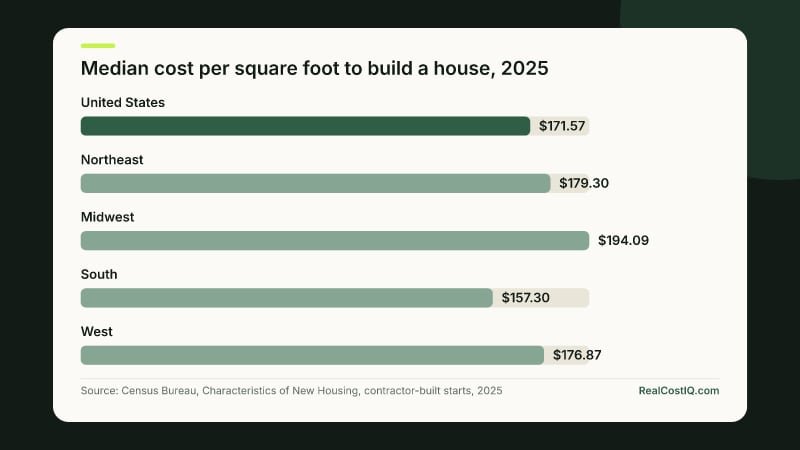 Home BuyingCost to Build a House Per Square Foot (2026): Average Cost by Region, Plus Land and FinancingTwo federal and industry datasets give two different per-square-foot numbers for a new house. Here is what each one divides, and what a builder's per-foot quote usually leaves out.19 min read
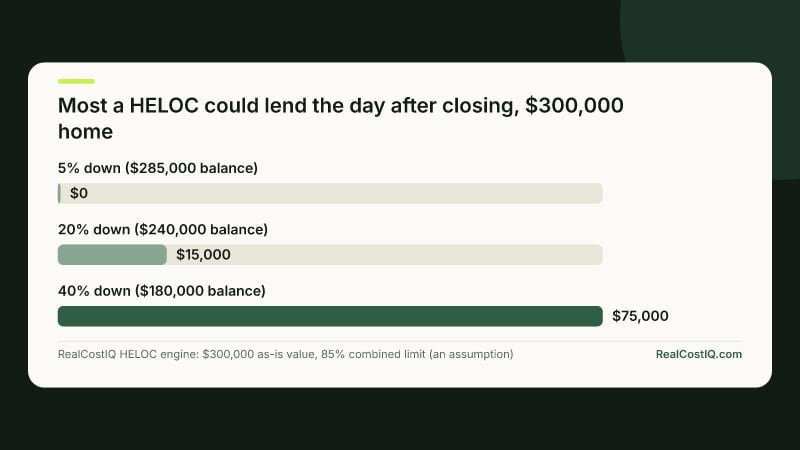 MortgagesFinancing a Fixer-Upper at Purchase: FHA 203(k), HomeStyle and CHOICERenovation vs a HELOC LaterA renovation mortgage rolls the repair budget into the purchase loan, sized on the value after the work. Here are the rules, a worked payment example, and when a HELOC after closing fails.26 min read
 Home BuyingRepair Allowance After a Home Inspection: Credit Limits (3% to 9% Fannie Mae, 6% FHA) and Roof and AC PricingAn inspector says the roof or AC is near the end of its life. This is how to price the ask, which form it should take, and where the lender's rules cap it.19 min read
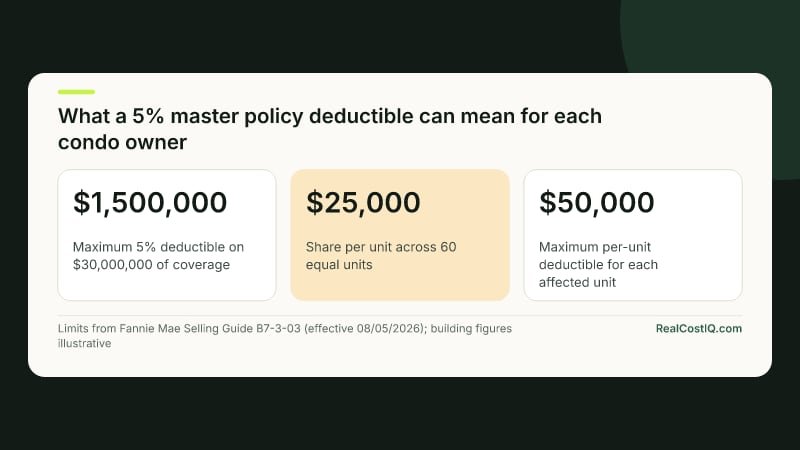 Home InsuranceCondo Insurance (HO-6) vs the HOA Master Policy: What You Insure YourselfThe association insures the building; you insure what it does not. Where that line falls depends on one sentence in your governing documents. Here is how to find it, size your HO-6, and meet the lender's condo insurance rules.15 min read
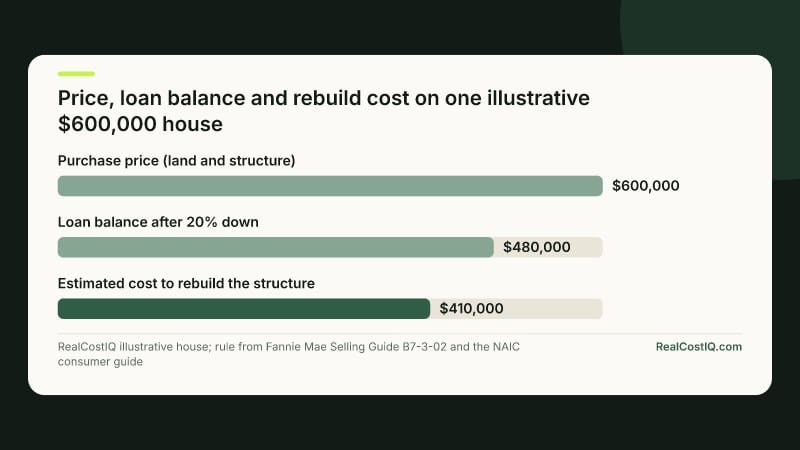 Home InsuranceHow Much Homeowners Insurance Does Your Mortgage Lender Require?The lender does not pick a number. It tests your policy against replacement cost, a deductible ceiling and a named-mortgagee clause. Here is each test, the flood exception, and what Massachusetts law says about a lender asking for more.15 min read
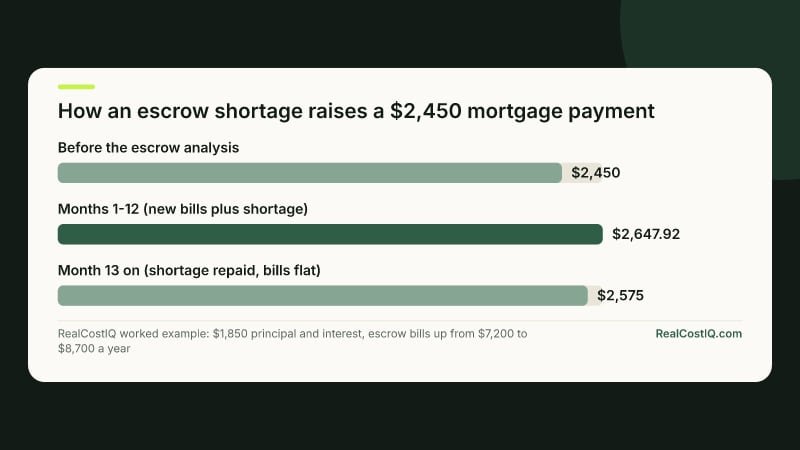 MortgagesEscrow Shortage: Why Your Mortgage Payment Went Up and What to DoYour principal and interest did not change, but your payment did. Here is how the annual escrow analysis produces a shortage, what your servicer may and may not demand, and how to check the math.19 min read
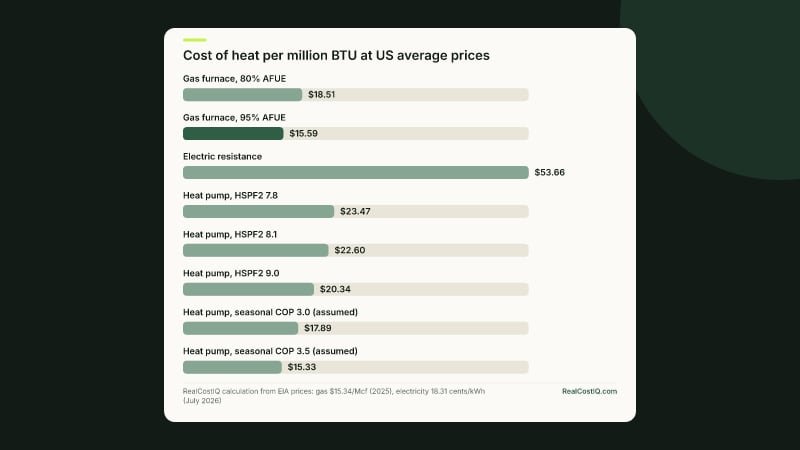 Renovation & RepairHeat Pump vs Gas Furnace in 2026: Installed Cost and Cost to RunThe math behind the choice: what each system costs to install, what a million BTU of heat costs from gas and from electricity at current EIA prices, and where a heat pump stops winning.24 min read
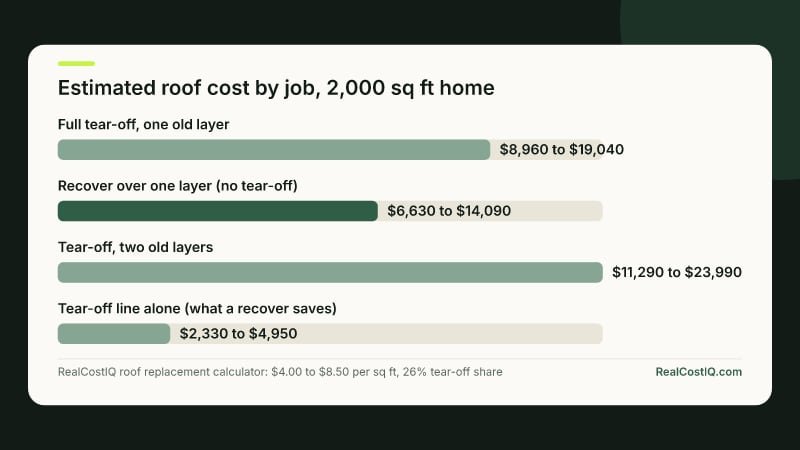 Renovation & RepairReroofing Over Old Shingles vs. a Full Tear-Off: Cost, Code and WarrantyA roof-over skips tear-off, but it is not always legal, it can cost you the shingle warranty, and it mostly defers the tear-off cost. Here is the decision rule.18 min read
Canada
Canada blog → MortgagesHELOC Rates in Canada: Prime Plus a Spread, What the Big Banks Charge, and the 65% LimitA Canadian HELOC is priced as the lender's prime rate plus a spread, and only some banks print the spread. This post prices C$100,000 at five spreads and lists the set-up costs, including Alberta's.15 min read
 Home BuyingRent or Buy in Vancouver in 2026: Condo vs Townhouse, With Strata Fees and Property Transfer TaxA Vancouver condo at C$682,500 costs about C$4,645 a month to own against C$2,900 to rent a two-bedroom condo. Buying catches up after about 11 years in the base case. A C$1,016,700 townhouse does not catch up against the same rent.16 min read
 Home BuyingSelling in Toronto, Buying in Calgary: What the Same Detached House Costs to Buy, Close On and TaxA move from Ontario to Alberta changes the price, the closing bill and the property tax base. This post puts a Toronto detached house next to a Calgary one, line by line, using September 2026 board data.13 min read
 Home BuyingToronto Condo Fees in 2026: What's Normal per Square Foot, How Fast They Rise, and Spotting Special-Assessment RiskA fair Toronto condo fee is about C$0.75 to C$0.85 a square foot, so C$525 to C$595 on a 700-square-foot unit. A fee far below that can be a warning, because it can mean an empty reserve fund.17 min read
 Home BuyingBuy Now or Wait for Spring 2027? Canada's Housing and Rate Outlook After the October DecisionForecasters expect flat prices in 2026 and a small rise in 2027, with mortgage rates edging up. On a C$600,000 home, a 2.5% price fall only offsets a 0.26-point rate rise.12 min read
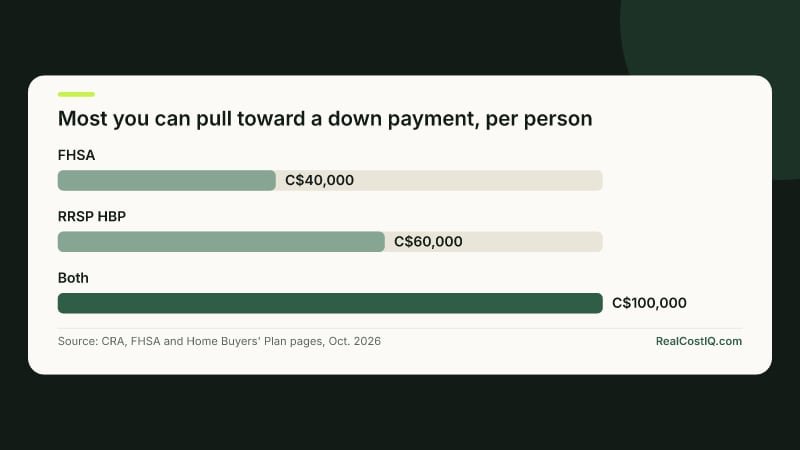 Home BuyingFHSA or RRSP Home Buyers' Plan for Your Down Payment? How Much Each Adds, Using Both, and RepaymentThe FHSA can hold C$40,000 for a first home and has no repayment. The RRSP Home Buyers' Plan lets you borrow C$60,000 from yourself and pay it back over 15 years. You can use both.14 min read
 MortgagesMortgage Life Insurance from Your Bank vs Term Life: What You Pay and What Your Family GetsOn a C$500,000 mortgage at age 35, one big bank's example costs C$67.66 a month. A 20-year term policy for the same amount was quoted at C$22.93. Here is what each one pays.15 min read
 Home BuyingWhat a House Really Costs per Month in Canada Beyond the Mortgage (First-Year Budget)On a C$750,000 Toronto house, the costs beyond the mortgage run about C$1,622 to C$2,247 a month in our example. The average Canadian owner with no mortgage spent about C$1,146 a month on shelter in 2023.12 min read
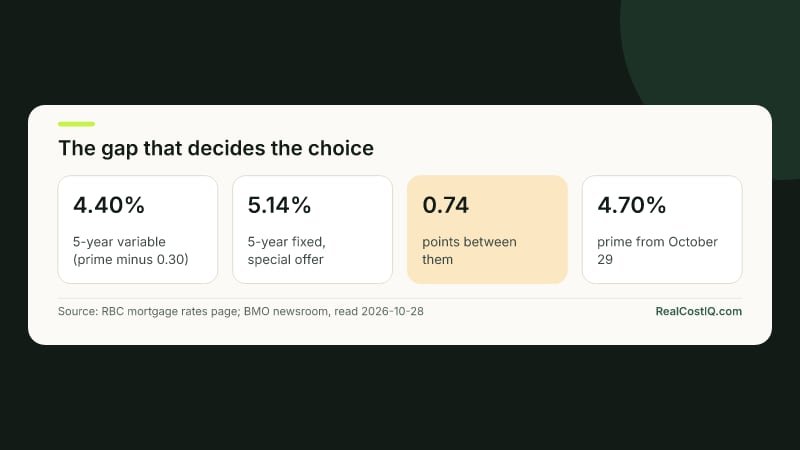 MortgagesFixed or Variable in Canada After the October 28 Rate DecisionThe Bank of Canada raised its rate on October 28, 2026. A 5-year variable still starts below a 5-year fixed, but the gap is small. Here is how far prime must rise for variable to lose, on a C$600,000 and a C$750,000 mortgage.16 min read
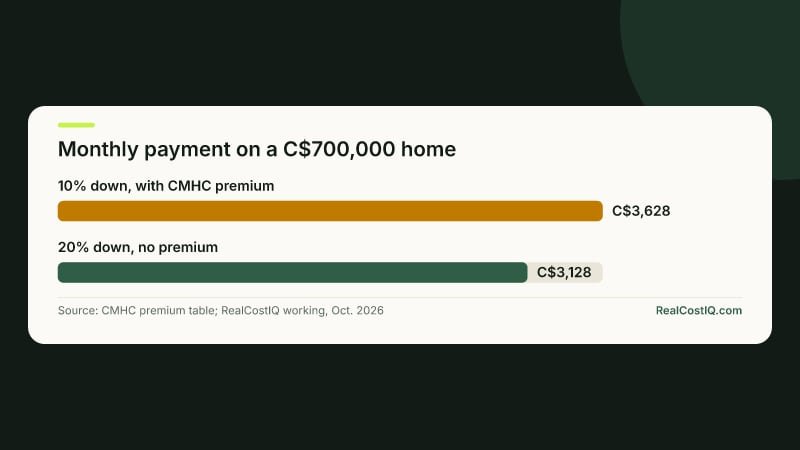 Home BuyingParents Helping With the Down Payment in Canada: Gift Letters, Co-Signing, Going on Title, and What Each CostsA parent can gift money, co-sign the loan or go on title, and each costs something different. This post prices the three routes on one Ontario purchase and shows what lenders ask for.13 min read
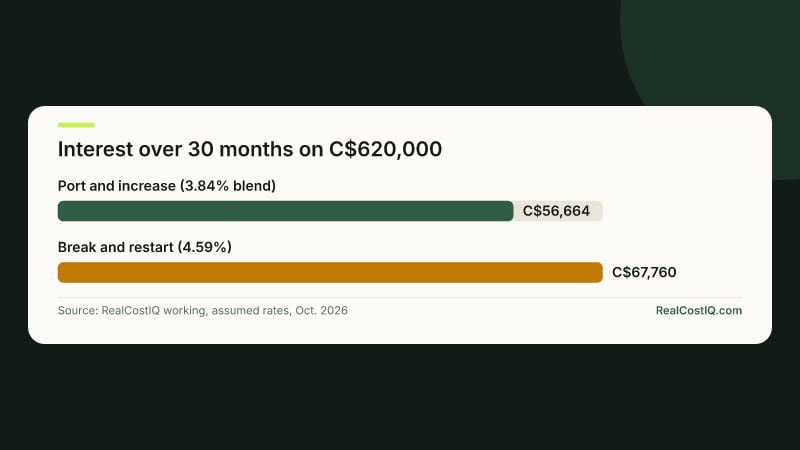 MortgagesPorting Your Mortgage When You Move in Canada: Port, Break or Blend?Porting keeps your old rate and skips the penalty, but only for the amount you already owe. This post works a C$200,000 top-up three ways and shows what lenders publish, and what they do not.16 min read
 Property Taxes & FeesToronto's Two Land Transfer Taxes: First-Time Rebates, Co-Buyers Who Don't Both Qualify, and the Bill at C$800K and C$1.1MA Toronto buyer pays Ontario's land transfer tax and the City's own. Each has its own first-time rebate, and each treats a co-buyer who owned before in a different way. Here is the bill at C$800,000 and C$1.1M, case by case.16 min read
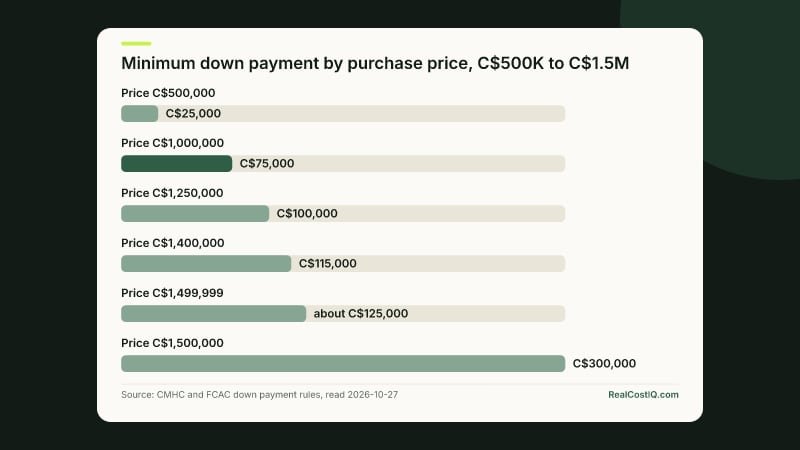 MortgagesBuying a C$1 Million Home in Canada: Minimum Down Payment, CMHC Premium and the Monthly PaymentOn a C$1 million home the minimum down payment is C$75,000, and the mortgage can still be insured because the cap is C$1.5 million. The payment is about C$5,672 at the minimum.14 min read
 Home BuyingBuying a Rental Condo in Ontario in 2026: Why Most Don't Cash-Flow, and the Numbers That Decide ItOn a C$600,000 Toronto condo with 20% down, rent after vacancy covers the mortgage interest but not the interest plus fees and tax. The cash flow is about minus C$1,709 a month.13 min read
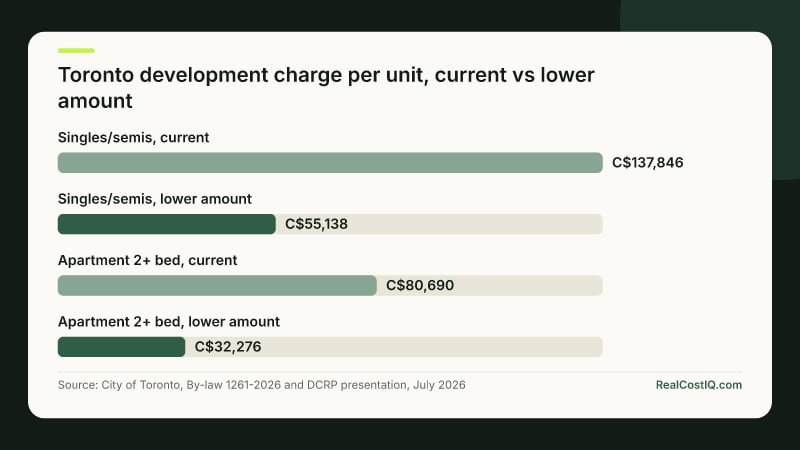 Home BuyingNew Build vs Resale in Ontario: Development Charges, the Tarion Fee, Hookups and the HST Adjustment on Your Closing BillA new build adds lines that a resale never has. This post reads Toronto's development charge by-law, Tarion's fee table and the addendum's Schedule B to show which lines can reach you and how to cap them.15 min read
 MortgagesWhy Big-Bank Mortgage Penalties Are So High: How TD, RBC, Scotiabank, BMO and CIBC Word the IRD, and Where to Find Your DiscountAll five big banks compare your rate to a posted rate, not to what they would offer you today. This post reads each bank's own published wording and shows where your discount sits.18 min read
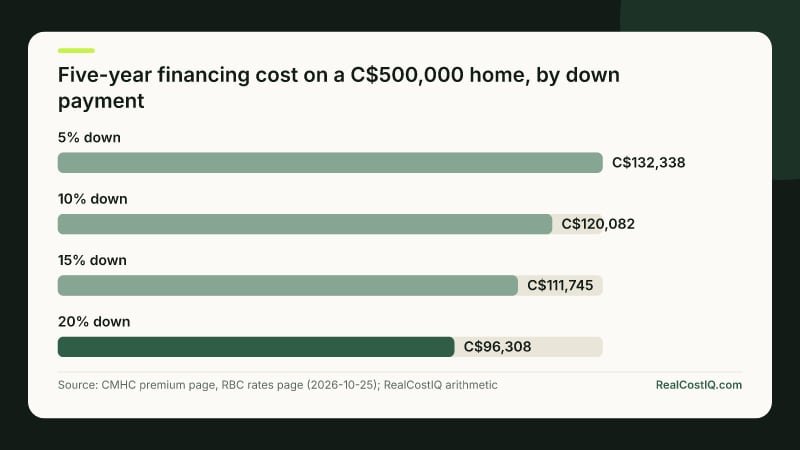 Mortgages20% Down or Pay CMHC Insurance? The Break-Even at 5, 10, 15 and 20% DownOn a C$500,000 Ontario home, each extra C$25,000 down earns about 7% to 12% a year over a five-year term. The best jump is from 15% to 20% down, which removes the premium.15 min read
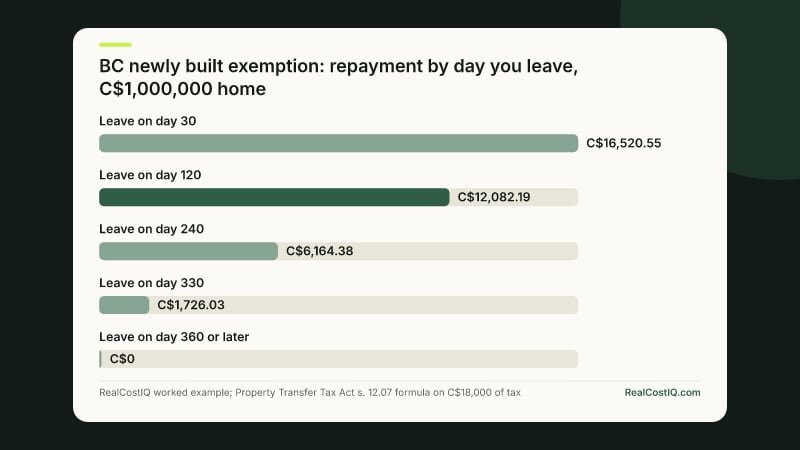 Property Taxes & FeesBC First-Time Buyer and Newly Built Property Transfer Tax Exemptions: Who Qualifies, and When You Have to Pay It BackBoth BC exemptions come with a move-in clock. Miss the 92-day start or leave before the first anniversary and part of the tax comes back as a bill. Here is who qualifies and what the repayment looks like.14 min read
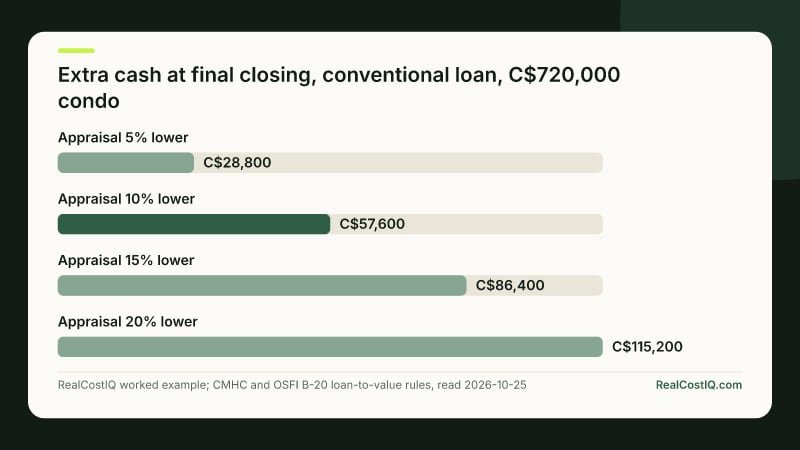 Home BuyingPre-Construction Condo Appraised Below Your Price? What You Owe at Final Closing and Your OptionsYou signed for a new condo years ago. At final closing the lender's appraiser says it is worth less. The loan shrinks and the gap lands on you. Here is the math at four appraisal levels, and the choices you have.15 min read
 Home BuyingClosing Costs in Canada Beyond the Land Transfer Tax: Lawyer Fees, Disbursements and the Statement of AdjustmentsLand transfer tax is the big line on an Ontario closing. This post reads the rest of the bill: the lawyer's fee, disbursements, registration fees and the statement of adjustments, with a C$800,000 example and the Alberta and British Columbia contrast.18 min read
 Property Taxes & FeesOntario's New-Home HST Break (April 2026 to March 2027): Who Qualifies, Who Doesn't, and the Dates That MatterOntario's temporary HST relief on new homes can remove up to C$130,000 of tax, but only if the agreement was signed between April 1, 2026 and March 31, 2027. This post answers the edge cases: signing dates, changed contracts, assignments, rentals and renovations.15 min read
 Home BuyingBuy First or Sell First in Canada? The Bridge-Loan Math on a Move-Up PurchaseSelling first, buying first with a bridge loan, and buying with no firm sale each have a price and a risk. This post prices all three on one C$950,000 move-up and shows which risk costs the most.14 min read
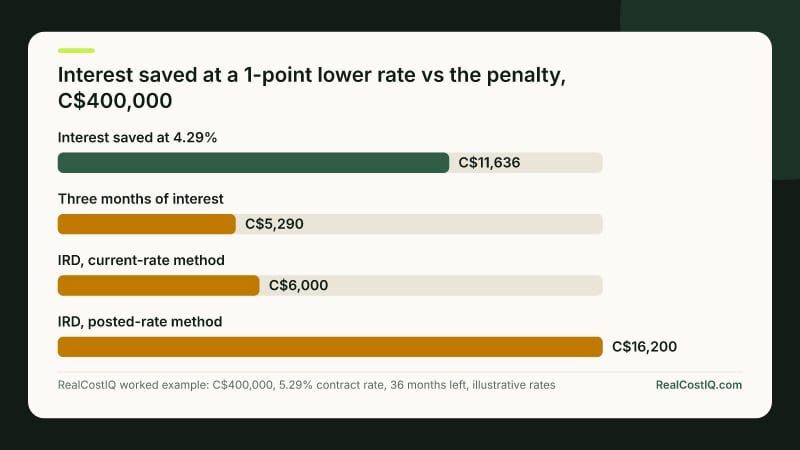 MortgagesShould You Break Your Mortgage for a Lower Rate? Break-Even, Blend-and-Extend and the 120-Day Early RenewalBreaking a fixed mortgage for a lower rate only pays when the savings beat the penalty. This post works the break-even on C$400,000, then compares blend-and-extend and the 120-day early renewal.15 min read
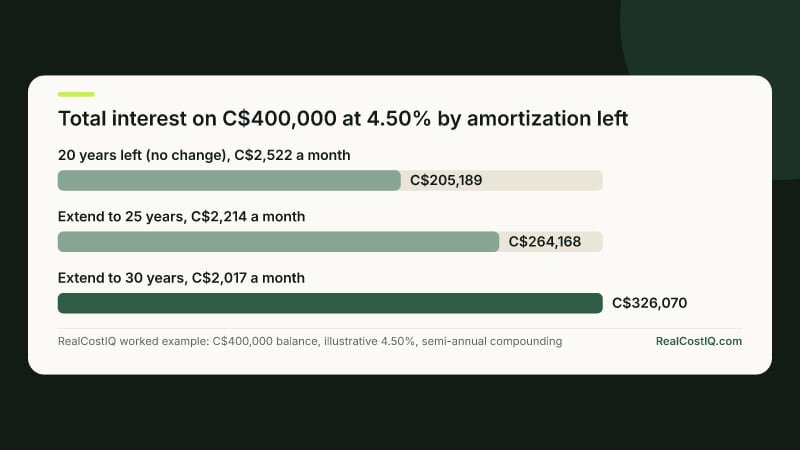 MortgagesExtending Your Amortization at Renewal in Canada: Lower Payment, Higher Lifetime CostA longer amortization at renewal lowers the payment today and raises the interest you pay in total. This post prices it on a C$400,000 balance, then covers who can say yes and what to ask first.19 min read
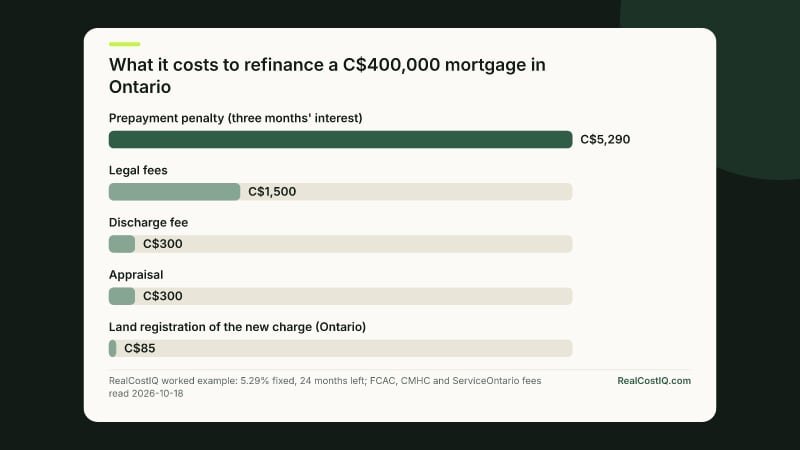 MortgagesRefinancing Your Mortgage in Canada: the 80% Limit, the Costs, and the Break-EvenA refinance lets you borrow up to 80% of your home's value, but it comes with a penalty, legal and appraisal costs. This post prices a C$160,000 cash-out and shows when the costs pay back.14 min read
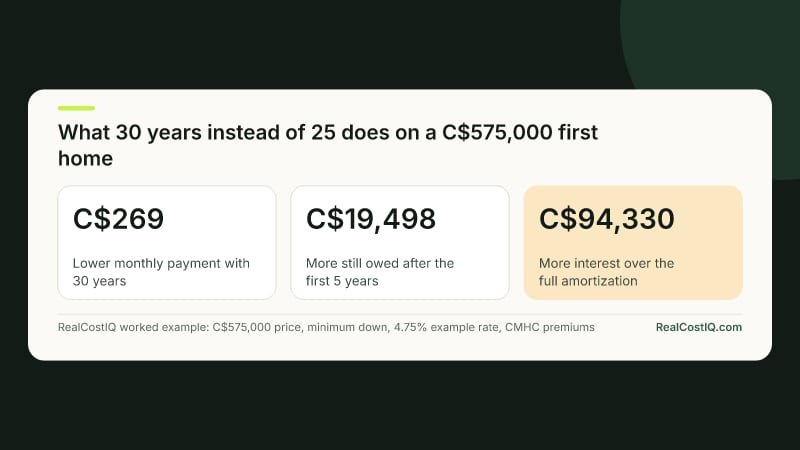 Mortgages30-Year Amortization for First-Time Buyers in Canada: Lower Payment vs. Total InterestOn a C$575,000 first home at an example 4.75%, a 30-year amortization cuts the payment by about C$269 a month. It also adds about C$94,000 of interest over the full term. Here is who qualifies and how the numbers work.14 min read
 Home BuyingWhat Income Do You Need to Buy an Average Home in Each Province? (2026)A typical Ontario home needs about C$169,900 of household income to pass the stress test with the minimum down payment, and a typical New Brunswick home about C$87,200. Each figure uses a named city's 2026 property-tax rate.20 min read
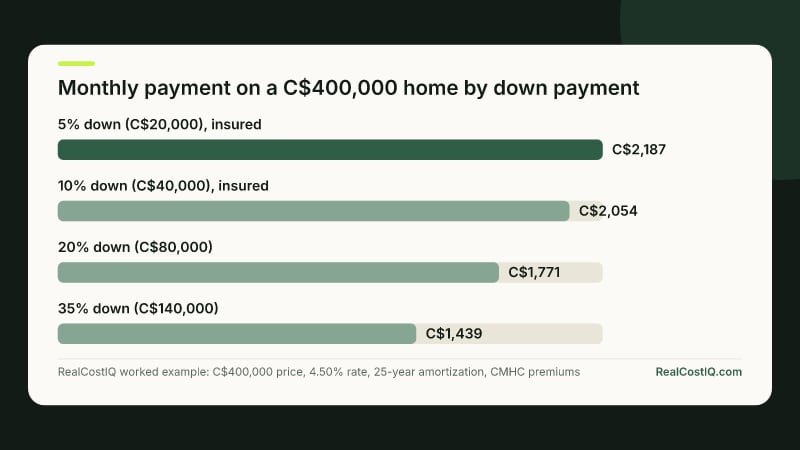 Home BuyingBuying Your First Home as a Newcomer to Canada: Down Payment, Credit and Insured MortgagesA newcomer can buy with as little as 5% down. The three mortgage insurers each have a newcomer programme, and none needs a Canadian credit score. Here is what each one asks.16 min read
 Home BuyingCalgary vs Edmonton in 2026: The Full Cost of Buying and Owning a HomeSame Alberta rules, very different bills. On the same C$500,000 home, Edmonton's 2026 property tax is about C$1,857 a year higher than Calgary's. Prices flip the picture.15 min read
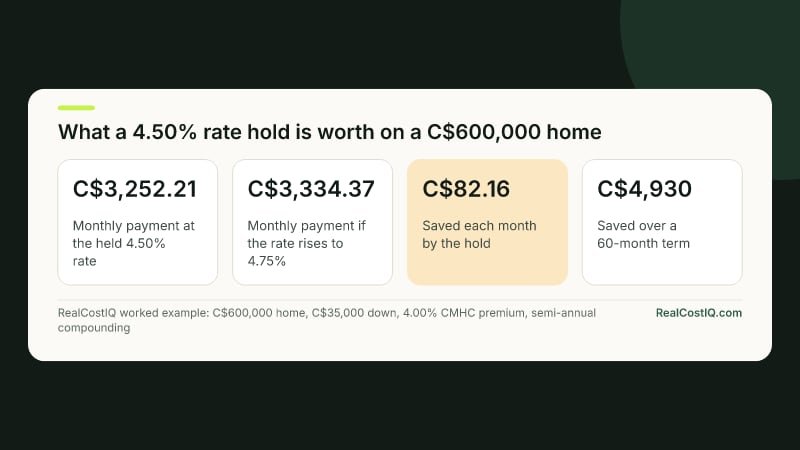 MortgagesMortgage Pre-Approval in Canada: What the Rate Hold Covers and What Lenders Re-CheckA pre-approval holds your rate, often for 120 days. It does not hold your approval. Income, debts, credit and the property are all checked again.14 min read
 Home BuyingRent or Buy in Toronto in 2026? Condo vs House, Worked OutA Toronto condo bought at C$640,000 costs about C$1,581 a month more than a comparable two-bedroom rental. Buying only catches up after about 11 years in the base case, and not at all against a one-bedroom.16 min read
 MortgagesBank of Canada Raises Rate to 2.50% (Oct 28, 2026): What It Means for Your Mortgage PaymentA quarter-point move by the Bank of Canada changes the payment on a C$500,000 variable mortgage by about C$69 a month. A fixed-rate mortgage does not move until renewal.16 min read
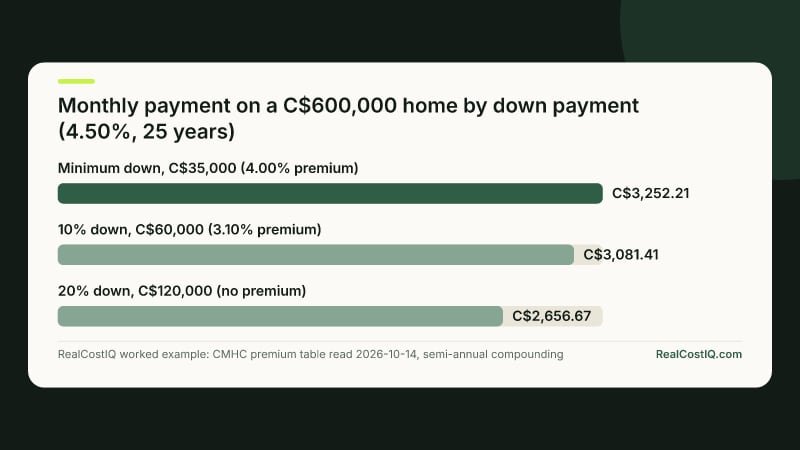 MortgagesMortgage Payment on a C$600,000 Home in Canada: Minimum Down, 10% and 20% Down, CMHC Premium IncludedOn a C$600,000 home at an example rate of 4.50% over 25 years, the payment is about C$3,252 with the minimum down payment and about C$2,657 with 20% down.13 min read
 MortgagesRefinancing to Add a Secondary Suite in Canada: The Insured 90%, the C$2 Million Cap, the 30-Year Amortization, What Counts as a Suite, and Why the C$80,000 Loan Never OpenedSince 2025-01-15 an owner can refinance with insured financing to build a suite, up to 90% loan-to-value on the lending value (the lesser of the as-improved value, or the as-is value plus the cost of the work). What the rule actually allows, where the money cannot go, and what happened to the C$80,000 loan.19 min read
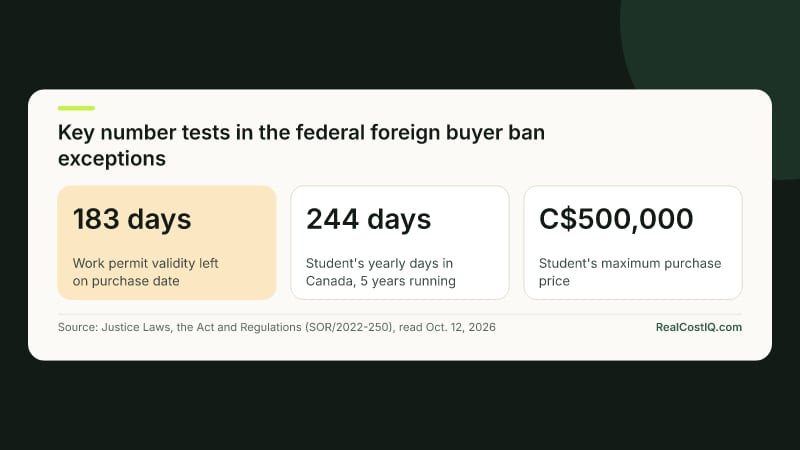 Home BuyingCanada's Ban on Foreign Buyers of Homes: Who Is Caught, the Exceptions, the Penalties, When It Ends, and Why the Date Is Not ObviousThe federal ban is a yes-or-no rule about who may buy, not a tax on the price. Here is what the Act and Regulations say about who is caught, which properties and places are outside it, the exceptions, the penalty, and the January 1, 2027 repeal date, read from the consolidated text on 2026-10-12.19 min read
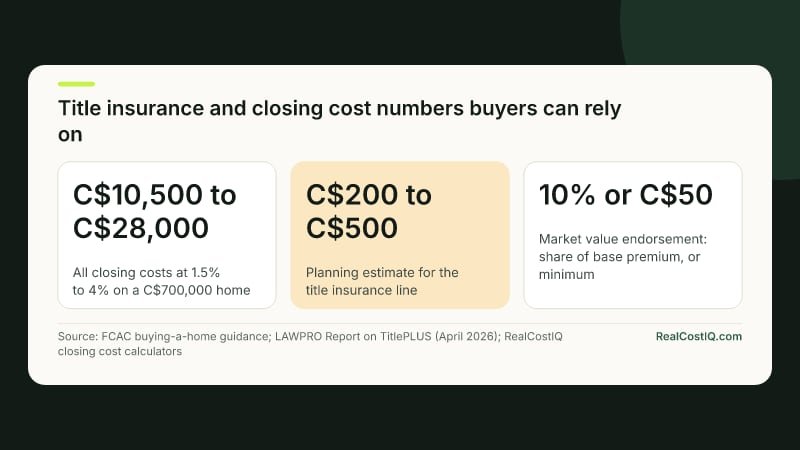 Home BuyingTitle Insurance or a Lawyer's Title Search When You Buy in Canada: What Each Does, What Title Insurance Does Not Cover, and Why Quebec Works DifferentlyA title search is work done before closing. Title insurance is a policy that pays for covered losses after. They are not substitutes, and in Quebec the land register works on a different principle. This is what each does in Ontario, British Columbia, Alberta and Quebec, from regulator, government and insurer texts read on 2026-10-12.21 min read
 Home BuyingBuying a New Home in Ontario: What the Tarion 1-, 2- and 7-Year Warranty Covers, Delayed-Closing Compensation, and How to Check a Builder's LicenceThe builder gives the warranty and Tarion backstops it: one year for workmanship, two for water and key systems, seven for major structural defects. Here is what each covers, the claim clock, the C$7,500 delayed-closing cap and the licence check.28 min read
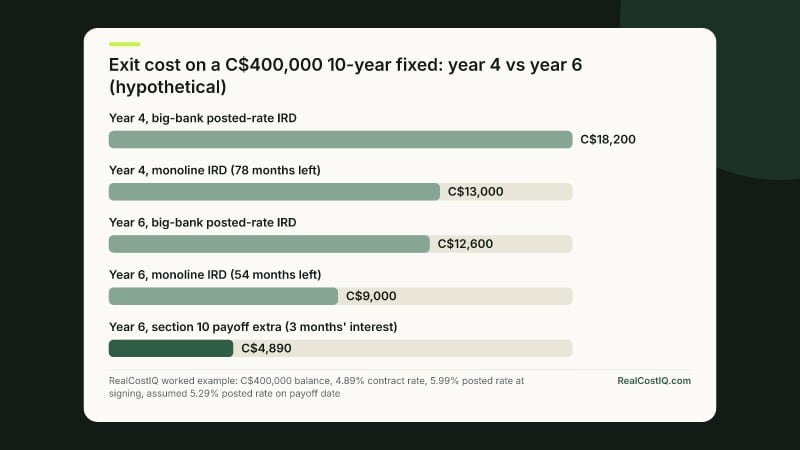 MortgagesThe Interest Act's Five-Year Rule: When a Canadian Mortgage Longer Than Five Years Can Be Paid Off for Three Months' InterestA 7- or 10-year mortgage is not a ten-year penalty trap. Section 10 of the Interest Act sets a statutory way out after year five, with exclusions for corporations and some business entities. Here is the text, the exceptions and a worked comparison in CAD.20 min read
 Home BuyingBuying With Conditions or Firm in Canada: Financing and Inspection Conditions, Where the Deposit Sits, and BC's Three-Business-Day Rescission RightIn British Columbia a buyer can walk away within three business days for 0.25% of the price, even on a firm offer. In the other provinces read, for a resale purchase, the protection is the condition you keep in the contract.18 min read
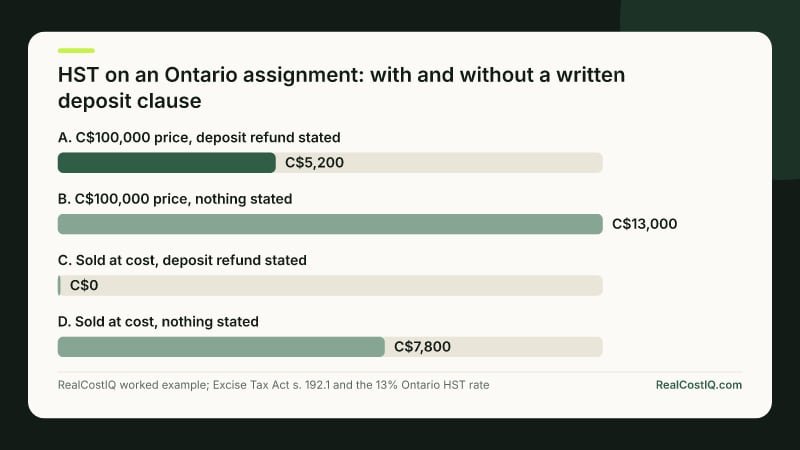 Home BuyingPre-Construction Assignment Sales in Ontario: HST on the Assignment Price, the Deposit Exception, Builder Fees and What the Buyer Can Claim BackSince 7 May 2022 an assignment of a new home or condo agreement is taxable even when an individual sells it. The tax lands on the whole price unless the assignment agreement states the deposit reimbursement in writing.18 min read
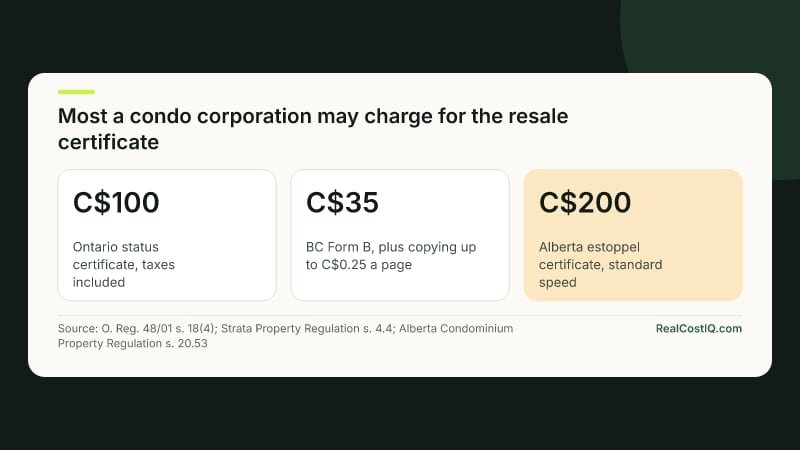 Home BuyingBuying a Resale Condo in Canada: The Status Certificate (Ontario), Form B (BC), the Estoppel Certificate (Alberta) and Quebec's EquivalentOntario caps the certificate at C$100 and gives the corporation 10 days. BC caps Form B at C$35 plus copying and gives one week. Alberta allows up to C$200. Quebec sets 15 days and no fee in the articles.21 min read
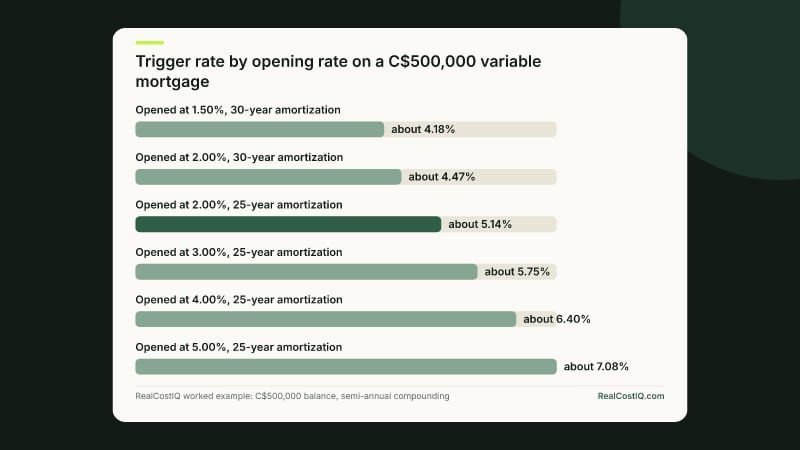 MortgagesVariable-Rate Mortgage With a Fixed Payment in Canada: Trigger Rate, Trigger Point, Negative Amortization and What Happens at RenewalOn a C$500,000 mortgage opened at 2.00% over 25 years, the payment stops covering interest at about 5.14%. What lenders do at that line, and at the trigger point, is in your contract.19 min read
 Property Taxes & FeesWhat It Costs to Sell a Home in Canada: Commission Plus GST/HST, Legal Fees, the Mortgage Payout and Who Pays WhatCommission, the tax on it, the mortgage payout and the legal work all come out of a seller's proceeds. How each is set, which ones the buyer pays instead, and a worked example in Canadian dollars with a hypothetical commission rate.25 min read
 Home InsuranceWhat Sets Your Home Insurance Premium in Canada, and the Water and Earthquake Risks a Standard Policy Leaves OutRebuild cost, the age of your wiring, plumbing and roof, your claims, your deductible and your distance to the fire hall set the price. Flood and earthquake are separate, optional and priced by location. Here is how to read the quote.22 min read
 MortgagesHow Canadian Lenders Count Your Income for a Mortgage: Salary, Bonus, Self-Employed and RentalTwo applicants with the same gross pay can qualify for very different mortgages. The difference is how each income type is counted, and the rules are published by the insurers.21 min read
 MortgagesLowest Mortgage Rate or a Flexible One? What a Restricted Canadian Rate Costs You When You Compare Two OffersA 0.15-point lower rate saves about C$3,580 over five years on C$500,000. One early exit on a restricted mortgage can cost more than that. Here is the arithmetic.20 min read
 Home BuyingBuying or Selling an Ontario Home With a Rented Water Heater or Furnace: The Contract, the Title Notice and the Buyout at ClosingWho inherits the rental contract, what an old notice of security interest means on title, and what a buyout costs at closing. Ontario rules read from the province's own pages on 2026-10-06.21 min read
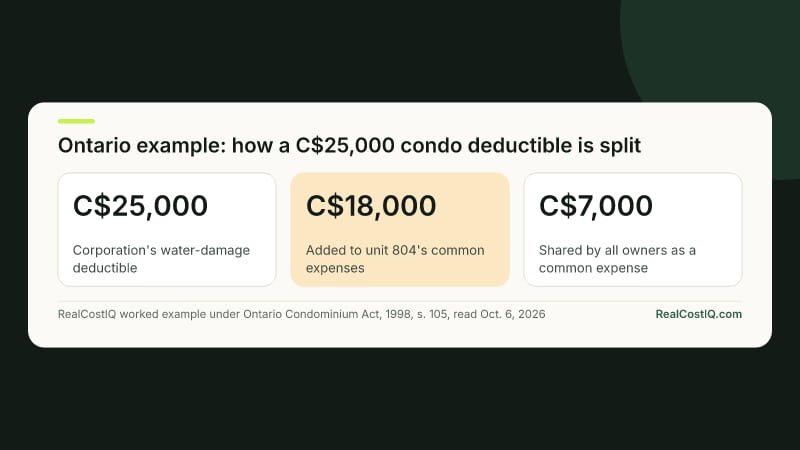 Home InsuranceCondo Insurance in Canada: What the Corporation's Policy Covers and the Deductible You Can Be ChargedThe corporation insures the building, but a water leak from your unit can put its whole deductible on your bill. How Ontario, British Columbia and Quebec each decide who pays, with worked examples in Canadian dollars.30 min read
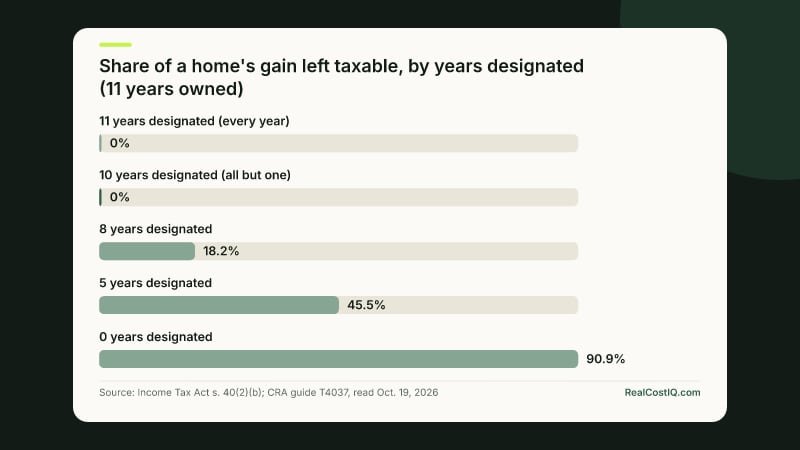 Property Taxes & FeesDo You Pay Capital Gains on Your Primary Residence in Canada? Rules for Homes and RentalsThe principal residence exemption, the plus-one year, adjusted cost base, the 12-month flipping rule, CCA recapture on rentals and non-resident withholding, with the arithmetic shown.23 min read
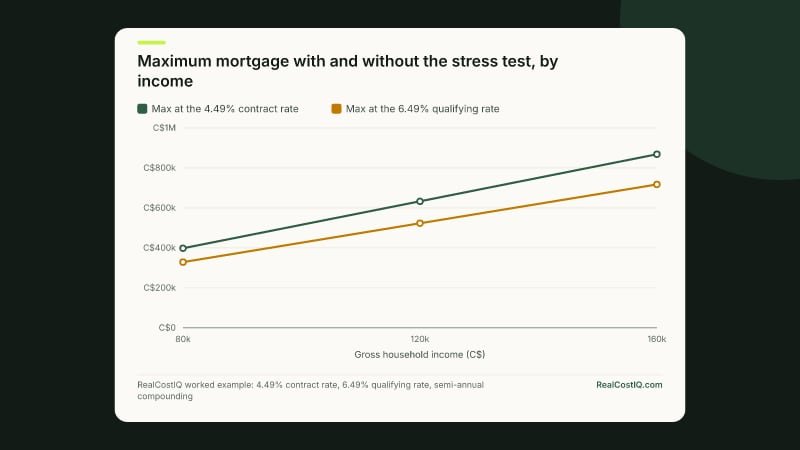 MortgagesMortgage Stress Test Canada 2026: Qualifying Rate, Renewals and Worked ExamplesThe stress test does not change your payment. It changes how big a mortgage a lender will approve. Here is the exact arithmetic, in CAD, at three incomes.21 min read
India
India blog → Mortgages30-Year Home Loan and Prepay, or 20 Years? What Each Choice Costs, and Whether a Part-Payment Should Cut Your EMI or Your TenureA 30-year loan with regular prepayments can match a 20-year loan, with a lower EMI to fall back on. We worked one ₹50 lakh loan through both routes, and through a ₹5 lakh part-payment that cuts either the EMI or the tenure.16 min read
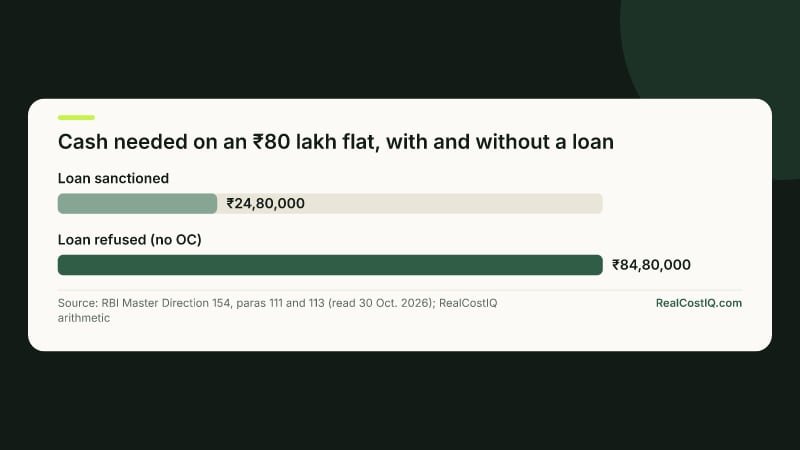 Home BuyingBuying a Flat Without an Occupancy Certificate: The Extra Charges, Loan Refusals and Risks in RupeesNo occupancy certificate can mean no bank loan, higher property tax and water bills, and a possession offer that is not valid. The rupee cost on an ₹80 lakh flat, with the sources.15 min read
 MortgagesHow Much Flat Can You Afford on ₹10, 15, 25 or 40 LPA? Loan, Down Payment, Stamp Duty and RegistrationA ₹10 LPA salary may support a flat of about ₹49 lakh to ₹61 lakh. A ₹40 LPA salary may support ₹1.64 crore to ₹2.05 crore. The loan is only part of it. Here is the cash you also need on day one.14 min read
 Home BuyingMOFA Carpet Area vs RERA Carpet Area: What Your Mumbai Flat Agreement Really Gives YouTwo laws define carpet area in Mumbai, and they do not agree on the balcony. Which one your flat uses decides what you can claim if the area falls short. Here are the rules, the orders, and a worked refund.13 min read
 Property Taxes & FeesSelling One Flat to Buy Another: The Capital-Gains Exemption Timeline in Months and RupeesIf you sell a flat and buy or build another, the Income-tax Act, 2025 can cut the tax on your gain to nil. The windows are in months, and one missed date turns the gain into tax. Here is the calendar, with rupee examples.16 min read
 MortgagesHome Loan Balance Transfer After the 2026 Rate Hike: How Many Months to Break Even?A cheaper rate does not pay for itself on day one. We worked a ₹50 lakh loan through a 0.25, 0.50 and 0.75 point cut, set the fees that SBI, HDFC Bank and ICICI Bank list against the saving, and counted the months to break even.17 min read
 MortgagesJoint Home Loan With a Parent: Age Caps, Tenure, Co-Ownership and How Much More You Can BorrowA parent's income can lift your home loan. A parent's age can shorten it. We worked a ₹70,000 earner and a parent on ₹30,000 through five ages, set against the age limits that SBI, HDFC Bank and ICICI Bank publish.16 min read
 MortgagesPaying for Interiors or a Renovation: Top-Up Home Loan vs Personal Loan vs Savings (₹8 Lakh Worked)A top-up has the lower rate. A personal loan has the shorter life. Savings have no EMI but a price all the same. We worked ₹8 lakh through each, using bank rate pages read on 28 October 2026.17 min read
 Home BuyingBuying a Resale Flat: The Bank Valuation Gap, Society Transfer Fee and What a Bank Asks of an Older BuildingA resale flat priced at ₹95 lakh and valued at ₹85 lakh needs about ₹7 lakh more of your own money. Here is the RBI loan-to-value maths, in rupees, and the checks for an older building.17 min read
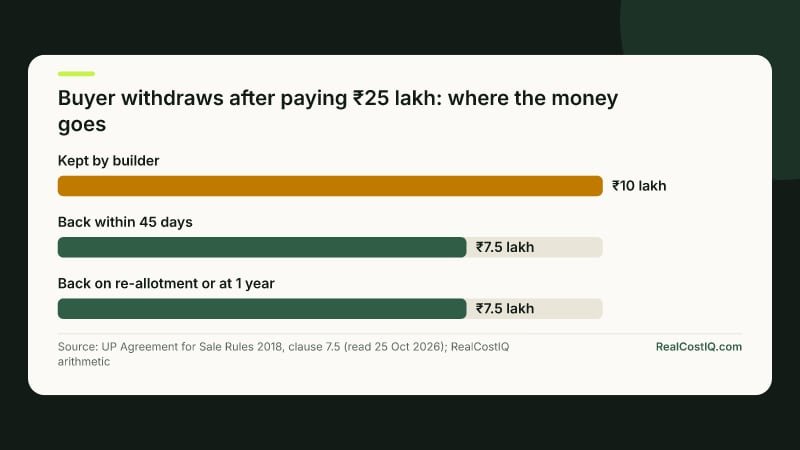 Home BuyingCancelling a Flat Booking: How Much the Builder May Keep, and When You Get Your Money Back With InterestWalk away after signing and the builder may keep the booking amount. Walk away because the builder failed and you get everything back with interest. We read the RERA Act and one state's model agreement and worked both exits in rupees.16 min read
 Property Taxes & FeesBuying a Flat From an NRI Seller: How Much TDS You Must Deduct, and Whether You Still Need a TAN (2026)On a ₹1 crore flat from an NRI, the buyer must hold back ₹14,30,000, not ₹1,00,000. A certificate can cut that to about ₹5,20,000. Since 1 October 2026 an individual buyer files on Form 141 with a PAN, and needs no TAN.16 min read
 Home BuyingBuying a Flat in Bengaluru With an A-Khata, B-Khata or No e-Khata: What It Costs and Why Banks Say NoOn a ₹75 lakh flat, an A-khata can mean ₹15,00,000 down and a ₹53,984 EMI. A B-khata may mean ₹30,00,000 down and a higher rate, if any lender says yes. We show the RBI rules and the numbers.15 min read
 Home BuyingBuying a Flat for Rental Income: Rental Yield vs Home Loan CostA ₹80 lakh flat that rents for ₹20,000 a month earns 3% before costs and about 2.2% after them. The ₹64 lakh loan costs 8.5%. We work out the monthly gap, the rent that closes it, and how long rent growth would take.15 min read
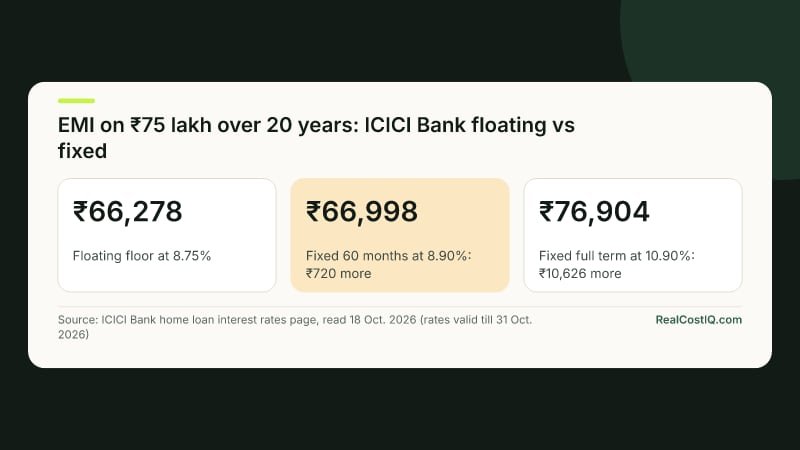 MortgagesFixed vs Floating Home Loan in India After the October 2026 Rate Hike: What the Premium CostsA five-year fixed rate costs about ₹720 a month more than the floating floor on a ₹75 lakh loan. A full-term fixed rate costs about ₹10,600 more. We work out how much the floating rate must rise before fixing pays, and what a bank's word fixed really covers.18 min read
 MortgagesEBLR vs MCLR: Should You Switch Your Home Loan Benchmark? (2026)Older home loans can sit on a bank's own MCLR. Newer ones sit on the RBI repo rate (EBLR). We worked a ₹40 lakh loan through the switch, set out what RBI's 2025 rules say, and listed the fee three banks publish.23 min read
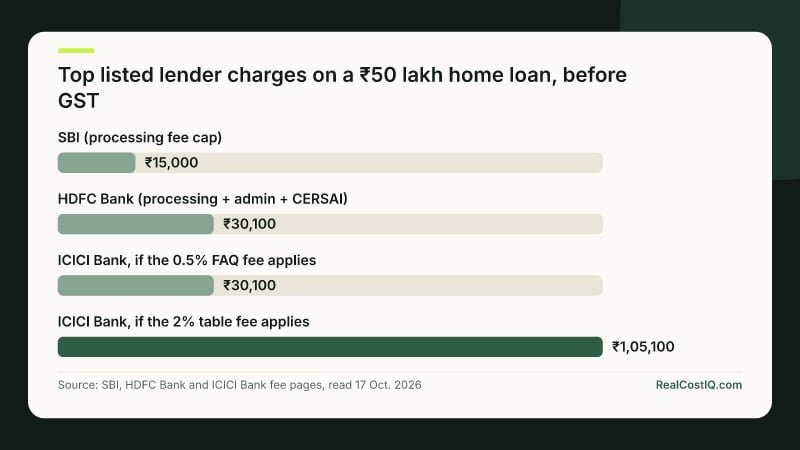 MortgagesHome Loan Processing, Legal and Technical Charges in India: The Full List (2026)A home loan costs more than its interest. We read the fee pages of SBI, HDFC Bank and ICICI Bank on 17 October 2026 and set every charge against a ₹50 lakh loan, with the gaps we found.17 min read
 Property Taxes & FeesHome Loan Tax Deductions in 2026-27: What Interest and Principal Save Under Each RegimeA ₹40 lakh loan can cut a self-occupied owner's tax by about ₹55,900 to ₹83,900 in year 1 under the old regime, and by nothing under the new one. We show the rules, the new section numbers and the year-by-year working.18 min read
 MortgagesHome Loan on a ₹50,000 Salary: How Much Can You Borrow?A ₹50,000 take-home salary usually supports a home loan of about ₹23 lakh to ₹32 lakh, and a flat of about ₹26 lakh to ₹41 lakh. The range is wide because banks use different limits. Here is each step, with tables for 20, 25 and 30 years.18 min read
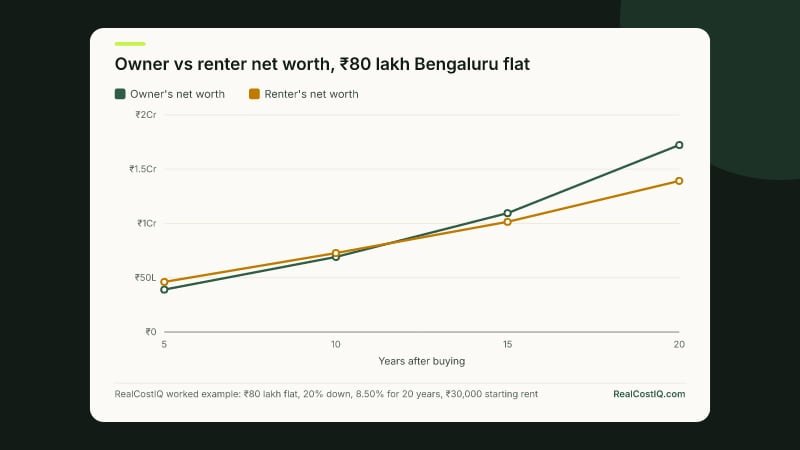 Home BuyingRent or Buy a Flat in India in 2026? Rent Yield vs Home Loan Rate in Three CitiesA flat that rents for 4.6% of its price a year is bought with a loan at 8.5%. We run an ₹80 lakh Bengaluru flat, then Mumbai and Delhi, and show the year buying finally pulls ahead and the four inputs that move it.18 min read
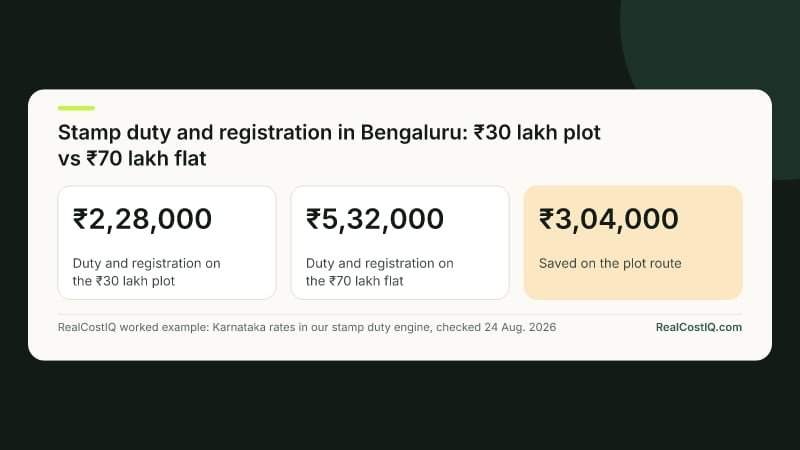 MortgagesPlot Plus Construction Loan vs Buying a Ready Flat: The Total Cost, Step by StepBuild your own house on a plot, or buy a finished flat for the same ₹70 lakh? We work through stamp duty, GST, the construction budget and the interest you pay before you move in, using one city, round numbers and RBI's rules.19 min read
 MortgagesRBI Raised the Repo Rate to 5.50%: How Much Your Home Loan EMI Goes Up, by Loan Size and TenureA quarter-point rise in the repo rate adds about ₹156 a month to the EMI for every ₹10 lakh you owe over 20 years. Here is the full table, from ₹20 lakh to ₹1 crore and from 15 to 30 years, plus what happens if a second hike follows.15 min read
 Home BuyingIf Your Builder Goes Insolvent: Where a Flat Buyer Stands Under the IBC, and What the 2026 Amendment ChangedA buyer who has paid a builder is a financial creditor under the Code, but filing, claiming and voting all run through rules most buyers never see. We read the Code, the 2026 amendment and its commencement notification, and the IBBI regulations.26 min read
 MortgagesMissed Home Loan EMI: What Happens at 30, 60 and 90 Days (SMA-1, SMA-2, NPA)A missed EMI starts a clock that RBI has written down to the day. We read the RBI texts and walk a ₹50 lakh loan through the SMA-0, SMA-1, SMA-2 and NPA dates, what clears the flag, and the limits on recovery calls.19 min read
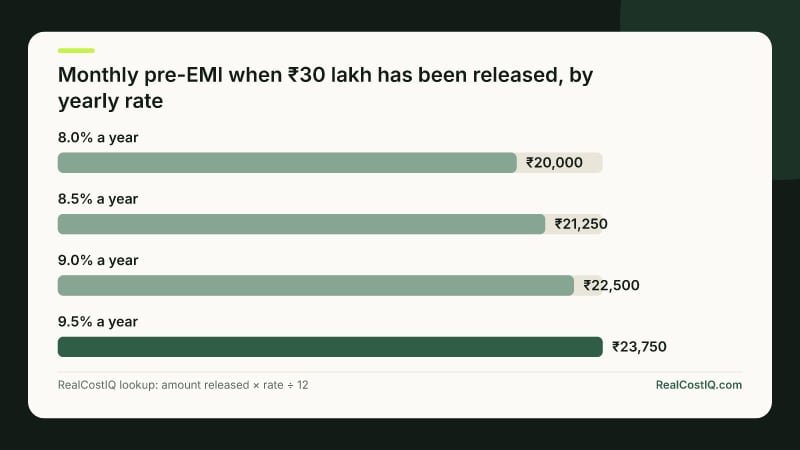 MortgagesPre-EMI vs Full EMI on an Under-Construction Flat: What You Pay Before Possession and What It Costs Over the LoanRBI says a home loan for an unfinished flat must be released in line with construction stages. That is why you pay pre-EMI on a growing balance. We walk a ₹60 lakh loan through three ways of carrying it and show what each costs.18 min read
 MortgagesCan Your Bank Force Home-Loan Insurance on You? What RBI's Conduct Directions Change from 1 January 2027From 1 January 2027, banks, NBFCs and housing finance companies may not make your loan conditional on buying a third-party product such as insurance. We read the directions and set out who is covered, what you can ask for, and what a financed premium costs.18 min read
 MortgagesWhen Your Home Loan Rate Resets: EMI or Tenure, and What RBI Rules Let You DoA rate rise gives you three levers: a higher EMI, a longer tenor, or a part-prepayment. We worked a ₹50 lakh loan through each and set out what the RBI's own circulars say the lender must offer, disclose and not charge.27 min read
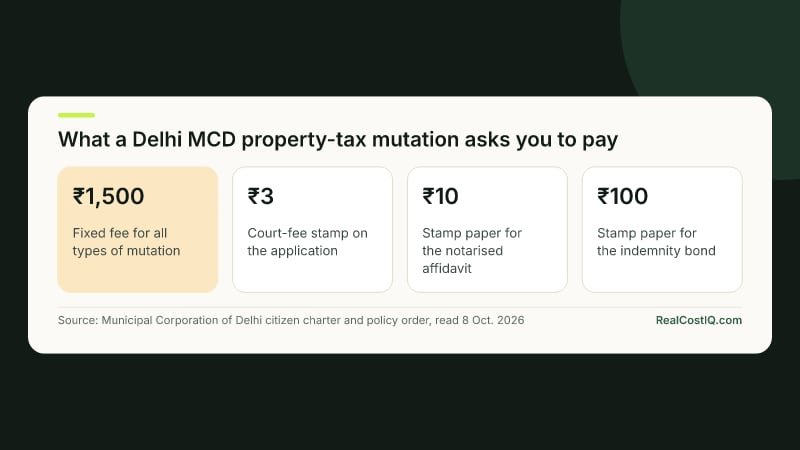 Home BuyingMutation After You Buy Property in India: What Karnataka, Telangana, Uttar Pradesh and Delhi RequireRegistration moves the title. Mutation moves the name in the record that the tax office, the Tahsildar and your lender read. We read four states' laws and say what each one asks of the buyer, and what we could not read.19 min read
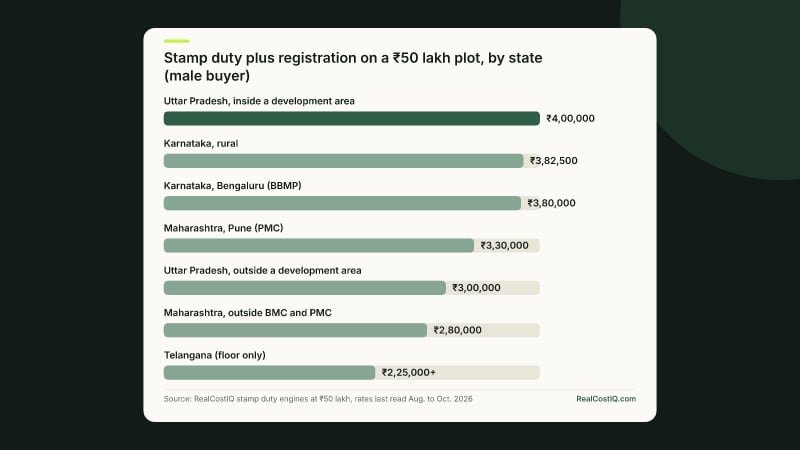 Property Taxes & FeesPlot Registration Charges by State: Stamp Duty 4% to 7%, Plus Who May Buy Agricultural Land and Conversion RulesA plot is not a flat. The state decides who may buy agricultural land, whether it must be converted before you build, and what the sub-registrar charges. We read the statutes for four states and priced a ₹50 lakh plot in each.26 min read
 Property Taxes & FeesBuying or Selling Below the Circle Rate in India: Stamp Duty, Seller Tax and Buyer TaxSell a flat for ₹80 lakh when the circle rate says ₹90 lakh and three bills change at once: stamp duty on ₹90 lakh, the seller's capital gain on ₹90 lakh, and the buyer's income on ₹10 lakh. Here is how each works, with the 10% tolerance and the 2025 Act section numbers.23 min read
 Renovation & RepairWhat a Modular Kitchen Quote in India Includes Beyond the CabinetsA per-square-foot kitchen quote prices the cabinets. The chimney, hob, sink, countertop, civil work and GST usually sit outside it. We priced what we could from the makers' own pages and say plainly where we could not.19 min read
 Home BuyingIFMS, Corpus Fund, Advance Maintenance and the Society Transfer Fee: What a Builder or Society Can Charge YouThe interest-free maintenance deposit is not a refund to you, a corpus fund is three different things, and Maharashtra's draft bye-laws cap a resale premium at ₹25,000. We read the rules and mark what no rule caps.20 min read
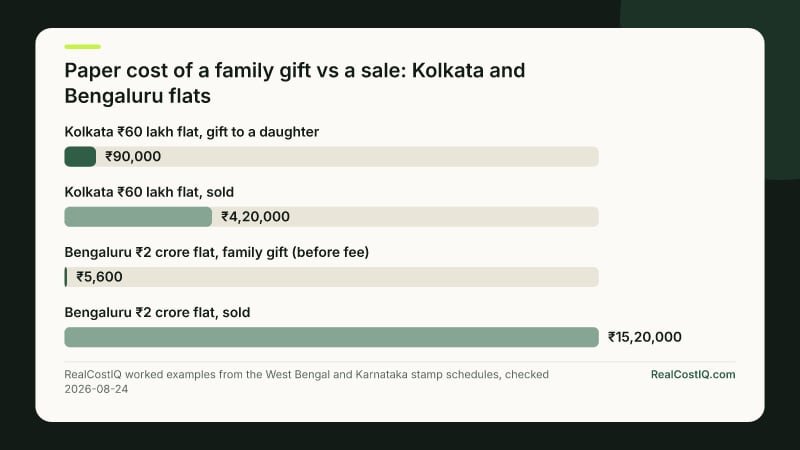 Property Taxes & FeesGift Deed vs Will vs Partition vs Release Deed: Transferring Property in the FamilyA Maharashtra gift to a daughter pays ₹200 stamp duty; the same flat gifted in Bengaluru pays ₹5,000 plus cess. We compare the four family instruments on cost, revocability, tax and what the donee inherits.27 min read
 Home BuyingThe True Cost of Buying a Flat in India: Every Charge Beyond the Sticker PriceA ₹1 crore flat is rarely a ₹1 crore cheque. Stamp duty by state, 5% GST on under-construction homes, TDS, brokerage and the charges that vary by project, line by line.24 min read