A mortgage payment has two moving parts. Your servicer is the company that collects your payment. On a fixed-rate loan, principal and interest stay the same. The escrow part does not. Escrow is your servicer's estimate of next year's property tax and homeowners insurance bills, divided by 12. It also includes any money needed to refill the account. When either bill rises, or when last year's estimate fell short, the escrow part goes up. That happens even though your loan terms never changed. This article explains the rule your servicer follows. It shows the math behind the new number. It also shows where you have real choices. If the parts of a mortgage payment are new to you, start with what PITI means.
Paid the shortage and the payment still rose: the two parts of the increase
Many people pay the shortage and then see the payment stay high. They think the servicer made a mistake. Usually it did not. A new payment has two separate parts. One is the higher monthly escrow for next year's bills. The other is the shortage, spread over 12 months. Paying the shortage removes only the second part. The first part stays because the bills really went up.
| Part of the increase | Monthly amount | What ends it |
|---|---|---|
| Higher tax and insurance ($8,700 a year instead of $7,200, divided by 12) | +$125.00 | Only lower bills |
| Shortage repayment ($875 divided by 12) | +$72.92 | Paying it off, or 12 months |
| Total increase if you pay nothing up front | +$197.92 | |
| Total increase if you pay the $875 up front | +$125.00 | Still there |
Figures from the illustrative household in the worked example below: $1,850 principal and interest, escrow bills up from $7,200 to $8,700 a year. A lump sum cuts the payment from $2,647.92 to $2,575.00. It cannot bring it back to $2,450.00.
So if your payment is still higher after you pay, compare the new monthly escrow with your real bills. If the bills match, the servicer is right. The only fix is to lower the bills themselves, which the sections on property tax appeals and insurance shopping below cover.
How the annual escrow analysis works
Servicers hold escrow money in an account. They pay your tax and insurance bills from it. The CFPB (Consumer Financial Protection Bureau) describes an escrow account as a reserve funded by a portion of each monthly mortgage payment. This lets the lender spread large bills into manageable monthly amounts. RESPA (the Real Estate Settlement Procedures Act) and its rule, Regulation X, govern how the account is run: 12 CFR 1024.17.
Once per escrow computation year, the servicer runs an analysis. The computation year is the yearly period the servicer uses to track the account. The servicer projects the bills it expects to pay over the next 12 months. It projects the month-by-month balance, given your current payment. Then it finds the lowest point that balance reaches. Regulation X requires servicers to use the aggregate accounting method. That means taxes and insurance are pooled in one balance, not tracked item by item. Within 30 days after the end of the computation year, the servicer must send you an annual escrow statement. It shows the account history, the projection, and your current and new monthly payments. It also explains any shortage or deficiency.
The cushion: one-sixth, or two months
A servicer may build a cushion into the target balance. The cushion keeps a slightly higher bill from pushing the account negative. The rule caps the cushion at no more than one-sixth of estimated total annual disbursements. That equals two months of escrow-paid bills. Disbursements are the payments the servicer makes from the account. The cap is a ceiling, not a requirement. Your mortgage contract or state law can set a lower cushion. Where federal or state law gives a lower amount, the lower amount controls.
| Annual tax + insurance | Monthly escrow (÷12) | Maximum cushion (÷6) |
|---|---|---|
| $4,800 | $400 | $800 |
| $7,200 | $600 | $1,200 |
| $8,700 | $725 | $1,450 |
| $12,000 | $1,000 | $2,000 |
Arithmetic on the one-sixth ceiling in 12 CFR 1024.17. Your actual cushion can be lower than the ceiling.
Surplus, shortage and deficiency are three different things
Regulation X defines these terms precisely, and servicer letters often blur them. A shortage is the amount by which the current escrow balance falls short of the target balance. A deficiency is the amount of a negative balance in the account. It means the servicer has already paid bills with money it advanced. A surplus is the reverse: the balance is above the target. If a surplus is $50 or more, the servicer must refund it within 30 days of the analysis, as long as you are current on the loan. Below $50, it may refund the surplus or credit it.
| Situation | What the rule allows | Source paragraph |
|---|---|---|
| Shortage smaller than one month's escrow payment | Do nothing, require repayment within 30 days, or spread it over at least 12 months | §1024.17(f)(3)(i) |
| Shortage of one month's escrow payment or more | Do nothing, or require equal monthly payments over at least 12 months. No demand for a lump sum | §1024.17(f)(3)(ii) |
| Deficiency smaller than one month's escrow payment | Do nothing, require repayment within 30 days, or collect in two or more equal monthly payments | §1024.17(f)(4)(i) |
| Deficiency of one month's escrow payment or more | Do nothing, or require repayment in two or more equal monthly payments | §1024.17(f)(4)(ii) |
| Surplus of $50 or more | Refund within 30 days if you are current | §1024.17(f)(2)(i) |
Paragraph citations and thresholds as read in the CFPB's published text of 12 CFR 1024.17 on 2026-10-05. A servicer can be more generous than the rule, and your state may add protections.
Why shortages have become common
A shortage appears when the bills the servicer actually paid, or must now pay, are larger than the estimate behind your old payment. The estimate is set once a year. So any mid-year increase lands as a shortage at the next analysis. Two inputs have been moving the wrong way.
Property taxes
ATTOM's 2025 annual property tax analysis found $396.8 billion in property taxes levied on 89.6 million single-family homes. That was up 3.7 percent from 2024. The average single-family bill was $4,427, up 3 percent. The national effective tax rate, which is tax paid as a share of home value, rose to 0.9 percent from 0.86 percent. That is the highest since 2020. ATTOM noted that half of metro areas saw increases above the national average. Among the largest metros, Memphis led at 34 percent and Baltimore followed at 27 percent. The national average hides a lot. If your county reassessed or a levy passed, your increase can be several times that.
Homeowners insurance
The Insurance Information Institute (III), citing data from the National Association of Insurance Commissioners (NAIC), reports that the average homeowners premium rose 11.2 percent in 2022. It went to $1,569 from $1,411, after a 7.6 percent rise the year before. The III page's latest year of data is 2022. More recently, the NAIC's 2018 to 2024 market analysis (released Aug. 5, 2026) found inflation-adjusted average premium increases of 18.3 to 43.3 percent since 2018, as a range across NAIC regions; it publishes no national figure. That works out to 2.4 to 5.3 percent a year. It also found company-initiated non-renewals up between 96 and 216 percent, depending on region. A non-renewal is when the insurer ends your policy. The NAIC also found 715 companies writing homeowners coverage in 2024. A non-renewal matters for escrow. A replacement policy often costs more, and the new premium becomes the new escrow target.
The two effects stack. Say a tax bill rises 3 percent and an insurance premium rises 10 percent in the same year. On the bills alone, that can raise a $600 escrow payment by roughly $30 a month. The shortage on top of that is the part that surprises people. For the premium side in detail, see our home insurance cost guide.
Worked example: from $2,450 to $2,648
This is an illustrative household, not a real borrower. All figures are made up to show how the cushion and the 12-month spread work.
- Principal and interest: $1,850 a month, fixed.
- Last year's escrow estimate: $4,800 tax + $2,400 insurance = $7,200, or $600 a month.
- New bills after a reassessment and a premium renewal: $5,400 tax (two $2,700 installments) + $3,300 insurance = $8,700 a year.
- Old total payment: $1,850 + $600 = $2,450.
Step 1: new monthly escrow on the bills alone
$8,700 ÷ 12 = $725. That is $125 more than before, entirely from the higher bills ($8,700 minus $7,200 is $1,500, divided by 12).
Step 2: the cushion ceiling
$8,700 ÷ 6 = $1,450, the most the servicer may target as a cushion.
Step 3: project the balance
Say the bills come due in month 4 (tax, $2,700), month 7 (insurance, $3,300) and month 12 (tax, $2,700). You deposit $725 a month. Measured against the starting balance S, the lowest point of the year is month 7:
| Month | Deposits to date | Bills paid to date | Balance |
|---|---|---|---|
| 3 | $2,175 | $0 | S + $2,175 |
| 4 | $2,900 | $2,700 | S + $200 |
| 6 | $4,350 | $2,700 | S + $1,650 |
| 7 | $5,075 | $6,000 | S − $925 (lowest) |
| 10 | $7,250 | $6,000 | S + $1,250 |
| 12 | $8,700 | $8,700 | S |
Deposits of $725 a month against the bill schedule above. The lowest projected balance is S minus $925.
Step 4: compare against the target
To end the lowest month at the full $1,450 cushion, the account needs S = $925 + $1,450 = $2,375 at the start of the projection. Say the account will actually hold $1,500. Then the shortage is $2,375 − $1,500 = $875. That is more than one month's escrow payment ($725). So under §1024.17(f)(3)(ii), the servicer can only require it as equal payments over at least 12 months.
Step 5: the new payment
$875 ÷ 12 = $72.92. New escrow payment: $725 + $72.92 = $797.92. New total: $1,850 + $797.92 = $2,647.92, an increase of about $198 a month. Of that, $125 is the higher bills and $73 is the shortage repayment.
| Component | Before | Months 1-12 after | Month 13 on (bills flat) |
|---|---|---|---|
| Principal and interest | $1,850.00 | $1,850.00 | $1,850.00 |
| Tax + insurance (÷12) | $600.00 | $725.00 | $725.00 |
| Shortage repayment | $0.00 | $72.92 | $0.00 |
| Total payment | $2,450.00 | $2,647.92 | $2,575.00 |
Illustrative figures. After 12 months the shortage is repaid and the payment steps down, but only if the bills do not rise again, which is the assumption that most often fails.
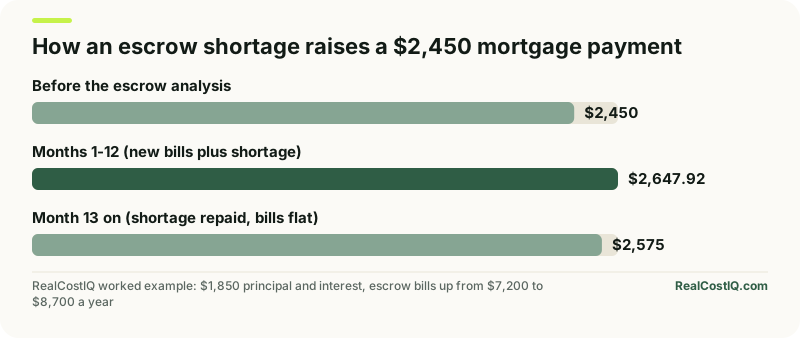
To rerun this with your own principal, rate and escrow, use the mortgage calculator. It separates principal and interest from taxes and insurance, so you can see how much of the payment is escrow.
Your first escrow analysis after buying
New owners get hit hardest. When you closed, the lender set your escrow from the bills it could see. For a resale, that is usually the seller's tax bill. But the seller's bill may not be yours. In many places a sale lets the county reset the assessed value to your purchase price. When that happens, the new bill can be much higher than the old one. The first annual analysis then shows a shortage.
New construction works the same way, with a twist. The first bill may cover only the land. When the county adds the finished house, the bill jumps. California's State Board of Equalization (BOE) explains that a change in ownership or completed new construction lets the county reappraise the property right away. The difference becomes a supplemental bill. The BOE also says that bill goes to the owner. The lender does not get it, even when it pays your annual taxes through an impound account. Other states have their own rules, so ask your county assessor how a sale or a new build changes your bill.
How to check the servicer's analysis
Servicer escrow math is usually right, but the inputs can be wrong. A wrong input flows straight into your payment. Work through the annual statement in this order.
- Check the projected bills against the actual bills. Pull your county tax bill and your insurance declarations page. The statement should list the same amounts and due dates. A common error is an old insurance premium. Another is a tax figure from before an exemption was applied.
- Check for items that should not be there. If you changed insurers, make sure the old policy is not still being paid. Also make sure any removed private mortgage insurance (PMI) is not still collected through escrow.
- Check the cushion. Compute one-sixth of the projected annual total. Compare it to the cushion the statement implies. If it is above the ceiling, ask the servicer in writing why.
- Check the starting balance. The projection's opening balance should match your actual escrow balance on the analysis date. Suppose the servicer already advanced money for a bill you paid yourself. Then it will show a lower balance than the truth.
- Check the repayment term. For a shortage of one month's escrow payment or more, the spread should be equal monthly amounts over at least 12 months. Confirm that the number of months times the monthly amount equals the shortage.
- Check the date. The annual statement is due within 30 days after the end of the computation year. The new payment takes effect with a notice period set by the servicer. Find the effective date and the first payment due at the new amount.
If something does not match, the CFPB advises contacting your servicer first. Keep records of discrepancies. For a formal dispute, send a notice of error or information request, which the CFPB describes as a letter disputing the error. If the problem persists, it points to housing counselors, the HOPE Hotline at (888) 995-4673, and filing a CFPB complaint. The CFPB lists two warning signs to watch for. One is unexpected payment changes without notice. The other is force-placed insurance charges. Force-placed insurance is coverage the servicer buys at your cost when it thinks yours has lapsed.
Lump sum or spread over 12 months?
The rule lets you choose. Which is better depends on what the cash would otherwise do. Spreading the $875 shortage means paying $72.92 a month for 12 months. At any moment during that period you hold, on average, roughly half of the $875 that you would have handed over up front. Say that money sits in a savings account earning 4 percent. That is an assumed figure for illustration, so use your own. The benefit is about $19 over the year. That is not nothing, and it is not much.
The case for paying a lump sum is mostly about your monthly budget and about removing a risk. A lump sum lowers the new payment right away, to $725 in the example. That matters if a lender is reviewing your debt-to-income ratio for a refinance or a second loan. The ratio compares your monthly debts to your monthly income. A lump sum also removes the chance that you forget the spread is temporary and misjudge your budget.
| Your situation | Better move | Why |
|---|---|---|
| Cash is tight and the shortage is under a few hundred dollars | Spread it over 12 months | Lowest immediate cost; the rule guarantees at least 12 months for a shortage of one month's payment or more |
| You have idle savings earning a low rate and the shortage is large | Pay a lump sum, or part of it | A lower monthly payment and no repayment tail |
| Savings earn well above zero and you would not miss the monthly amount | Spread it, and set a calendar reminder for month 13 | You keep the cash working until each installment is due |
| Applying for a refinance or loan in the next few months | Pay a lump sum if you can | The shortage installment inflates your monthly payment on a lender's debt-to-income calculation |
| Servicer demands the full shortage within 30 days | Check the amount against one month's escrow payment first | If you are current, a shortage at or above one month's escrow payment may only be spread over 12 months or more |
| The bills themselves are wrong or inflated | Dispute before paying anything extra | Fixing the input shrinks both the new escrow payment and the shortage |
| You are behind on the mortgage | Call the servicer before the due date | Rules on the shortage can differ if you are delinquent, and loss mitigation options matter more than the escrow item; if the cause is a layoff, see forbearance, modification and loss mitigation after a layoff |
Lowering the bills that cause the shortage
Repayment only moves the problem across 12 months. The lasting fix is to shrink the bills that feed the account.
Appeal the property tax assessment
Your county or state sets the deadlines, forms and standards for an assessment appeal. So we cannot give a single national procedure. Do not assume any filing fee or success rate. Some things are consistent. The appeal window is short, and the assessment notice usually opens it. The strongest evidence is recent sales of comparable homes that sold for less than your assessed value. That is the value the county uses to set your tax. Factual errors also help, such as wrong square footage or bedroom count. The appeal covers the assessed value, not the tax rate. You can estimate what a lower assessment is worth with our property tax calculator. Say a successful appeal cuts the bill after the servicer has already built the higher number into your payment. Then send the revised bill to the servicer and ask for a re-analysis.
Shop the insurance
Premiums for the same house vary widely between carriers. The III reports a range of $893 to $2,677 across states for the average premium in 2022. This shows how local the market is. Price the same coverage limits and deductible across several insurers a few weeks before your renewal. The deductible is the amount you pay before insurance pays. Consider raising it only if you could pay it from savings. Estimate where your premium should land with the home insurance cost calculator. Send the new declarations page to the servicer as soon as you switch. Then escrow pays the new policy and not the old one.
Can you drop escrow altogether?
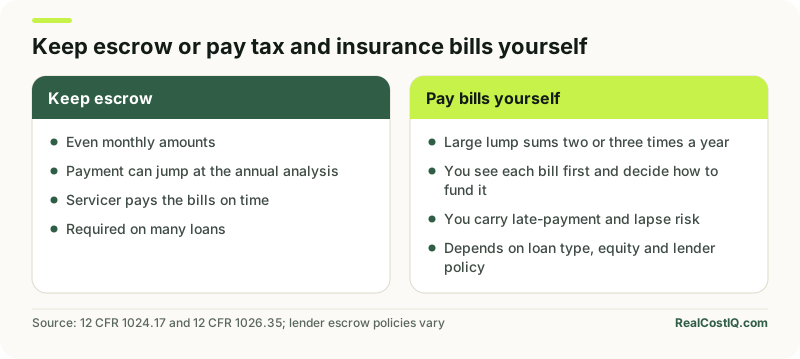
Removing escrow does not remove the bills. It means you pay them yourself in lump sums. That is typically twice a year for taxes and once for insurance. For a shortage-prone account, that can feel like control. It also makes you responsible for budgeting a $2,700 tax installment on a specific date.
Federal rules set a floor only for higher-priced mortgage loans. Under 12 CFR 1026.35, those loans must keep escrow until the earliest of two events. One is the debt ending. The other is a cancellation request from the borrower, received no earlier than five years after closing. Even then, cancellation requires that the unpaid principal balance be below 80 percent of the original property value. The borrower must also not be delinquent or in default. The rule exempts some transaction types. These include cooperative shares, initial construction financing, short-term bridge loans, reverse mortgages and PACE (property assessed clean energy) transactions. It also exempts some small creditors.
For a standard conventional loan, no one national rule covers whether you can waive escrow, when, or at what price. Your lender's and the investor's policy sets it. Ask your servicer for its written escrow-removal conditions. Expect questions about equity, payment history and whether taxes or insurance are due soon. Expect some items to be handled differently, such as flood insurance in a mapped flood zone or private mortgage insurance. Check your loan estimate or closing disclosure for any escrow waiver fee before you assume it is free. Removal also does not erase your obligation. A missed tax or insurance bill becomes your problem. Your loan documents set what the lender can do about it. The PMI calculator shows how long you are likely to carry mortgage insurance. That often ends around the time waiving escrow becomes realistic.
| Factor | Keep escrow | Pay bills yourself |
|---|---|---|
| Cash flow | Even monthly amounts | Large lump sums twice or three times a year |
| Surprise risk | Payment can jump at the annual analysis | Bills still rise, but you see them first and decide how to fund them |
| Missed-bill risk | Servicer pays on time | You carry late-payment and lapse risk |
| Who earns the float | Held in the escrow account until bills are due | You, if you reserve the money in savings |
| Availability | Required on many loans | Depends on loan type, equity and lender policy |
A short action plan
- Read the annual escrow statement, not just the payment-change letter. Find the shortage, the cushion and the projected bills.
- Match every projected bill to a real tax bill and declarations page.
- If a figure is wrong, send a written notice of error to the servicer and keep proof of mailing.
- If the figures are right, decide between a lump sum and the 12-month spread using the decision table above.
- Appeal the assessment if comparable sales support it, and shop your insurance before the next renewal.
- Put a reminder in the calendar for the month after the spread ends, and another for the next annual analysis.